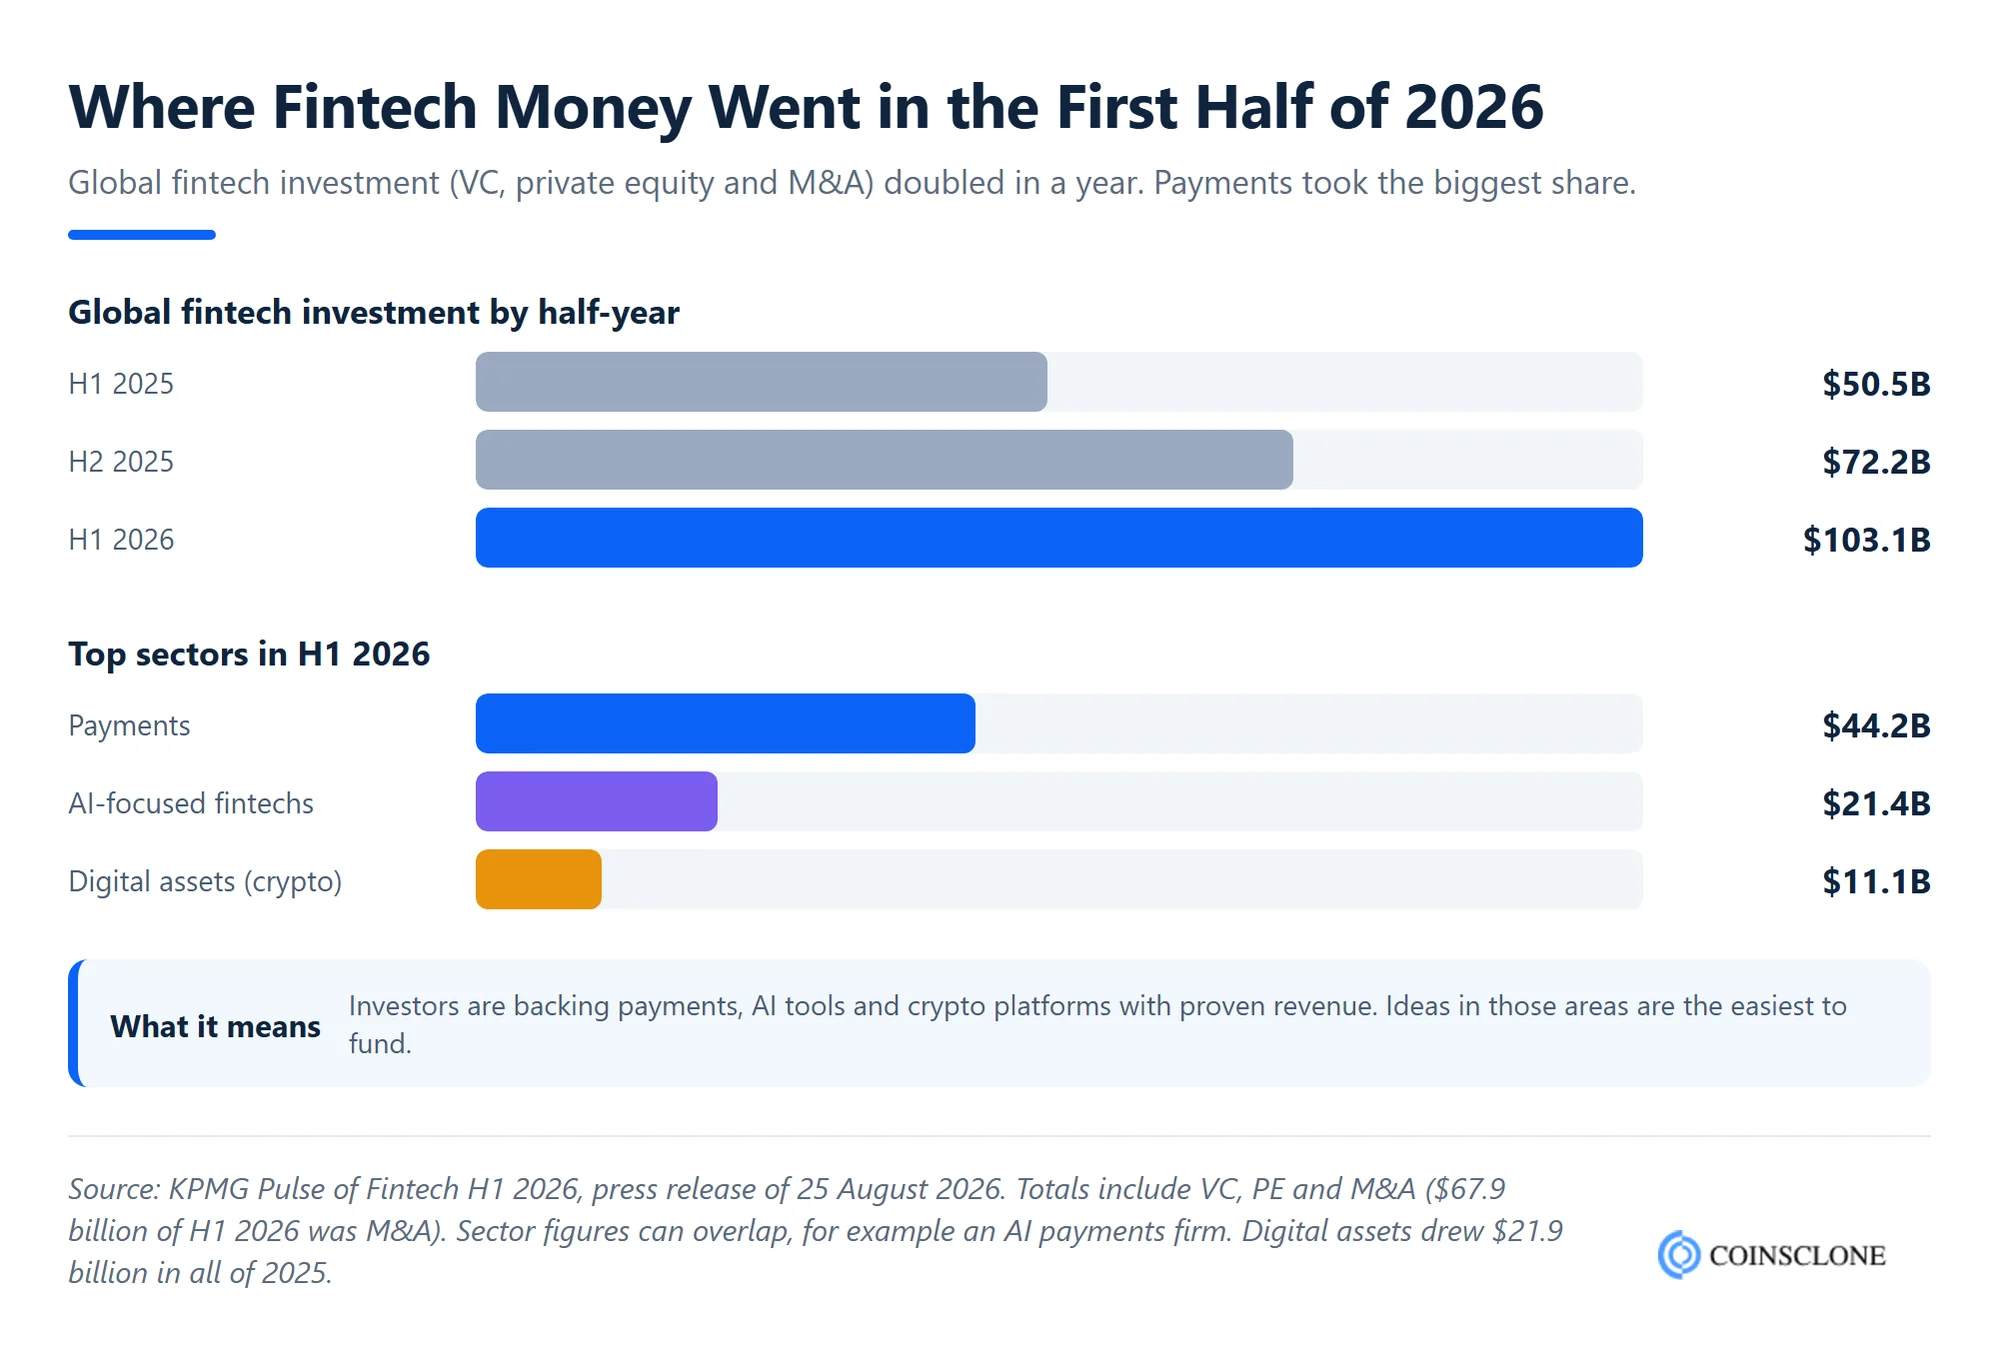
Fintech business ideas are easier to judge in 2026, because the market now shows which models pay. Investors put $103.1 billion into fintech in the first half of 2026, per KPMG, and most of it went to payments, AI and crypto. Public fintechs such as Robinhood and Chime also report how they make money each quarter, so you can see what works before you build.
This guide lists 16 fintech business ideas for startups, from crypto exchanges and digital banks to stablecoin payments and tokenized assets. For each idea, you get a short overview, real examples, key features and the ways it makes money. After the list, we compare the ideas side by side, show which licence each one needs, and share cost ranges and a simple path from idea to MVP.
In this guide:
- 16 fintech business ideas, each with examples, features and revenue streams
- Where fintech funding went in 2026, and how two public fintech apps really earn
- A side-by-side table and a licence decision tree for every idea
- Cost and time ranges for a fintech MVP, plus a simple way to test an idea first
16 Fintech Business Ideas for Startups in 2026
Tech has changed how people pay, save, borrow and invest. Each idea below solves one money job better than a bank branch does. We kept the strongest ideas from earlier years, removed ones that are not really fintech, and added three that grew fast in 2026.
1. Starting a Crypto Exchange Platform
Overview
A crypto exchange lets users buy, sell and trade Bitcoin and other coins. It is the front door to crypto for most people, so it is one of the largest earning fintech business ideas. The whole crypto market was worth about $2.9 trillion on 2 October 2026, with close to $100 billion traded each day, per CoinGecko. Even a small share of that volume can pay well.
Examples
Binance, Coinbase, Kraken, OKX and Bybit are popular crypto exchanges. Each has a wide user base and a loyal community behind its success.
Key features
- Trading engine: An order book and matching engine fill buy and sell orders in milliseconds.
- Security: Cold storage, two-factor login and DDoS protection keep funds and data safe.
- APIs: Market data and liquidity APIs connect the exchange to other platforms, so the order book is never empty.
- Clean user panel: A simple dashboard brings in new traders and keeps them active.
- Trading modes: Spot, P2P (peer-to-peer) and OTC (over-the-counter) trading suit different users.
How It Makes Money
Trade fee: The exchange takes a small fee on every trade.
Withdrawal fee: Users pay a small fee to move crypto out of the platform.
Deposit fee: Some exchanges charge a fee when users add fiat money by card.
Margin trading: Users borrow funds to bet on price moves, and the exchange charges fees and interest on the loan.
Crypto staking: The exchange stakes coins for users and keeps a share of the rewards.
Token launchpad: New projects pay a listing or launch fee to sell their tokens to the exchange’s users.
A white label crypto exchange is the fastest way in. Coinsclone ships one in 4 to 6 weeks, or 7 to 10 weeks with fiat payment rails.
2. Initiating a DeFi or Decentralized App
Overview
DeFi (decentralized finance) apps run on blockchains through smart contracts. Users can swap, lend, borrow and earn without a bank in the middle, and every trade is open to see on-chain. About $95 billion sat in DeFi apps on 1 October 2026, per DefiLlama. Over the past year, DeFi swap apps earned about $3.15 billion in fees and lending apps about $1.65 billion.
Examples
Uniswap, Aave, PancakeSwap, Compound and Curve are leading DeFi apps. They offer swaps, lending, staking and liquidity pools.
Key features
- Wallet login: Users connect a wallet instead of opening an account, so they can start in seconds.
- User control: Users keep their own keys and stay in charge of their funds.
- Passive income: Staking, lending and liquidity pools let users earn on assets they hold.
- Many use cases: DAOs, lending, gaming and on-chain insurance all run on DeFi.
How It Makes Money
Swap fee: The app takes a small fee when users swap one coin for another.
Staking fee: The platform keeps a small share of staking rewards. If a user breaks a stake early, a penalty fee also adds to revenue.
Native token: A platform token unlocks key features, fee discounts and voting, which drives demand.
IDO: An Initial DEX Offering lets new projects raise funds on your platform, and you charge them a launch fee.
Also Read: How to Build a DeFi App
3. Starting a Digital Wallets Business
Overview
Digital wallets store cards, cash balances or crypto keys inside an app. They let people pay with a tap or a QR code instead of cash or a plastic card. Crypto wallets do one more job: they hold the keys that move coins on the blockchain. Many wallets now earn from built-in swaps. Over the past year, Phantom earned about $114 million and MetaMask about $50 million in such fees, per DefiLlama.
Examples
- Payment wallets: Apple Pay, Google Pay and PayPal.
- Crypto wallets: MetaMask, Trust Wallet and Phantom.
Key features
- Fast checkout: Tap, scan or click to pay in seconds.
- Strong key safety: Biometrics, secure chips and MPC (key sharing) protect funds even if a phone is lost.
- Contactless pay: Users pay without handing over cash or cards.
- QR codes: Users scan to send and receive money quickly.
- Rewards: Cashback and coupons keep users coming back.
How It Makes Money
Transaction fee: A small fee on each payment or transfer.
In-app swap fee: Crypto wallets add a small fee when users swap tokens inside the app.
Withdrawal fee: Some wallets charge a fee to cash out to a bank.
Merchant fee: Shops pay a small cut to accept payments from the wallet.
Also Read: How much does it cost to develop a crypto wallet?
4. Launching an NFT Marketplace
Overview
NFT marketplaces let users mint, list, buy and auction NFTs (non-fungible tokens). The hype of 2021 has gone, and the art market is far smaller now. NFT marketplaces earned about $0.41 billion in fees over the past year, against $3.15 billion for crypto swap apps. Most of that came from Telegram’s Fragment, which sells usernames and numbers. So the 2026 NFT idea is niche: tickets, game items, memberships and digital IDs, not profile pictures.
Examples
OpenSea, Magic Eden, Blur and Rarible are leading NFT marketplaces. OpenSea now charges a 1% fee per sale.
Key features
- Easy minting: Creators turn files into NFTs in a few clicks.
- New income for creators: Artists, musicians and brands earn royalties on every resale.
- On-chain proof: The blockchain records who owns each item and who made it.
- Auctions and offers: Fixed price, timed auction and bidding modes fit every kind of seller.
- Many niches: Gaming, tickets, music and real assets can share one marketplace.
How It Makes Money
Minting fees: The marketplace charges users to turn an item into an NFT.
Listing fees: Some marketplaces charge a fee to list an NFT for sale.
Trading fees: Like a crypto exchange, the marketplace takes a cut of each sale.
Auction fees: Users pay to join or run NFT auctions.
Also Read: How to Build an NFT Marketplace?
5. Providing a Crypto Payment Solution for eCommerce
Overview
Crypto payment gateways help online shops accept Bitcoin, stablecoins and other coins. The shop can keep the crypto or get paid out in local money. Demand has grown as big brands moved in. A PayPal survey from January 2026 found that about 4 in 10 US merchants now accept digital assets.
Examples
BitPay, CoinPayments, Coinbase Commerce and Stripe’s stablecoin payments are well-known crypto payment options. Shopify and BigCommerce stores use several of them.
Key features
- Clear records: Every payment is easy to trace on the blockchain.
- Card on-ramp: Buyers can buy crypto with a debit card right at checkout.
- Many payment methods: Stablecoins, Bitcoin and other coins, with payouts in fiat.
- Global reach: Shops can sell to buyers in any country without card network limits.
How It Makes Money
Transaction fees: The gateway takes a small fee on each payment, often around 1%.
Crypto withdrawal fees: Merchants pay a small fee to move crypto out.
Fiat payout and card fees: Users pay to convert crypto to fiat or to top up with a card.
Merchant plans: Larger shops pay monthly for extra tools, such as invoicing and reports.
A standard gateway takes Coinsclone about 6 to 9 weeks to build, or 10 to 14 weeks with fiat settlement.
6. Developing a Trading and Investment App
Overview
Trading apps let people invest in stocks, ETFs, options, crypto and now prediction markets from a phone. AI tools help users track prices and spot trends. Robinhood shows how big this can get. It had 28.4 million funded customers and $369 billion in platform assets at the end of June 2026, with $1.31 billion in revenue for the quarter.
Examples
Robinhood, eToro and Webull are popular trading apps known for low fees and easy sign-up. Wealthfront is a well-known robo-advisor that invests for users on autopilot.
Key features
- Zero minimum: Users can sign up and start with any amount.
- AI insights: Smart alerts and research tools help users make better choices.
- Always-on support: Help and fund management are on hand at all times.
- Wide market access: One app covers stocks, crypto and other assets.
How It Makes Money
Trading fee and order flow: The app earns a small amount on each stock, option or crypto trade.
Premium plans: Paid tiers add margin, research and higher interest on cash. Robinhood has 4.8 million Gold subscribers.
Interest: The app earns interest on users’ idle cash and on margin loans. For Robinhood, this was $389 million in one quarter.
Ads and partner offers: Large apps earn from sponsored content and partner deals.
7. Launching a Digital Banking App
Overview
Digital banks, or neobanks, offer bank accounts, cards and savings fully in an app, with no branches. Most run on a licensed partner bank and focus on a better app. Chime had 10.4 million active members and made $670 million in revenue in Q2 2026. Revolut, the largest in Europe, had 68.3 million retail customers and £4.5 billion in revenue in 2025. Some digital banks now add crypto through blockchain in finance tools such as stablecoin accounts.
Examples
Chime, Revolut, Nubank and Monzo are leading digital banking apps. Users manage accounts, cards, savings and transfers in one place.
Key features
- Instant payments: Money moves between users in seconds.
- Fraud alerts: Real-time checks flag odd activity and protect funds.
- Spending insights: Built-in tools show where money goes each month.
- Fewer bank visits: Users open accounts, get cards and send P2P payments from the app.
How It Makes Money
Card fees (interchange): Each time a user pays with the card, the bank earns a small cut from the shop’s card fee. Chime made $430 million from payments in one quarter.
Paid plans: Premium tiers add perks such as travel insurance, higher limits and better FX rates.
Interest: The bank earns on deposits and on small loans, such as overdrafts.
Instant transfer and FX fees: Users pay small fees for faster transfers or for currency exchange.
8. Creating a Loan Lending App
Overview
Loan lending apps let people borrow money from a phone, often in minutes. Some lend their own funds. Others connect borrowers with lenders, as in P2P lending. Many use cash flow and bank data, not just a credit score, to decide who gets a loan. That lets them serve people that banks often turn away.
Examples
Dave, EarnIn, Upstart and SoFi are popular lending apps. Users can get small cash advances or larger personal loans with a fast, simple process.
Key features
- Fast funding: Money can reach the user in a short time, which helps in emergencies.
- Simple design: A clean app makes it easy for anyone to apply.
- Privacy: Users apply from home, without the stress of a branch visit.
- Smart tools: Loan calculators, credit models and reports help both sides decide.
How It Makes Money
Interest: The main revenue stream. Rates are often higher than at banks, to cover the risk.
Origination fees: A one-time fee on each new loan.
Subscription fees: Monthly plans unlock cash advances, credit tools or higher limits.
Express fees: Users pay a small fee to get funds instantly instead of in a few days.
9. Building a Crowdfunding App
Overview
Crowdfunding apps help founders raise money from many small backers. Some collect donations or pre-orders for products. Others sell real shares in a startup. In the US, a company can raise up to $5 million a year through Regulation Crowdfunding, and only through an SEC-registered funding portal or broker-dealer.
Examples
Kickstarter, Indiegogo, StartEngine and Wefunder are well-known crowdfunding platforms with strong track records.
Key features
- Progress meters: Founders and backers track how close a campaign is to its goal.
- Built-in payments: A payment gateway accepts many currencies and cards.
- Strong security: Large sums move through the app, so data and funds need top protection.
- Investor checks: Equity platforms verify investors and cap how much each one can put in.
How It Makes Money
Success fee: The main revenue stream. The platform takes a percentage of the funds each campaign raises.
Payment fee: A small fee on each pledge to cover card and gateway costs.
Paid plans: Founders pay for extras like CRM links, promotion and analytics.
Blockchain versions add on-chain records and token rewards for backers, as in DeFi crowdfunding platforms.
10. Insurance App
Overview
Insurance apps, or insurtech, sell and manage policies in an app. They use data, AI chatbots and connected devices to price risk and settle claims faster. A good app links policyholders and insurers with less paperwork. Many startups now sell “embedded” cover, such as travel or device cover added at checkout, instead of selling policies on their own.
Examples
Lemonade, Root and Policybazaar are well-known insurance apps. They cover home, car, health and life plans with quick quotes and claims.
Key features
- Clear home screen: Plain prices and big buttons help users buy cover in minutes.
- Policy section: Users see the type of cover, the benefits and the renewal date in one place.
- Built-in payments: Users pay premiums by card, bank or wallet.
- Fast claims: Users file claims with photos and chat with support in the app.
How It Makes Money
Premiums or commissions: Licensed insurers keep the premiums. Broker apps earn a commission on each policy sold. Prices depend on age, cover type and amount.
Partner fees: Brands pay to offer the app’s cover at their checkout.
Investing the float: Insurers invest premiums until claims are paid and keep the returns.
11. Stablecoin Cross-Border Payments
Overview
Sending money abroad through banks can take days and cost a lot. Stablecoins, which are crypto tokens pegged to the dollar, move in minutes for a few cents. More than $310 billion in stablecoins was in circulation on 1 October 2026, per DefiLlama. The US set clear rules for stablecoin issuers with the GENIUS Act, signed on 18 July 2025. Big players have moved in too: Stripe bought the stablecoin firm Bridge for $1.1 billion in 2025. This is a strong idea for remittance apps and B2B payment firms.
Examples
Bridge (Stripe), Circle’s payment network and remittance apps built on USDC and USDT show how stablecoins now power payouts, payroll and supplier payments.
Key features
- Fast settlement: Payments land in minutes, any day of the week.
- Local cash-out: Partners convert stablecoins to local money and pay out to bank accounts or mobile wallets.
- Compliance built in: KYC checks, sanctions screening and Travel Rule data on every transfer.
- Business tools: Bulk payouts, invoices and APIs for payroll and supplier payments.
How It Makes Money
Transfer fee: A flat or percentage fee on each payment.
FX spread: A small margin when converting between stablecoins and local money.
Business plans: Monthly fees for API access, bulk payouts and treasury tools.
Coinsclone’s stablecoin development services cover both the token and the payment rails around it.
12. Launching a Personal Finance App
Overview
Personal finance apps help people budget, track spending, save and plan taxes. They reach a wide audience because almost everyone wants more control over money. The market also shows why a clear revenue model matters. Intuit closed Mint, a free app with millions of users, in March 2024, and paid apps such as YNAB and Monarch Money took its users. To stand out, start small with MVP software developers and test your app with real users first.
Examples
YNAB (You Need a Budget), Monarch Money, Empower and Goodbudget have won many users with clear budgeting tools that help them plan debts and costs.
Key features
- Budgeting tool: Splits income into spending, saving and bills.
- Goals: Helps users save for a target and cut needless costs.
- Tax help: Helps users plan taxes early and pay on time.
- Support: Quick help for any app or account issue.
How It Makes Money
Subscription fee: The main revenue stream for most consumer finance apps.
Partner offers: The app earns a referral fee when users open a card, loan or savings account it suggests.
API access: The app can charge third parties to plug into its data or tools, with user consent.
13. Developing a Digital Mortgage App
Overview
Mortgage apps move home loans online, from the first quote to the final signature. They cut paperwork and give both lenders and borrowers a clear view of each step. Borrowers can compare rates, upload papers and track their loan from home.
Examples
Better is a well-known online mortgage lender that shows rates and approval steps in its app. Rocket Mortgage and loanDepot are other big names in digital home loans.
Key features
- No paperwork: Users fill in forms and upload papers from home.
- Data security: Encryption on both ends keeps personal data safe.
- Status tracking: Users see where their loan stands at any time, with no branch visits.
- Built-in compliance: Automated checks keep each loan in line with lending rules.
How It Makes Money
Origination fees: Lenders charge a fee to set up the loan, often 0.5% to 1% of the loan amount.
Discount points: Borrowers can pay points up front to lower their rate. One point costs 1% of the loan amount.
Closing costs: Fees for the application, processing, underwriting and rate lock.
Selling loans: Lenders sell loans to investors, often as mortgage-backed securities, and earn on the sale and on servicing.
Premium tools: Some apps charge for advanced tools for brokers and agents.
14. Building RegTech Apps
Overview
RegTech (regulatory technology) helps firms follow financial rules. It checks who customers are, watches transactions for fraud and money laundering, and keeps records for audits. Every new fintech needs these tools, and rules keep growing, so demand is steady. KPMG notes that investors are backing AI firms in digital identity, cybersecurity and regtech.
Examples
ComplyAdvantage, Sumsub and Onfido (now part of Entrust) are popular RegTech platforms. Chainalysis does the same job for crypto by tracing funds on the blockchain.
Key features
- Risk scoring: Rates each customer and payment so teams can focus on the risky ones.
- Fraud detection: AI spots odd patterns before money leaves.
- Anti-money laundering (AML): Screens users against sanctions and watch lists.
- KYC (Know Your Customer): Checks ID documents and selfies in seconds.
- Cybersecurity: Protects sensitive data from attacks and theft.
How It Makes Money
SaaS plans: Firms pay monthly for access to the platform and its top features.
Per-check fees: A small fee for each ID check, screening or data lookup.
Audit fee: Paid reviews that show which parts of a platform still need work.
15. Launching an RWA Tokenization Platform
Overview
RWA (real-world asset) tokenization turns things like bonds, funds, gold and property into tokens on a blockchain. Investors can buy small shares, trade at any hour and settle in minutes. About $38.55 billion in tokenized real-world assets was held by investors in early October 2026, per RWA.xyz. BlackRock’s BUIDL fund alone holds more than $2 billion in tokenized US Treasuries. For fintech startups, this opens a new kind of investment app.
Examples
BlackRock BUIDL (issued through Securitize), Franklin Templeton’s BENJI and Ondo Finance lead tokenized treasuries and funds.
Key features
- Fractional shares: Users can buy a small slice of a large asset.
- Investor checks: KYC and whitelists make sure only eligible buyers can hold the tokens.
- Built-in rules: Token standards such as ERC-3643 enforce transfer limits in the smart contract.
- Payouts on-chain: Interest, rent or dividends reach holders automatically.
How It Makes Money
Issuance fee: Asset owners pay to tokenize and launch an asset.
Management fee: A yearly fee on the value of tokenized funds.
Trading fee: A cut of each trade on the secondary market.
Also Read: RWA Tokenization Platform Development
16. Buy Now, Pay Later and Embedded Lending
Overview
Buy Now, Pay Later (BNPL) lets shoppers split a purchase into a few interest-free payments. Embedded lending goes further: a software platform, such as an online store builder, offers loans to its own users through a partner. Rules are tighter now. In the UK, BNPL has been regulated by the FCA since 15 July 2026, so lenders need approval and must check that each buyer can afford to repay.
Examples
Klarna, Affirm and Afterpay lead BNPL. Shopify Capital is a well-known example of embedded lending for online sellers.
Key features
- Instant decision: Approval at checkout in seconds.
- Affordability checks: Soft credit checks and spending limits keep users from taking on too much.
- Merchant tools: Easy plugins for online stores and point-of-sale systems.
- Payment reminders: Clear schedules and alerts help users pay on time.
How It Makes Money
Merchant fee: The main revenue stream. Shops pay a percentage of each sale, because BNPL brings in more buyers and larger orders.
Interest on longer plans: Loans over longer terms carry interest.
Card and app fees: Some providers earn card fees and ad revenue from shopping apps.
Which Fintech Business Ideas Earn the Most in 2026?
Payments still attract the most money. Out of the $103.1 billion invested in fintech in the first half of 2026, $44.2 billion went to payments firms, per KPMG. AI-focused fintechs drew $21.4 billion and digital assets $11.1 billion. That points to payments, stablecoins, AI tools and crypto platforms as the strongest bets.
Revenue tells the same story. Public fintech apps rarely live on one fee. Instead, they stack several streams, as the chart below shows. A trading app earns on trades, but close to 30% of its money comes from interest on cash. A digital bank earns mostly from card fees, then adds paid plans and loans.
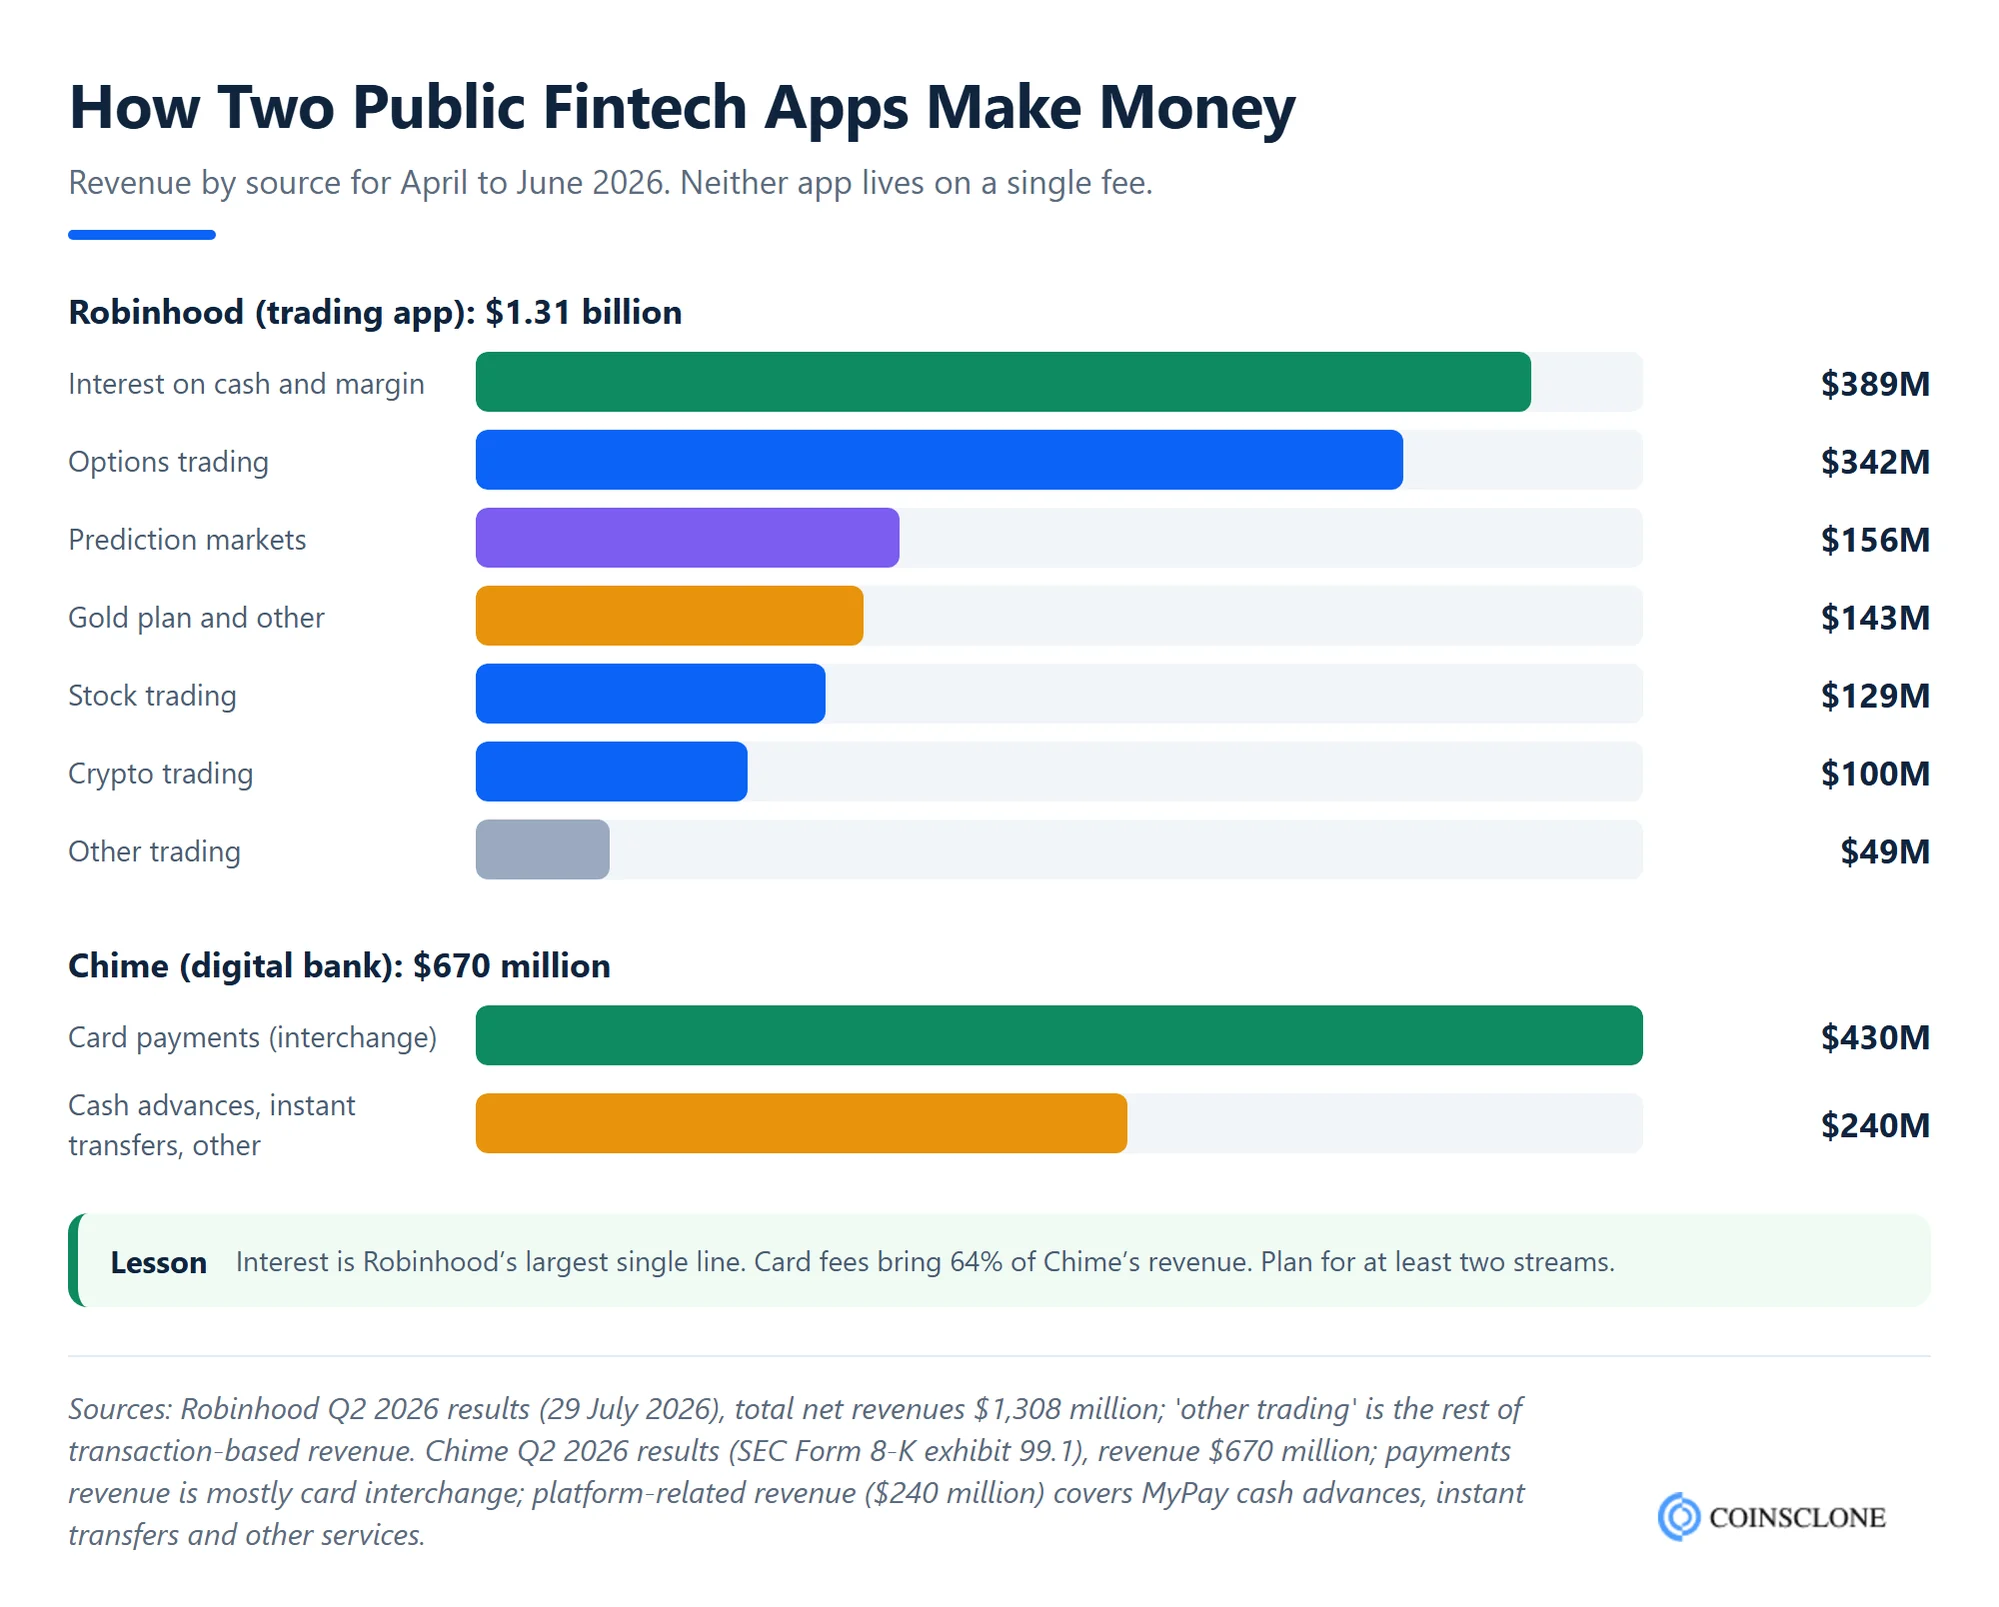
The lesson for a startup: plan for at least two revenue streams from day one. A fee on each transaction brings early revenue, and a paid plan or interest income adds steady money later.
Fintech Business Ideas Compared
Use this table to see each idea’s main revenue stream and how heavy its rules are. “Rule load” is a rough guide. It shows how much licensing and compliance work you should expect before launch.
| Fintech business idea | Main way it earns | Licence or partner usually needed | Rule load |
| Crypto exchange | Trade and withdrawal fees | Crypto licence (MiCA CASP in the EU, MSB and state licences in the US) | High |
| DeFi app | Swap and protocol fees | Often none for code; front ends may need one | Medium |
| Digital wallet | Payment, swap and merchant fees | E-money or money transmitter licence if you hold funds | Medium |
| NFT marketplace | Trading and minting fees | Usually none for unique NFTs | Low |
| Crypto payment gateway | Transaction and payout fees | Payment or crypto licence, or a licensed partner | Medium |
| Trading and investment app | Trades, interest, paid plans | Broker-dealer licence or a partner broker | High |
| Digital banking app | Card fees, interest, plans | Partner bank, or e-money licence | High |
| Loan lending app | Interest and origination fees | Lending licence per state or country | High |
| Crowdfunding app | Success fee on funds raised | Funding portal registration for equity raises | Medium |
| Insurance app | Premiums or commissions | Insurer or broker licence, or a partner insurer | High |
| Stablecoin cross-border payments | Transfer fee and FX spread | Money transmitter or payment licence, plus payout partners | High |
| Personal finance app | Subscriptions and referrals | Usually none if it does not move money | Low |
| Digital mortgage app | Origination fees and loan sales | Mortgage lender or broker licence | High |
| RegTech app | SaaS plans and per-check fees | None; you sell to licensed firms | Low |
| RWA tokenization platform | Issuance and management fees | Securities rules for most assets | High |
| BNPL and embedded lending | Merchant fees | Consumer credit licence (FCA in the UK since July 2026) | High |
If you want a quick start with low rules, look at RegTech, personal finance or an NFT niche. If you can handle licensing or work with a partner, payments, digital banking and stablecoins have the biggest upside.
How to Choose and Validate a Fintech Idea
A good fintech idea solves one painful money job for one clear group of users. Before you write any code, test it with these steps.
- Pick one user and one job. For example, “freelancers in the UK who wait 60 days to get paid” is better than “small businesses”.
- Check who already pays for the problem. If people spend time or money on it today, they will likely pay you to fix it.
- Map the rules first. Find out early whether you need a licence, a partner bank or neither. This one step can save months.
- Talk to 20 to 30 users. Ask how they solve the problem now, and what it costs them.
- Ask for a commitment. A paid pre-order, deposit or signed letter of intent is far stronger proof than a survey.
- Build an MVP around one money flow. Launch one core feature, such as “send money” or “buy a token”, and grow from there.
Most fintech ideas fail because nobody needed them, not because the tech broke. Testing first is the cheapest way to avoid that.
Licences and Rules to Check Before You Launch
Rules are the biggest difference between fintech and normal apps. The question that decides most of it is simple: will you hold or move other people’s money? Follow the tree below to see which path your idea fits.
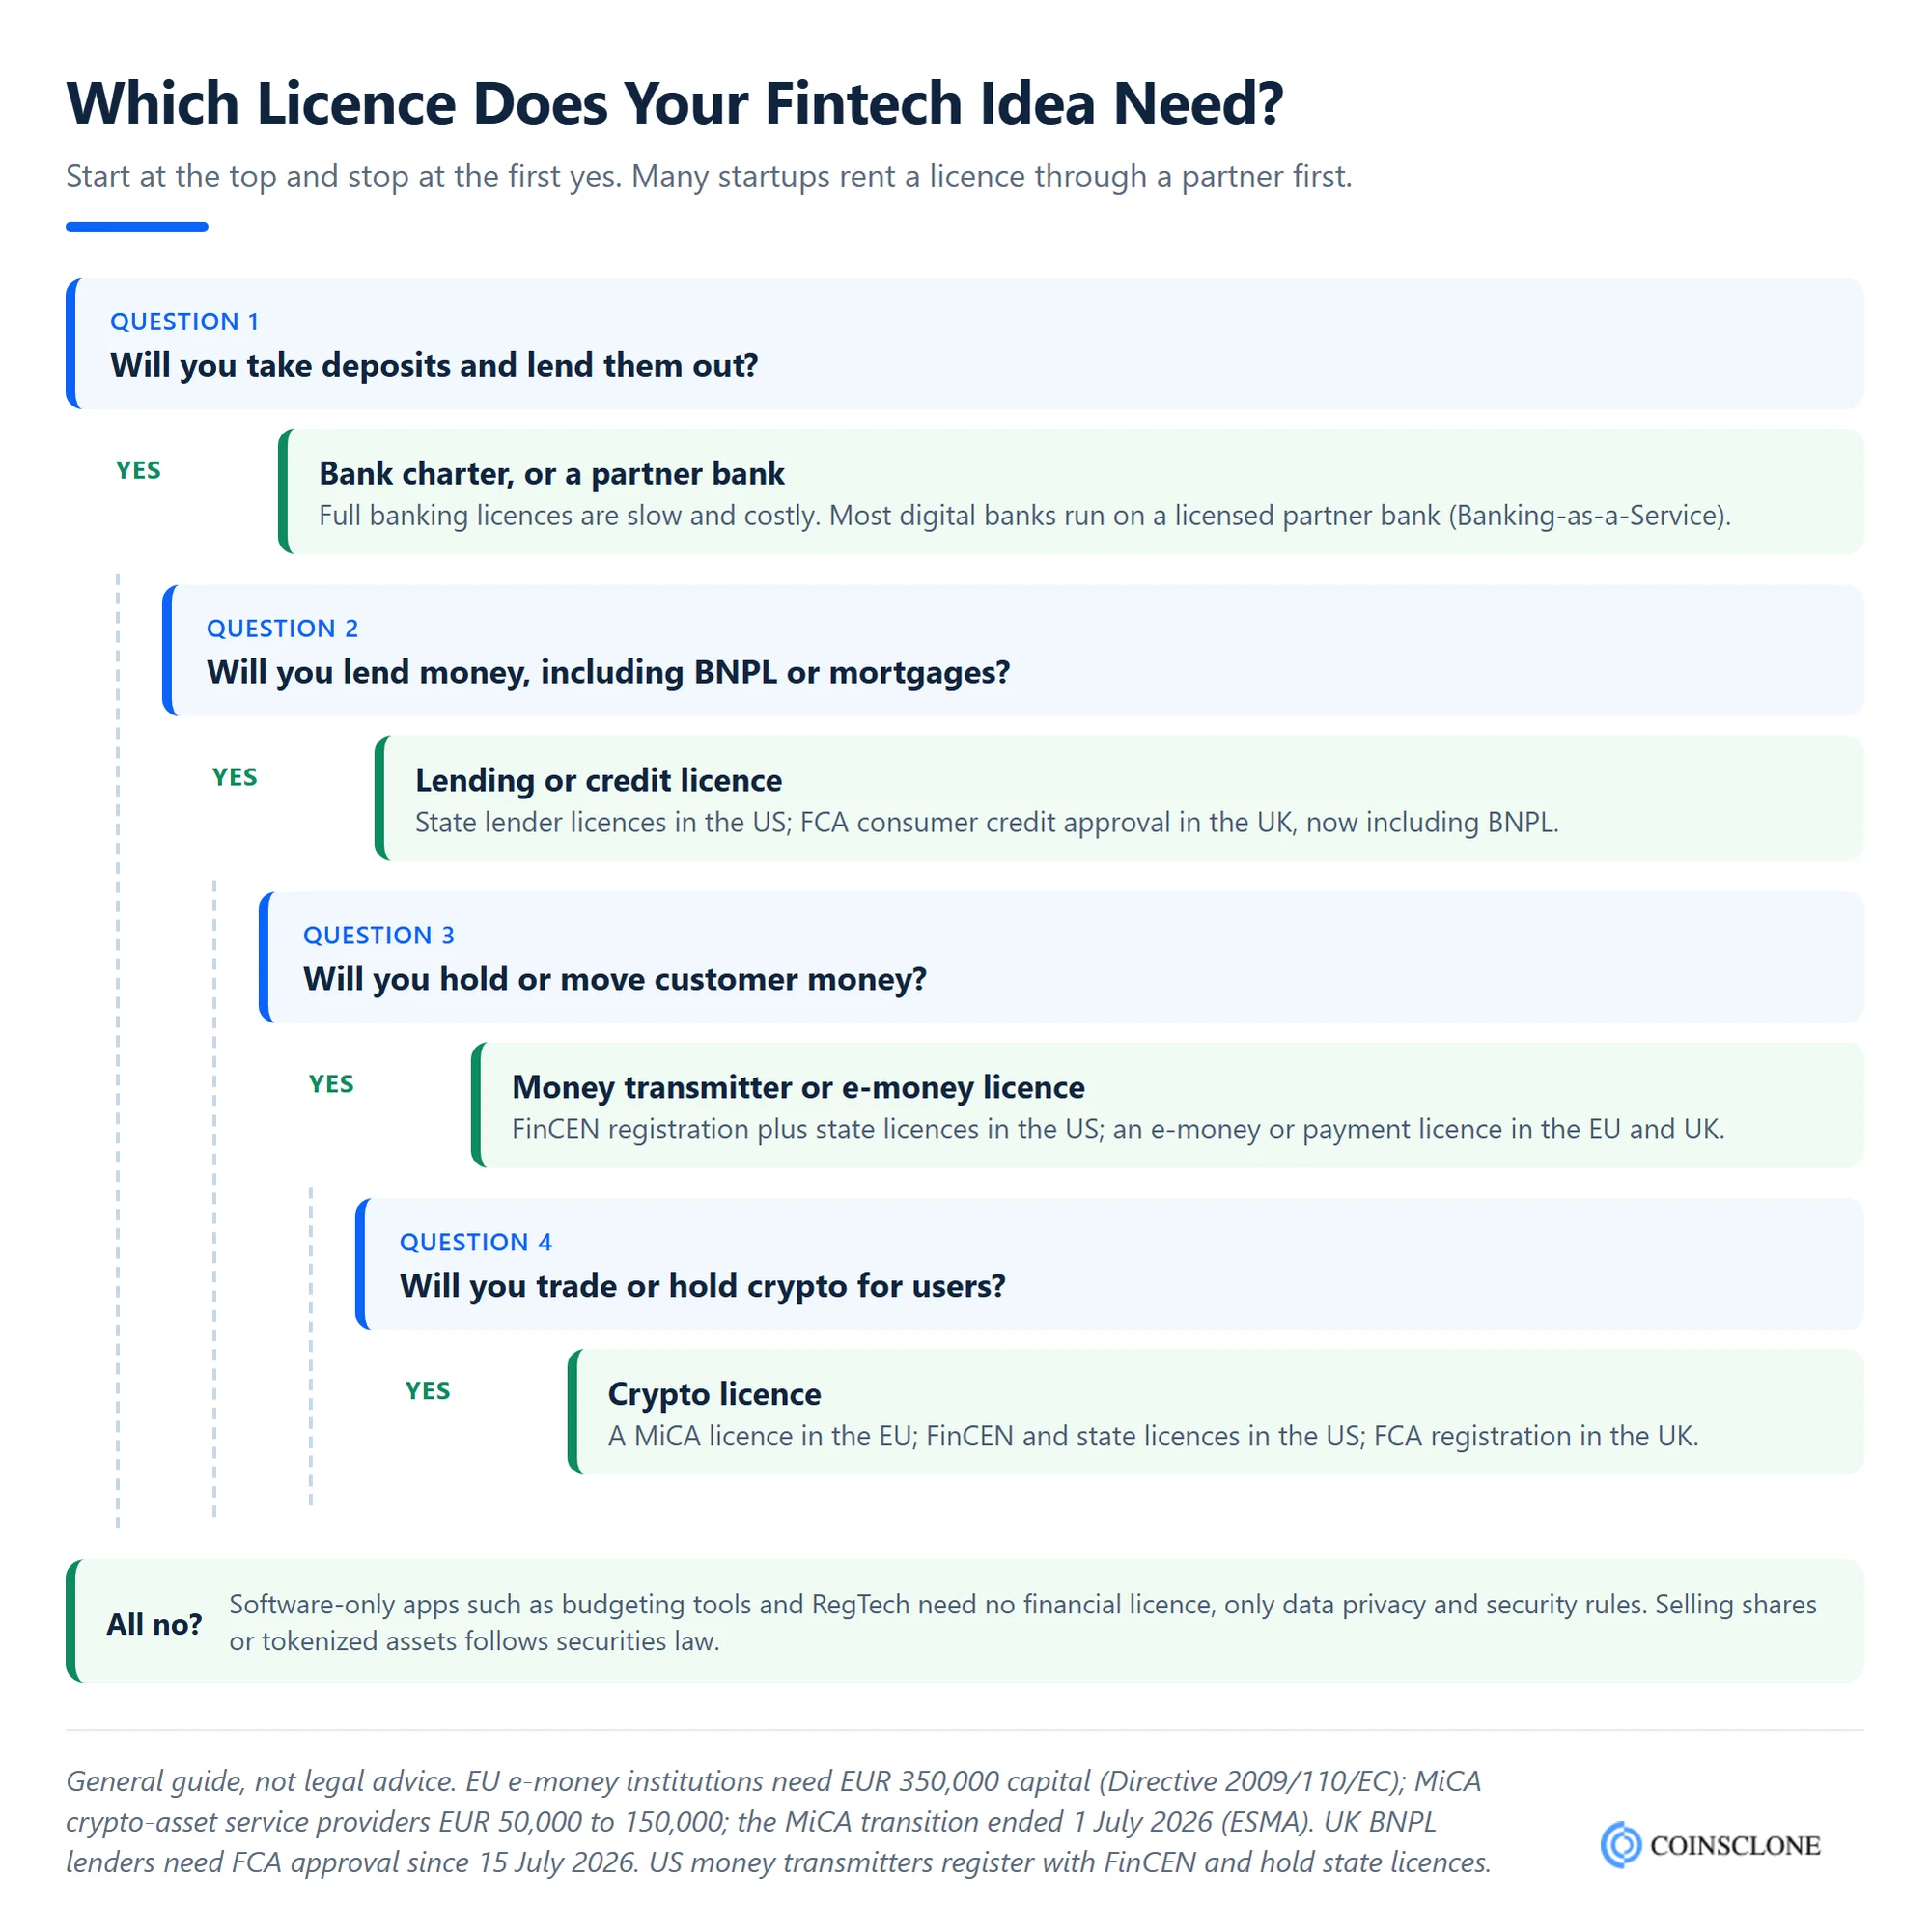
Here are the main rules by region:
- United States: Firms that move money register with FinCEN as a money services business and usually need a money transmitter licence in each state. Many startups use a partner bank (Banking-as-a-Service) instead of getting a bank charter. Stablecoin issuers now follow the GENIUS Act.
- European Union: Payment and e-money firms need a licence under the payment rules. An e-money institution needs at least €350,000 in capital. Crypto firms need a MiCA licence as a crypto-asset service provider, and the transition period ended on 1 July 2026.
- United Kingdom: The FCA licenses payment, e-money, lending and crypto firms. BNPL lenders need FCA approval since 15 July 2026.
- Everywhere: KYC (Know Your Customer), AML (anti-money laundering) checks and data privacy rules apply to almost every fintech that handles money.
Rules change often, so speak to a fintech lawyer in your target market before you build.
How Much Does It Cost to Build a Fintech App?
Costs depend on the idea, the features and the rules you must meet. Published 2026 agency cost guides give these rough ranges:
- Simple fintech MVP: $40,000 to $150,000, built on existing payment and banking partners.
- Compliance layer: $10,000 to $40,000 more for KYC, AML and reporting tools.
- Full digital bank: $300,000 to $500,000 or more, before licence costs.
- Time: About 10 to 14 weeks for a focused MVP, longer with custom AI or new infrastructure.
Crypto ideas can launch faster with ready-made software. Coinsclone’s published timelines are 4 to 6 weeks for a white label crypto exchange, 3 to 5 weeks for a white label wallet, 5 to 7 weeks for a white label DEX and 6 to 9 weeks for a standard payment gateway.
How to Build Your Own Fintech
Building a fintech startup is exciting, but it takes careful planning. Here is a short path from idea to launch:
- Set your goals and target users. Know exactly who you serve and what problem you solve.
- Check the rules. Confirm the licences, partners and compliance steps your idea needs.
- Study your rivals. Find what they do poorly and make that your USP (unique selling point).
- List the risks. Note the tech and business challenges ahead, and plan how to handle each one.
- Raise funds. Use savings, angels, VCs or crowdfunding to cover the build and the first year.
- Hire a skilled team. Fintech developers who know payments, security and the right tech stack save time and money.
- Launch an MVP. Start with a Minimum Viable Product, which is the cheapest way to test the market.
- Learn and improve. Gather user feedback after launch and fix weak spots fast.
Bringing a working fintech product to life takes deep tech skill, too. That is where a seasoned fintech software company like Coinsclone helps.
Envision Your Fintech Business Ideas with Coinsclone!
Coinsclone is a fintech software development company that has built crypto and blockchain products since 2018. We have delivered 350+ platforms for 200+ clients across 20 industries, from crypto exchanges and wallets to payment gateways, DeFi apps and RWA tokenization platforms. Share your idea with us, and our team will help you turn it into a secure, market-ready product.
Fintech joins finance and technology in a way that keeps creating new businesses. Demand will stay strong in the years ahead, and the right idea, built well, can grow fast.
Innovate Your Financial Services with Smart Fintech Solutions
Innovative, Scalable, and Market-Ready Ideas to Propel Your Business.
Frequently Asked Questions
Which fintech business idea is the most profitable?
Payments and digital banking earn the most at scale, because they collect a small fee on a huge number of transactions. In the first half of 2026, payments drew $44.2 billion of the $103.1 billion invested in fintech, per KPMG. For a startup, the most profitable idea is the one that serves a clear user group and stacks two or more revenue streams.
How much does it cost to develop a fintech app?
A focused fintech MVP usually costs $40,000 to $150,000, based on published 2026 agency cost guides. Compliance tools add about $10,000 to $40,000. A full digital bank can cost $300,000 to $500,000 or more, before licence costs.
What are the steps to validate a fintech app idea?
Pick one user group and one money problem. Check who already pays to solve it, and map the rules early. Then talk to 20 to 30 target users, ask for a pre-payment or letter of intent, and build an MVP around one core money flow.
What are the legal and regulatory considerations for fintech startups?
Most fintech startups need a licence, registration or a licensed partner before they handle money. You will also need KYC (Know Your Customer) and AML (anti-money laundering) checks. In the US, firms that move money register with FinCEN and get state licences. In the EU, payment firms need an e-money or payment licence, and crypto firms need a MiCA licence.
How long does it take to launch a fintech MVP?
A focused fintech MVP takes about 10 to 14 weeks to build. Licensing can add months, so map the rules at the start. Crypto products launch faster on white label software. For example, Coinsclone delivers a white label crypto exchange in 4 to 6 weeks.
What are the major features of fintech apps?
Most fintech apps need simple screens, strong security, KYC checks, data and spending insights, QR payments, chat support or AI assistants, alerts, budgeting tools and links to banks or other third-party services.
How do fintech apps make money?
Fintech apps earn through transaction fees, card fees, subscriptions, interest and service fees. The best apps combine several. Robinhood, for example, earns from trades, from interest on cash and from its Gold plan.
Related articles