RWA tokenization in Hong Kong has moved from pilots to live markets. In 2026 the city gave out its first stablecoin licences. It let the public trade fund tokens on licensed crypto platforms. It also sold the largest digital bond in the world. If you plan to put bonds, funds, gold or property on chain for buyers in Asia, Hong Kong is now one of the first places to look.
This guide shows how the Hong Kong market works as of October 2026. You will see which rules apply, which licence your project needs, what the government and banks have launched, and how a firm can get in. Each status claim has a date, so you can see how fresh it is.
In this guide:
- The rules that apply: the SFC token circulars, the April 2026 trading rules and the stablecoin law.
- A simple decision tree for which Hong Kong licence fits your token.
- Real market data: fund token assets, green bond sizes and the first stablecoin licences.
- The asset types, revenue models and risks to plan for.
- A step-by-step path to launch an RWA platform in Hong Kong.
See How Our MVP System Can Launch Your RWA Platform Faster
RWA Tokenization in Hong Kong — done right.
- MVP System:Launch your real-world asset tokenization platform up to 90% faster.
- Asset Tokenization Modules: Pre-built solutions for real estate, funds, commodities, and more — no heavy coding required.
- Compliance-Ready Framework:Built with Hong Kong’s regulatory landscape in mind for smoother approvals.
- Brand & Customization: Your platform, your assets, your investor experience.
- Revenue Engine: Earn through issuance fees, trading, asset management, and fractional ownership models.
See a free branded demo of your RWA platform in 48 hours — before you invest a cent.
Book a Free Demo to discover how our RWA tokenization solution can take you from concept to live platform in just 2–4 weeks.
RWA Tokenization in Hong Kong: How It Became a Real Market
RWA tokenization turns a real asset, such as a bond, a fund share, gold or a building, into a token on a blockchain. The token records who owns it. It can be split into small units and can settle in minutes instead of days.
Hong Kong has become a hub for this for three reasons. It has a deep finance market. Its two main watchdogs have written clear rules. And the government issues token bonds itself. Worldwide, real-world asset tokens on public chains reached $38.55 billion on 2 October 2026, not counting stablecoins, per the rwa.xyz dashboard. Hong Kong is a growing share of that market.
Notable projects and milestones
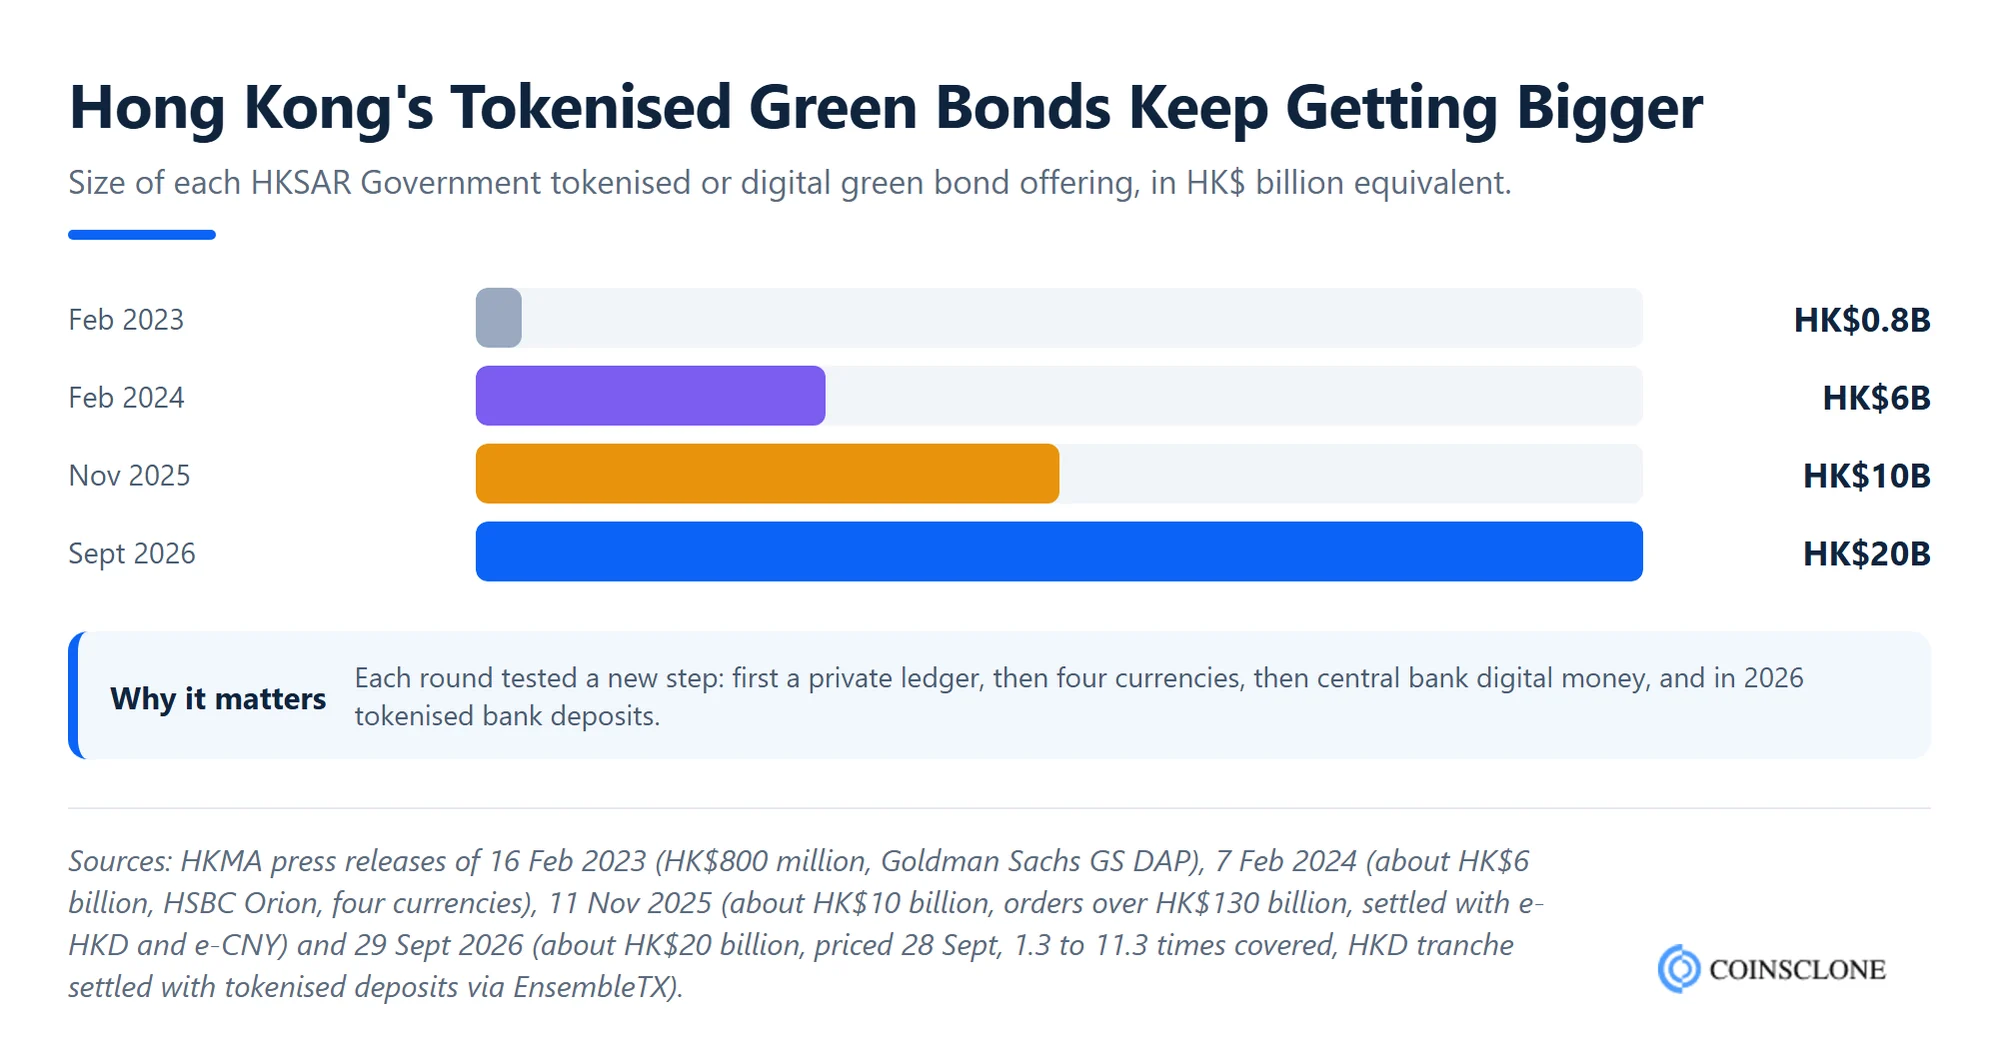
February 2023: The Hong Kong government sold HK$800 million of tokenised green bonds, one of the first by any government. The bonds ran on Goldman Sachs’ GS DAP token platform. The next round, HK$6 billion in February 2024, used HSBC Orion.
November 2023: The Securities and Futures Commission (SFC) published two token circulars. One is for firms that deal in security tokens. The other is for tokenised SFC-approved funds.
March 2024: The Hong Kong Monetary Authority (HKMA) launched Project Ensemble to test how banks can settle asset tokens with deposit tokens. HSBC also launched the HSBC Gold Token. HSBC calls it the first SFC-approved retail product in Hong Kong built on a blockchain ledger.
June 2025: The government issued its Policy Statement 2.0 on digital assets, with a plan called “LEAP” to grow token products.
August 2025: The Stablecoins Ordinance came into force.
April 2026: The HKMA granted the first two stablecoin licences. The SFC let the public trade fund tokens on licensed platforms.
September 2026: The government priced about HK$20 billion of digital green bonds. The HKMA calls it the largest digital bond issue in the world.
Key factors behind Hong Kong’s success
1) Clear rules from the SFC: A token keeps the legal status of the asset it wraps. So issuers know which rules apply from day one.
2) The government leads by example: It has sold four rounds of digital green bonds and plans to make digital bonds a routine part of its funding.
3) Banks and crypto firms work together: Banks, fund firms and licensed crypto platforms test real deals side by side in HKMA and SFC programmes.
Regulatory Framework for RWA Tokenization in Hong Kong
Hong Kong does not have one “token law”. Instead, two watchdogs share the work. The SFC covers shares, bonds, funds and crypto trading platforms. The HKMA covers banks, deposit tokens and stablecoins. The basic rule is “same activity, same risks, same rules”. In short, a token follows the rules of the asset behind it.
There are five main points of guidance
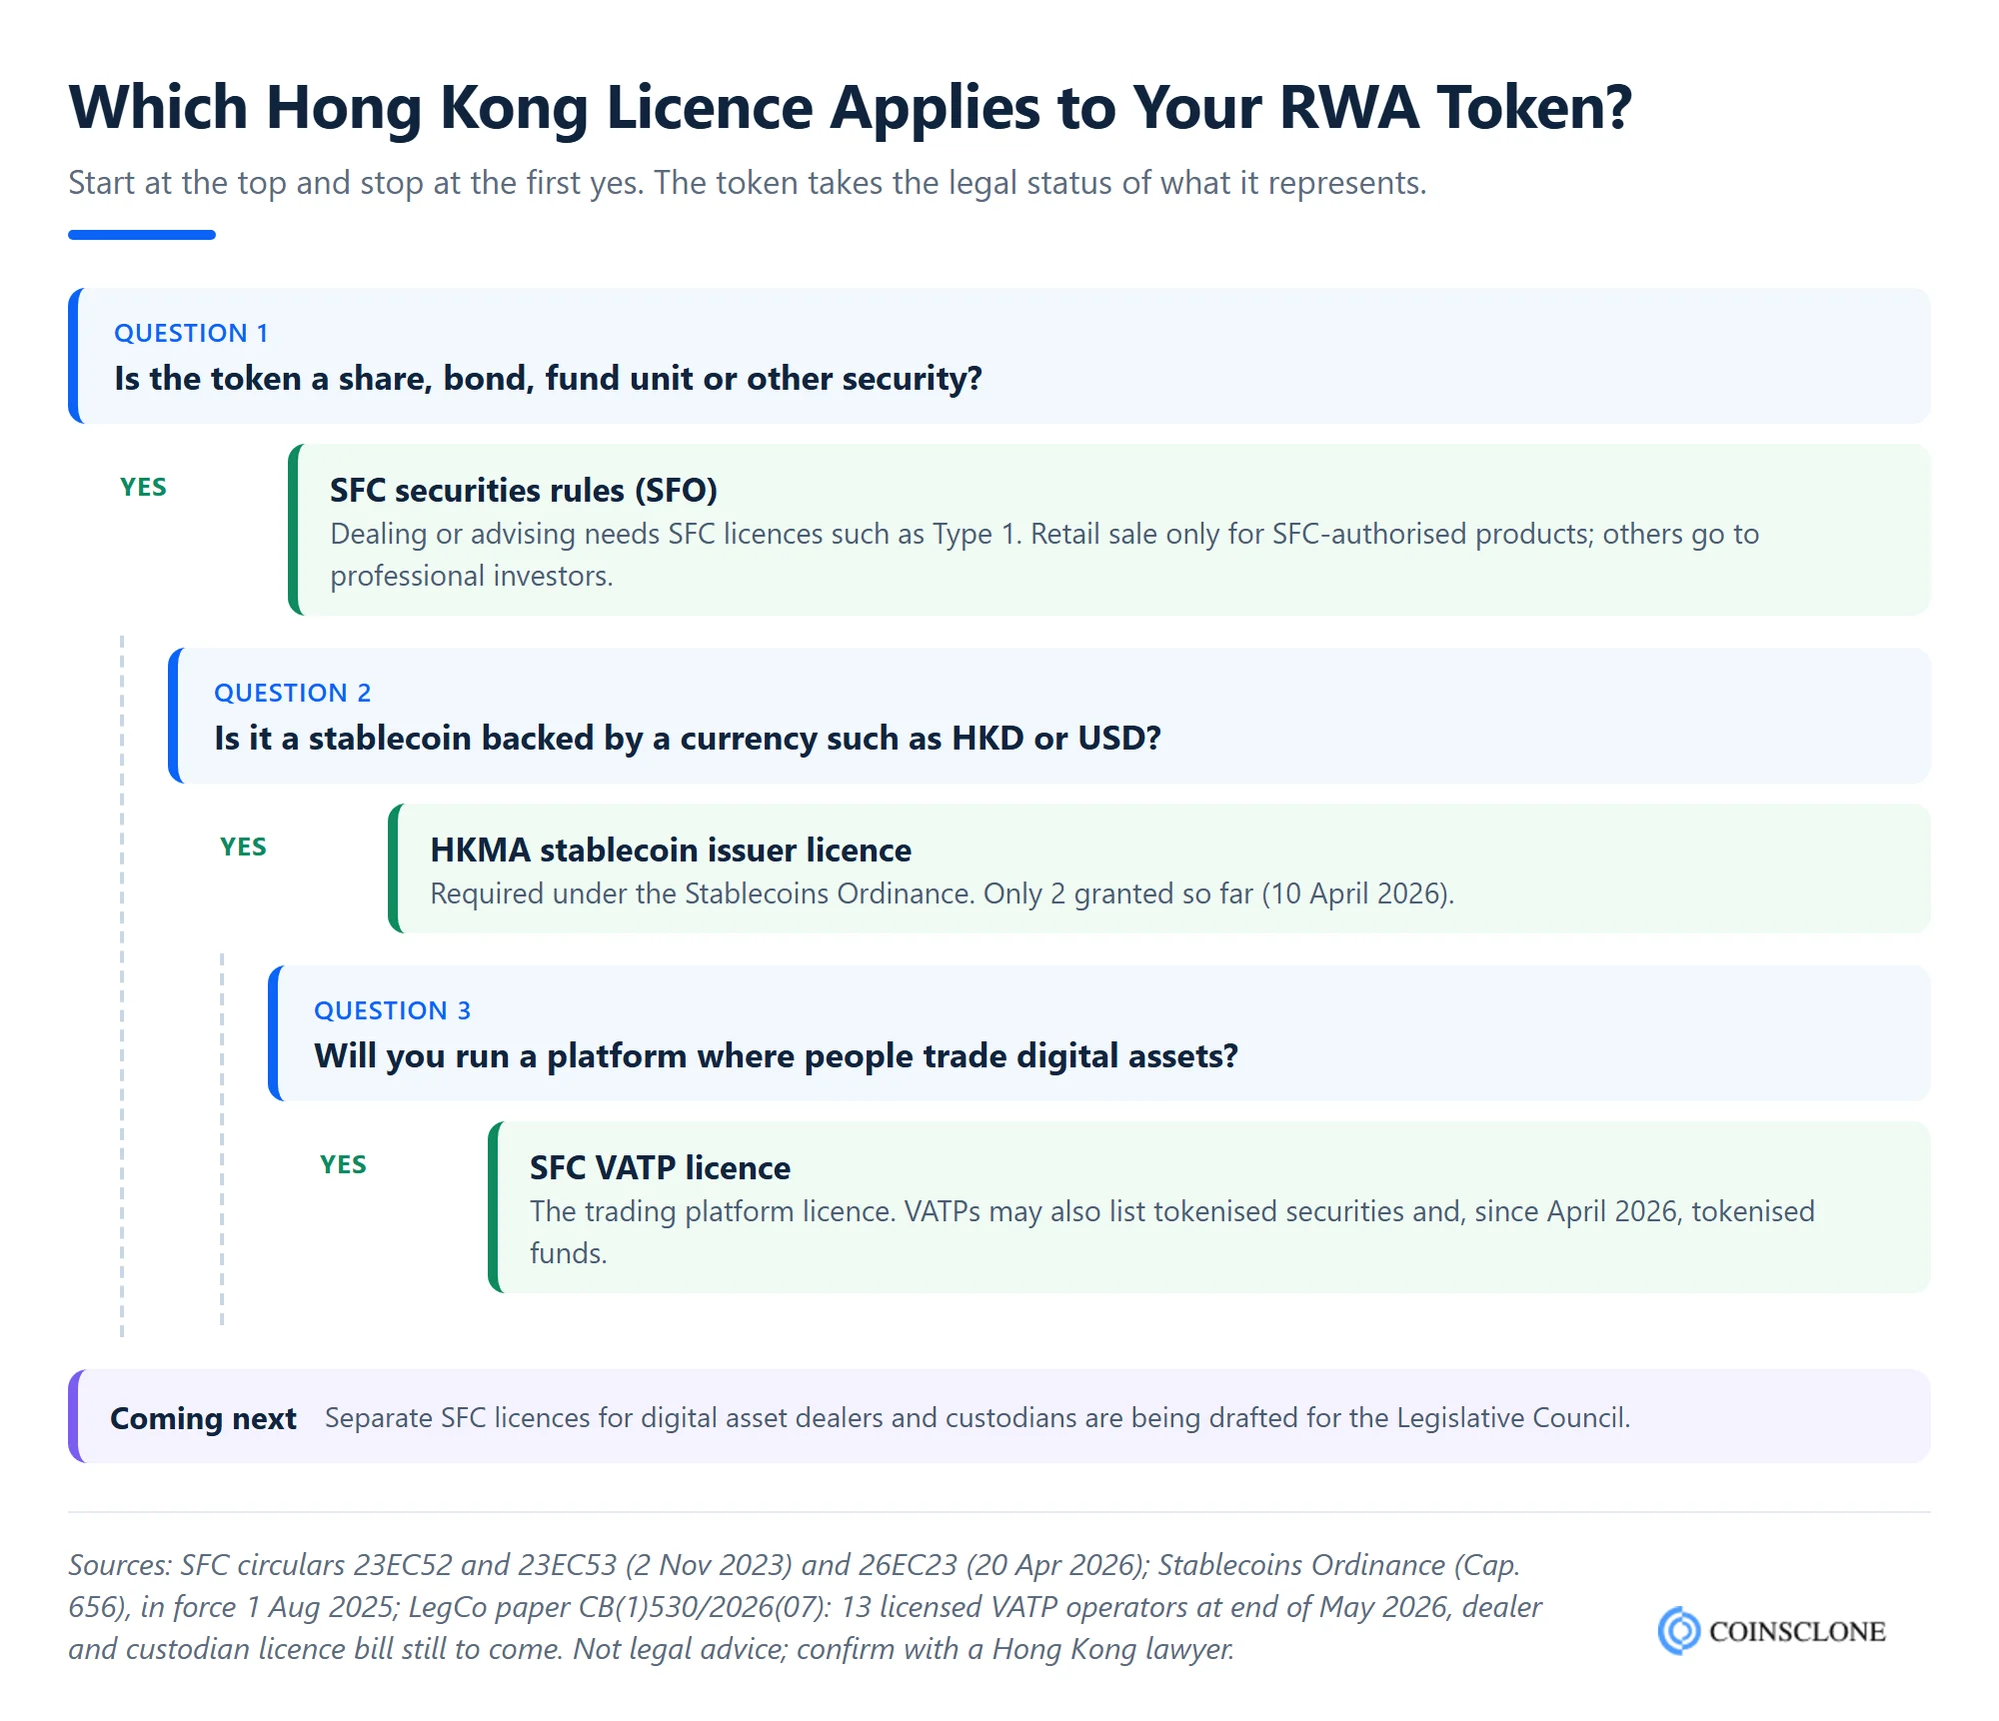
- Security tokens are still securities: The SFC’s November 2023 circular on tokenised securities calls them normal securities in a token wrapper. The Securities and Futures Ordinance (SFO) applies as usual, with its rules on offers, disclosure and trading.
- Licences follow the activity: Firms that deal in, advise on, manage or hold security tokens need the matching SFC licence, such as Type 1 for dealing. Platforms that trade crypto tokens need a virtual asset trading platform (VATP) licence. At the end of May 2026, the SFC had licensed 13 VATP operators.
- Fund tokens need SFC approval for retail sale: A fund can add a token share class. But the fund manager stays in charge of the token setup, custody and smart contract risks, even when a tech vendor runs part of it.
- Trading after launch is now allowed: Since 20 April 2026, retail buyers can trade tokens of SFC-approved funds on licensed VATPs. Platforms must warn buyers when a price strays from the fund’s value. They must post that value at least every 15 seconds and line up at least one market maker per product.
- Stablecoins need an HKMA licence: The Stablecoins Ordinance (Cap. 656) has been in force since 1 August 2025. Anyone who issues a fiat-backed stablecoin in Hong Kong, or a Hong Kong dollar stablecoin anywhere, needs an HKMA licence.
The LEAP plan and what is still coming
The June 2025 Policy Statement 2.0 set four goals under the name LEAP. They are Legal and rule streamlining, Expanding token products, Advancing use cases and People and partners. Under it, the government said it would issue token bonds as a routine. It also said it would back gold, metal and green energy tokens, and make clear the stamp duty on ETF tokens.
Two parts of the plan were still in progress in October 2026:
- Dealer and custodian licences: The government and SFC asked the market for views from June to August 2025 and published their response on 24 December 2025. As of the 2026 Policy Address in September, the bill was not yet law. So firms that only deal in or hold digital assets do not yet have their own licence.
- More token products: The 2026 Policy Address (16 September 2026) says the SFC will widen its rules. The aim is to let gold tokens and other suitable real-world assets be issued and traded on licensed platforms.
Types of Real-World Assets Being Tokenized in Hong Kong
Hong Kong’s token market is led by bonds and funds, not by property or art. That is because these assets fit the SFC’s rules. The main asset types are:
- Bonds: This is the busiest segment. Per the 2026 Policy Address, digital bonds issued in Hong Kong took nearly 50% of the world market from 2025 to the first half of 2026. Issuers include the government, public bodies and banks.
- Money market funds: Fund firms offer token share classes that hold short-term cash and government debt. They are the first funds allowed to trade on licensed crypto platforms. Our guide to tokenized treasuries explains how these products work.
- Gold and precious metals: HSBC’s Gold Token lets bank customers own gold in units of 0.001 troy ounce through the bank’s app. The LEAP plan names metals as a goal, which makes gold tokenization a strong use case.
- Real estate: Tokenization of real estate lets many buyers share one building. In Hong Kong, most property tokens count as securities or pooled funds. So offers often go to professional investors first.
- Private credit, equity and venture capital: Splitting stakes in private firms or loans opens them to more buyers. These are most often sold only to professional investors.
- Green and carbon assets: HKEX is building a blockchain platform for many asset types. It now holds carbon credits from its Core Climate market, and warehouse receipts for goods will follow in a 2027 pilot.
As these asset types grow, the Hong Kong market gets easier to reach and more open for buyers.
Impact of Tokenization on Hong Kong’s Financial Ecosystem
Tokens are changing how money and assets move in Hong Kong, for banks and for everyday buyers.
The major benefits of tokenizing assets in Hong Kong are:
More liquidity: Small units and round-the-clock trading give hard-to-sell assets more buyers. Since April 2026, fund tokens can trade on licensed platforms. Before, they could only be bought from and sold back to the fund manager.
Faster settlement: Asset tokens and cash tokens can swap in one step. In September 2026, the HKD part of the government’s green bond settled with deposit tokens through the HKMA’s EnsembleTX pilot. The HKMA calls this a world first.
More transparency: Each transfer is recorded on chain. Owners can prove what they hold and see each asset’s full history.
Wider access for retail buyers: Small token units let people buy into gold, funds and bonds that once needed large sums.
Global pull: Clear rules draw global banks and fund firms. Banks and fund managers from around the world now test live deals in the HKMA’s EnsembleTX pilot, which runs through 2026.
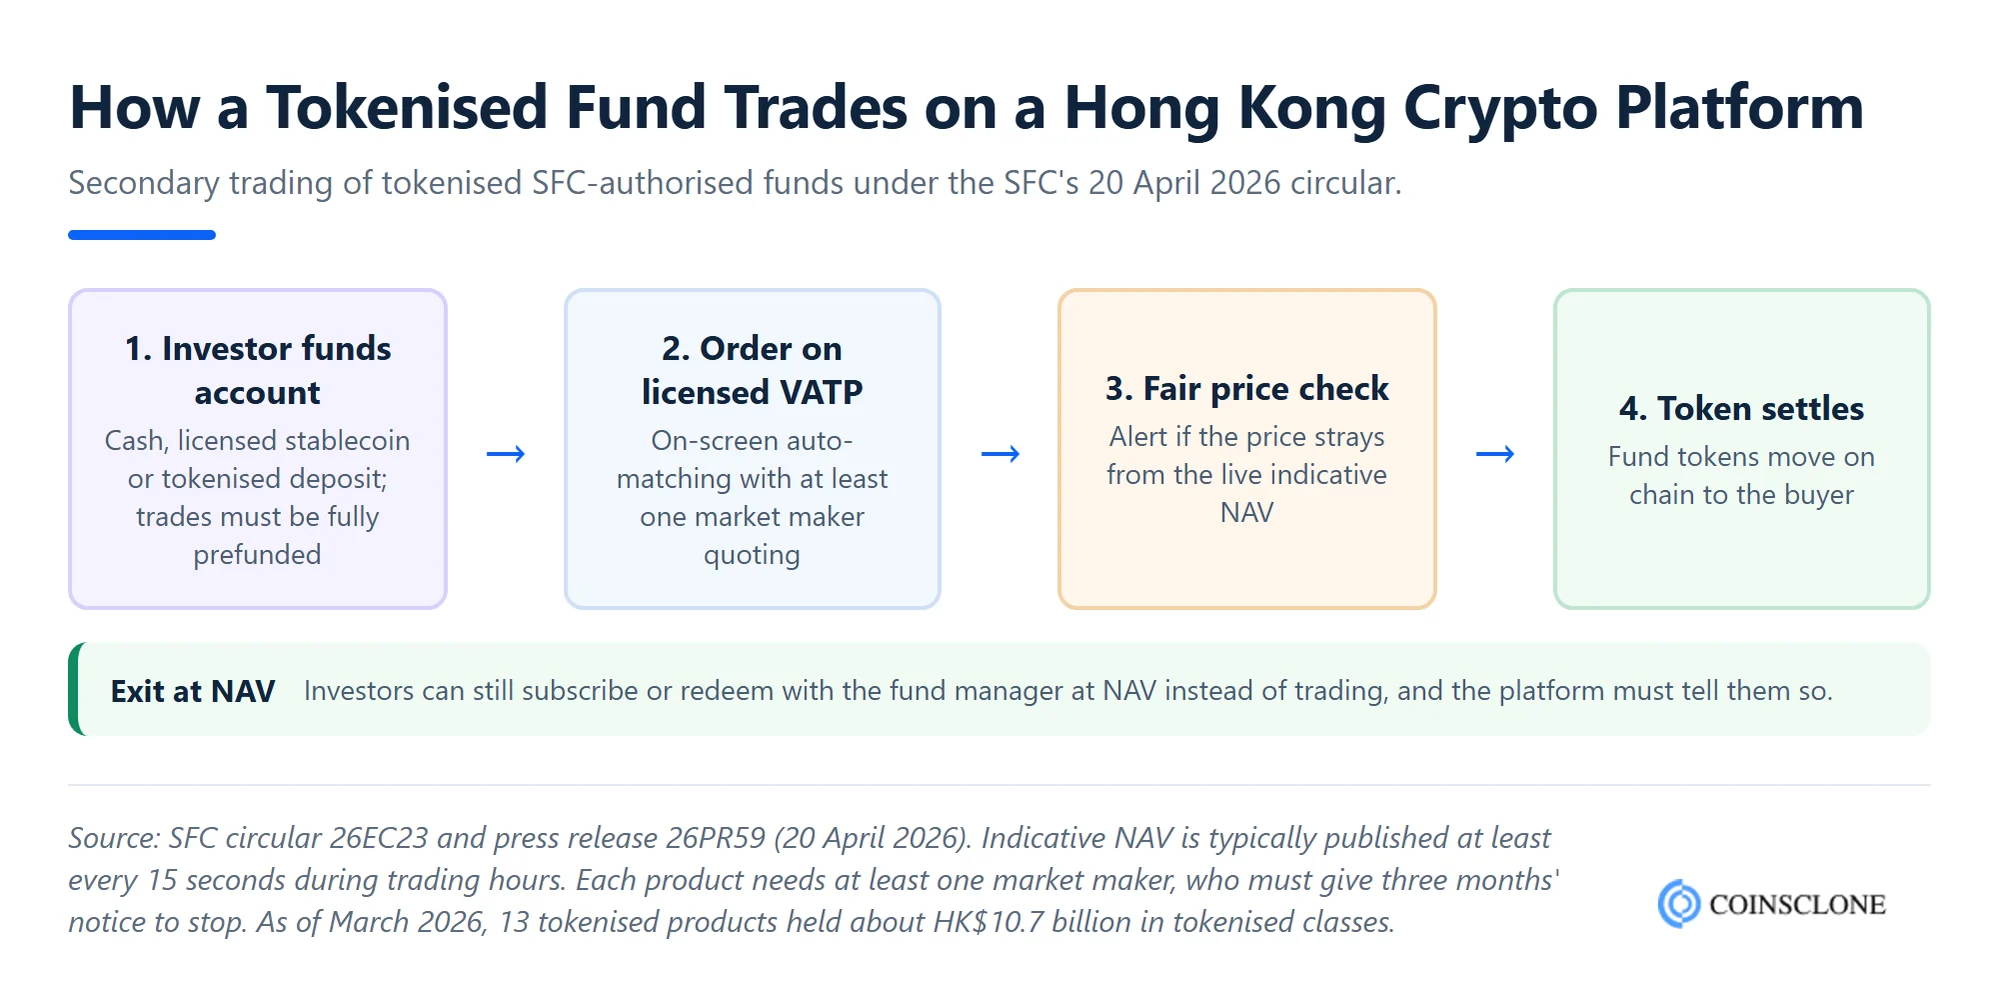
So tokens are not only a tech trend in Hong Kong. They are changing how the city’s markets settle trades, raise money and reach buyers.
Market Growth of RWA Tokenization in Hong Kong
Hong Kong publishes more hard numbers on tokens than most markets. Here is where things stand, with the date and source for each figure.
| Metric | Figure | Date | Source |
| Tokenised SFC-approved products sold to the public | 13 products | March 2026 | SFC |
| Assets in those token share classes | About HK$10.7 billion, up about 7 times in a year | March 2026 | SFC |
| Licensed crypto trading platforms (VATPs) | 13 operators | End of May 2026 | LegCo paper |
| Licensed stablecoin issuers | 2 (Anchorpoint Financial, HSBC) out of 36 applicants | 10 April 2026 | HKMA |
| Largest government digital green bond | About HK$20 billion in 4 currencies | 28 September 2026 | HKMA |
| Hong Kong share of world digital bond issues | Nearly 50% | 2025 to H1 2026 | 2026 Policy Address |
The trend is clear. Fund token assets grew about sevenfold in a year, and each government digital bond has been larger than the one before.
What comes next in 2026 and 2027
The 2026 Policy Address lists a few dated plans. The HKMA will test token versions of Exchange Fund Bills by the end of 2026. That would let banks use more than HK$1.3 trillion of these bills around the clock. CMU OmniClear will set up a digital asset platform this year to issue and settle digital bonds. The HKMA also plans to settle EnsembleTX in central bank money and run it 24/7 by around the end of 2026.
Revenue Models of RWA Tokenization in Hong Kong
As the market grows, platforms and service firms earn money in many ways. Most of it comes from the services they run to issue, manage and trade tokens.
Transaction Fees: Platforms charge a small fee each time a buyer buys, sells or moves a token. Licensed VATPs also earn trading fees on fund tokens now that trading after launch is allowed.
Management Fees: When tokens stand for a pooled asset, such as a fund or a shared property, the operator charges an ongoing fee to run it.
Issue and Listing Fees: Asset owners pay to set up, tokenize and list their assets. This covers legal work, smart contracts, buyer checks and onboarding.
Market Making: The April 2026 rules require market makers for fund tokens on VATPs. Firms that provide this depth earn the gap between buy and sell prices.
Paid Tools: Platforms can charge a monthly fee for data, portfolio tracking, reports and other tools.
Settlement and Custody Services: Banks and licensed custodians earn fees to hold tokens and to settle trades in stablecoins or deposit tokens.
Challenges in RWA Tokenization in Hong Kong
The market is growing fast, but projects still face real hurdles. Plan for these before you build.
- Complex rules: Rules sit across the SFC, the HKMA and anti-money laundering law. Separate dealer and custodian licences are still being written, so some business models must wait for new law.
- Limited retail access: Outside SFC-approved products, most security tokens can only be sold to professional investors. In Hong Kong, a person needs a portfolio of at least HK$8 million to qualify.
- Thin trading: Many tokens trade thinly at launch. That is why the SFC now requires market makers for fund tokens on VATPs.
- Mainland caution: In September 2025, Reuters reported that China’s securities watchdog had told some mainland brokers, off the record, to pause RWA work in Hong Kong. Projects with mainland backers should check their own position.
- Tech risks: Smart contract bugs, key theft and bad price feeds can all damage trust in a token. Audits and strong custody are a must.
How Businesses Can Successfully Enter Hong Kong’s RWA Ecosystem?
Do Market Research: Start by checking which assets Hong Kong buyers want and which are on chain now. Bonds, money market funds and gold have the clearest demand and the clearest rules today.
Know the Rules: Decide early whether your token is a security, a fund unit, a stablecoin or some other digital asset. That decides your licence, your buyers and your platform. Get advice from a Hong Kong lawyer before you build.
Build the Right Tech: Choose a secure blockchain that can scale, and a partner who has built token platforms before. Your platform needs buyer checks (KYC), transfer limits for eligible buyers, audit trails and links to licensed custodians.
Choose Licensed Partners: You do not always need your own licence. A tech firm can run the platform while a licensed bank, broker or VATP handles the regulated parts, such as dealing and sales. That licensed firm stays answerable to the SFC.
Plan Your Buyer Strategy: Explain clearly what the token gives buyers, how they can sell it and what fees apply. Most projects start with professional investors. They reach retail buyers only through SFC-approved products.
Build Partnerships: Work with banks, fund firms, custodians and licensed platforms. Schemes such as the SFC’s Digital Asset Accelerator and the HKMA’s EnsembleTX pilot help firms meet these players.
Coinsclone builds asset tokenization platforms with buyer checks, transfer limits and custody links built in. That way your platform fits Hong Kong’s licence model from the start.
Comparative Analysis: Hong Kong vs Other RWA Hubs
Hong Kong is one of a few strong RWA hubs. The table below compares the rules that matter most for issuers. For a wider view by country, see our guide to the top countries to launch RWA tokenization.
| Feature | Hong Kong | Singapore | Switzerland | US | EU |
| Main regulator | SFC and HKMA | MAS | FINMA | SEC (plus CFTC and states) | ESMA and national regulators |
| Law for asset tokens | SFO plus SFC token circulars | Securities and Futures Act | DLT Act (ledger-based securities) | Securities Act exemptions | MiFID II, DLT Pilot Regime, MiCA |
| Retail access | Yes for SFC-approved fund tokens | Mostly accredited and institutional | Yes, with a prospectus | Only through Reg A+ or Reg CF | Yes, with a prospectus |
| Stablecoin rules | HKMA licence since Aug 2025 | MAS stablecoin framework | FINMA guidance | Federal stablecoin law | MiCA |
| Best for | Bonds, funds, stablecoin rails | Bonds, funds, bank pilots | High-value private assets | Treasury funds, private credit | Cross-border offers in the EU |
Hong Kong stands out in two ways. The government issues digital bonds itself, and retail buyers can trade fund tokens on licensed platforms. Singapore and the US lead on bank pilots and Treasury funds. The best choice depends on your asset and your buyers.
Future of RWA Tokenization in Hong Kong
- 24/7 settlement: The HKMA plans to settle EnsembleTX in central bank money and run it around the clock by about the end of 2026. Tokens and cash could then swap at any hour.
- Government debt on chain as routine: The government will make digital bond sales regular and test token versions of Exchange Fund Bills before 2027.
- Stablecoins in trading: The 2026 Policy Address calls for licensed stablecoins to trade on VATPs and to settle money market fund tokens. HSBC plans to launch its Hong Kong dollar stablecoin in the second half of 2026.
- New asset types: Gold tokens, warehouse receipts and carbon credits are next in line. HKEX’s warehouse receipt pilot is set for 2027.
- New licences: Once the dealer and custodian bill passes, more firms will have a clear licence path to deal in and hold token assets.
How Coinsclone Is Supporting the Future of RWA Tokenization?
Coinsclone helps startups, large firms and finance houses build RWA token platforms from start to finish. Since 2018, our team has delivered 350+ platforms for 200+ clients across 20 industries. That work includes RWA token projects for firms in Hong Kong’s digital asset market.
Our RWA Tokenization Platform Development services combine rule-ready design, solid blockchain design and launch support. We help firms in global finance hubs turn real assets into tokens with more liquidity, openness and reach.
RWA Tokenization Services Offered by Coinsclone
Coinsclone provides a full range of RWA tokenization services, including:
- Asset Tokenization Platform Development
- Crypto Token Creation for Real-World Assets, with ERC-3643 permissioned tokens
- Smart Contract Development & Auditing
- Real Estate Tokenization Solutions
- Commodity & Precious Metal Tokenization
- Stablecoin Development for payment rails
With these services, Coinsclone helps firms build strong RWA platforms that link real assets with blockchain.
Frequently Asked Questions
Is RWA tokenization legal in Hong Kong?
Yes. Security tokens are allowed under current law. The SFC treats them as normal securities in a token wrapper, so the Securities and Futures Ordinance applies. Stablecoins fall under the Stablecoins Ordinance, in force since 1 August 2025.
Can retail investors buy tokenized assets in Hong Kong?
Yes, for SFC-approved products. Since 20 April 2026, retail buyers can trade tokens of SFC-approved funds on licensed VATPs, starting with money market funds. Most other security tokens are sold only to professional investors.
Who counts as a professional investor in Hong Kong?
Under the SFC’s Professional Investor Rules, a person needs a portfolio of at least HK$8 million. A firm qualifies with a portfolio of at least HK$8 million or total assets of at least HK$40 million.
Does a technology provider need an SFC licence?
Not always. A tech firm that only builds and runs the platform may not need its own licence if a licensed firm carries out the regulated activity, such as dealing. The licensed firm stays answerable for the whole setup, even the parts it outsources.
Can foreign companies tokenize assets in Hong Kong?
Yes. Foreign issuers can offer tokens in Hong Kong if they follow the same offer rules as local issuers. Most do this by selling to professional investors through SFC-licensed firms. Check whether the token is a security or not, as this changes the licence path.
Which companies hold Hong Kong stablecoin licences?
As of October 2026, two firms hold them. One is Anchorpoint Financial, a joint venture of Standard Chartered Bank (Hong Kong), HKT and Animoca Brands. The other is HSBC. The HKMA granted both licences on 10 April 2026 and says future licences will stay very limited.
Conclusion
By October 2026, Hong Kong has a working market for RWA tokenization, not just pilots. The SFC’s rules cover how tokens are issued and traded. The HKMA licenses stablecoins and settles deposit tokens. And the government keeps selling record digital bonds. For firms, the window is open now. Bonds, funds and gold have clear rules today, and new licences and asset types are on the way. A well-built platform that follows the rules is the way to take part.
See How Our MVP System Can Launch Your RWA Platform Faster
RWA Tokenization in Hong Kong — done right.
- MVP System:Launch your real-world asset tokenization platform up to 90% faster.
- Asset Tokenization Modules: Pre-built solutions for real estate, funds, commodities, and more — no heavy coding required.
- Compliance-Ready Framework:Built with Hong Kong’s regulatory landscape in mind for smoother approvals.
- Brand & Customization: Your platform, your assets, your investor experience.
- Revenue Engine: Earn through issuance fees, trading, asset management, and fractional ownership models.
See a free branded demo of your RWA platform in 48 hours — before you invest a cent.
Book a Free Demo to discover how our RWA tokenization solution can take you from concept to live platform in just 2–4 weeks.