P2P lending software development is the work of building an online platform where people and firms lend to each other directly, with no bank in the middle. In 2026, a basic MVP costs about $25,000 to $80,000 and takes 4 to 6 months, while a white label crypto lending build can go live in about 8 to 12 weeks.
This guide shows how such a platform moves money, which model to pick and the features you need. It also covers the rules in the US, UK, EU and India, and what a full build costs and how long it takes. You will also see how a platform earns on a single loan, with real fee numbers, and how to pick a lending software development company. By the end, you will know what to build first, what to plug in from partners and what to budget.
In this guide:
- How a P2P loan flows from request to repayment, and where the platform earns on each one
- The four business models, and a quick test to choose yours
- Must-have features, what goes into an MVP and the partner tools to plug in rather than build
- The hard limits set by the SEC, FCA, EU law and the RBI in 2026
- Real cost and time ranges, white label vs custom, and how to choose a development partner
See How Our MVP System Can Launch Your P2P Lending Platform Faster!
P2P Lending Software Development — done right.
- MVP System: Go live with your lending marketplace 90% faster.
- Payments & KYC: Pre-integrated modules — no coding, no hassle.
- Brand & Customization: Your design, your loan categories, your investors.
- Revenue Engine: Earn from transaction fees, interest spreads, and premium listings.
Get a free branded demo of your lending platform in just 48 hours — before you invest a cent.
Book a Free Demo to see how our P2P Lending Software Solution can take you from idea to live platform in just 8-12 weeks.
What Is P2P Lending Software Development?
P2P lending software development is the process of building a digital platform that lets people or firms lend and borrow money without a bank. The software runs the whole loan life: sign-up, ID checks, credit scores, loan listings, funding, payouts, repayments and records.
In simple terms, the platform is a marketplace. Borrowers post what they need. Lenders pick the loans they like and fund them, often in small slices. The platform checks risk, moves the money through a safe account and takes a fee for running the show.
There are two broad flavours today:
- Fiat P2P lending: Loans in dollars, pounds, euros or rupees, run by a licensed firm with bank escrow, credit bureau checks and local rules. Prosper in the US is the classic example.
- Crypto P2P lending: Loans in stablecoins or crypto, often backed by crypto or NFT collateral. Smart contracts hold the funds, release them and enforce the terms on chain.
Many new platforms mix both: a normal app and fiat rails up front, with a blockchain ledger or smart contract escrow behind it.
How Does P2P Lending Software Work?
A P2P platform does five jobs in a set order. It checks people, prices risk, finds lenders, holds the money safely and then collects and splits each payment. The same flow applies whether the loan is in dollars or in stablecoins. Only the plumbing changes.
Here is how it works on a classic fiat platform:
- Sign-up and checks: Borrowers and lenders register and pass KYC and AML checks. The platform links a bank account or card.
- Loan request: The borrower states the amount, term and purpose. The platform pulls a credit report and bank data.
- Risk grade: A scoring model gives the loan a grade and a rate. A better grade means a lower rate.
- Listing and funding: The loan goes live. Lenders fund it in slices, often by hand or through auto-invest rules.
- Escrow and payout: Funds sit in a bank-run escrow or trust account until the loan is fully funded. The platform then pays the borrower, minus its fee.
- Repayment and split: The borrower pays monthly. The platform takes its servicing fee and passes the rest to each lender in proportion to their slice.
- Collections: If a payment is late, the system sends nudges, adds late fees and, if needed, hands the loan to a debt firm.
On a crypto platform, the steps are the same, but the parts differ:
- Wallet link and sign-up: Users connect their crypto wallets and pass ID checks (KYC and AML) to join as borrowers or lenders.
- Loan request: Borrowers state the amount, purpose, term and collateral, usually in crypto or NFTs.
- Risk check: Smart contracts and models check risk using on-chain history, wallet activity and the value of the collateral.
- Loan listing: Approved requests are listed, and lenders review the terms and pick loans that suit them.
- Funding via crypto: One or more lenders fund the loan in crypto or stablecoins. A smart contract holds the money until the loan is fully backed.
- Smart contract payout: Once funded, the contract sends the funds to the borrower’s wallet and locks the collateral.
- Repayment in crypto: The borrower pays the contract, and it splits each payment among the lenders automatically. If the borrower defaults, the lender can claim the collateral.
- Real-time view: Both sides can track loan status, repayments and returns on a live dashboard backed by the chain.
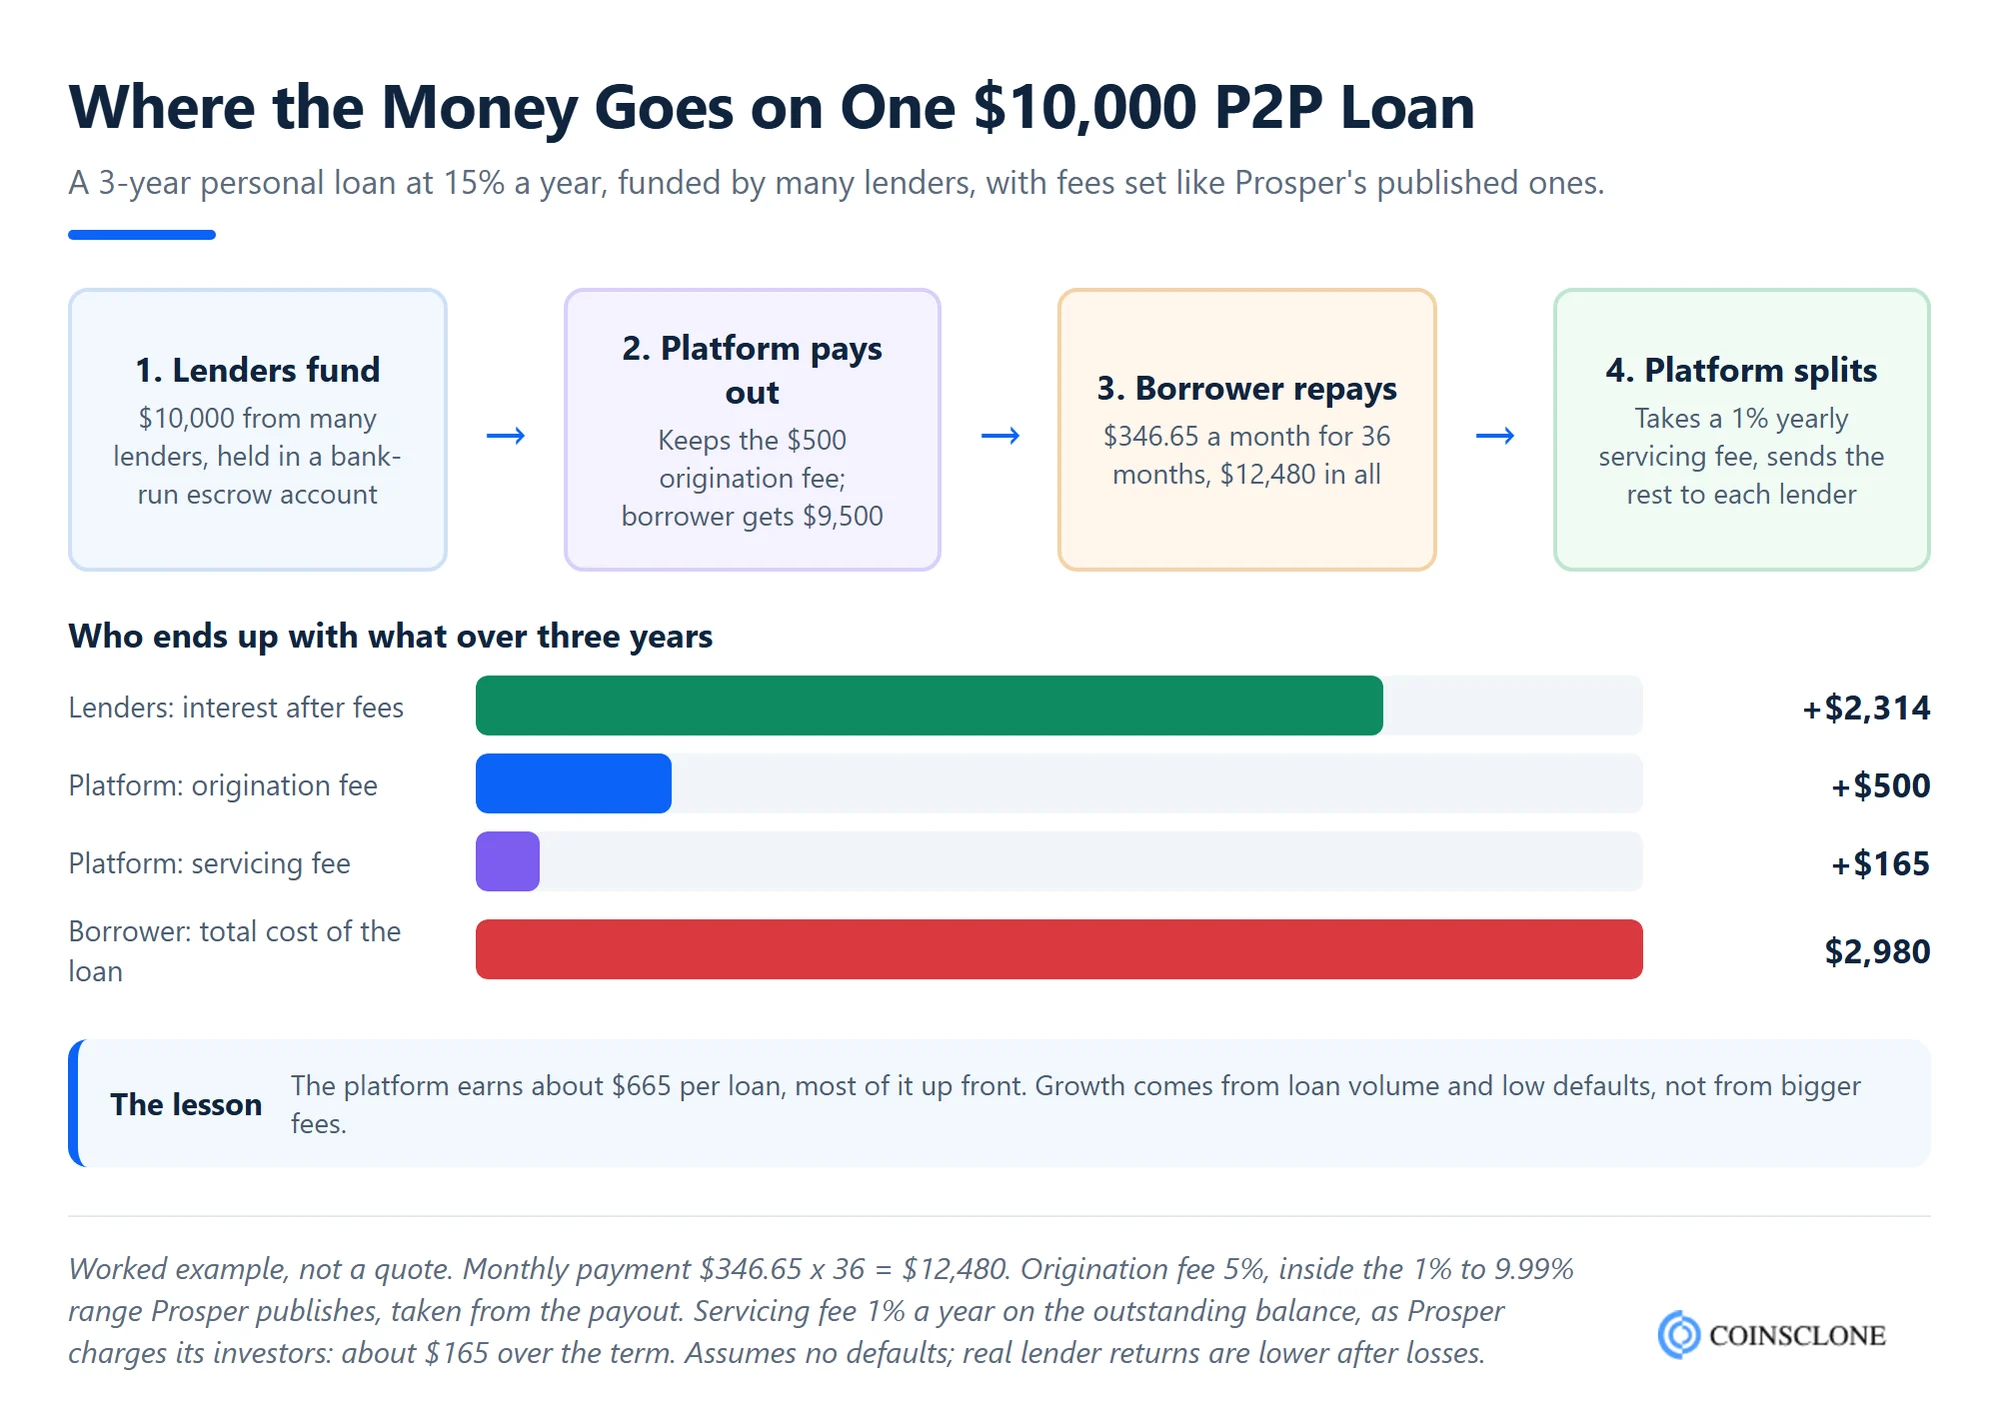
The worked example below shows where each dollar goes on one typical fiat loan.
Types of P2P Lending Platforms and Business Models
Before you write a line of code, decide two things: who borrows on your platform, and who carries the risk. Both choices shape your features, your licence and your budget.
Platform Types by Borrower
- Personal loan platforms: Small unsecured loans to people for debt payoff, home repairs or bills. They need strong credit scoring and collection tools.
- SME and business lending: Loans to small firms, often larger and secured. They need checks on firm data, uploads of accounts and longer terms.
- Real estate lending: Loans backed by property, split among many lenders. These overlap with real estate tokenization on blockchain rails.
- Invoice and supply chain finance: Firms sell or borrow against unpaid invoices. The software must check invoices and track the buyer who pays.
- Microlending: Very small loans, often in emerging markets, where mobile money and low fees matter most.
- Crypto and NFT backed lending: Loans against crypto or NFTs held in a smart contract. Platforms like this need price feeds and clear default rules. See our guide to NFT lending platform development.
Business Models by Risk
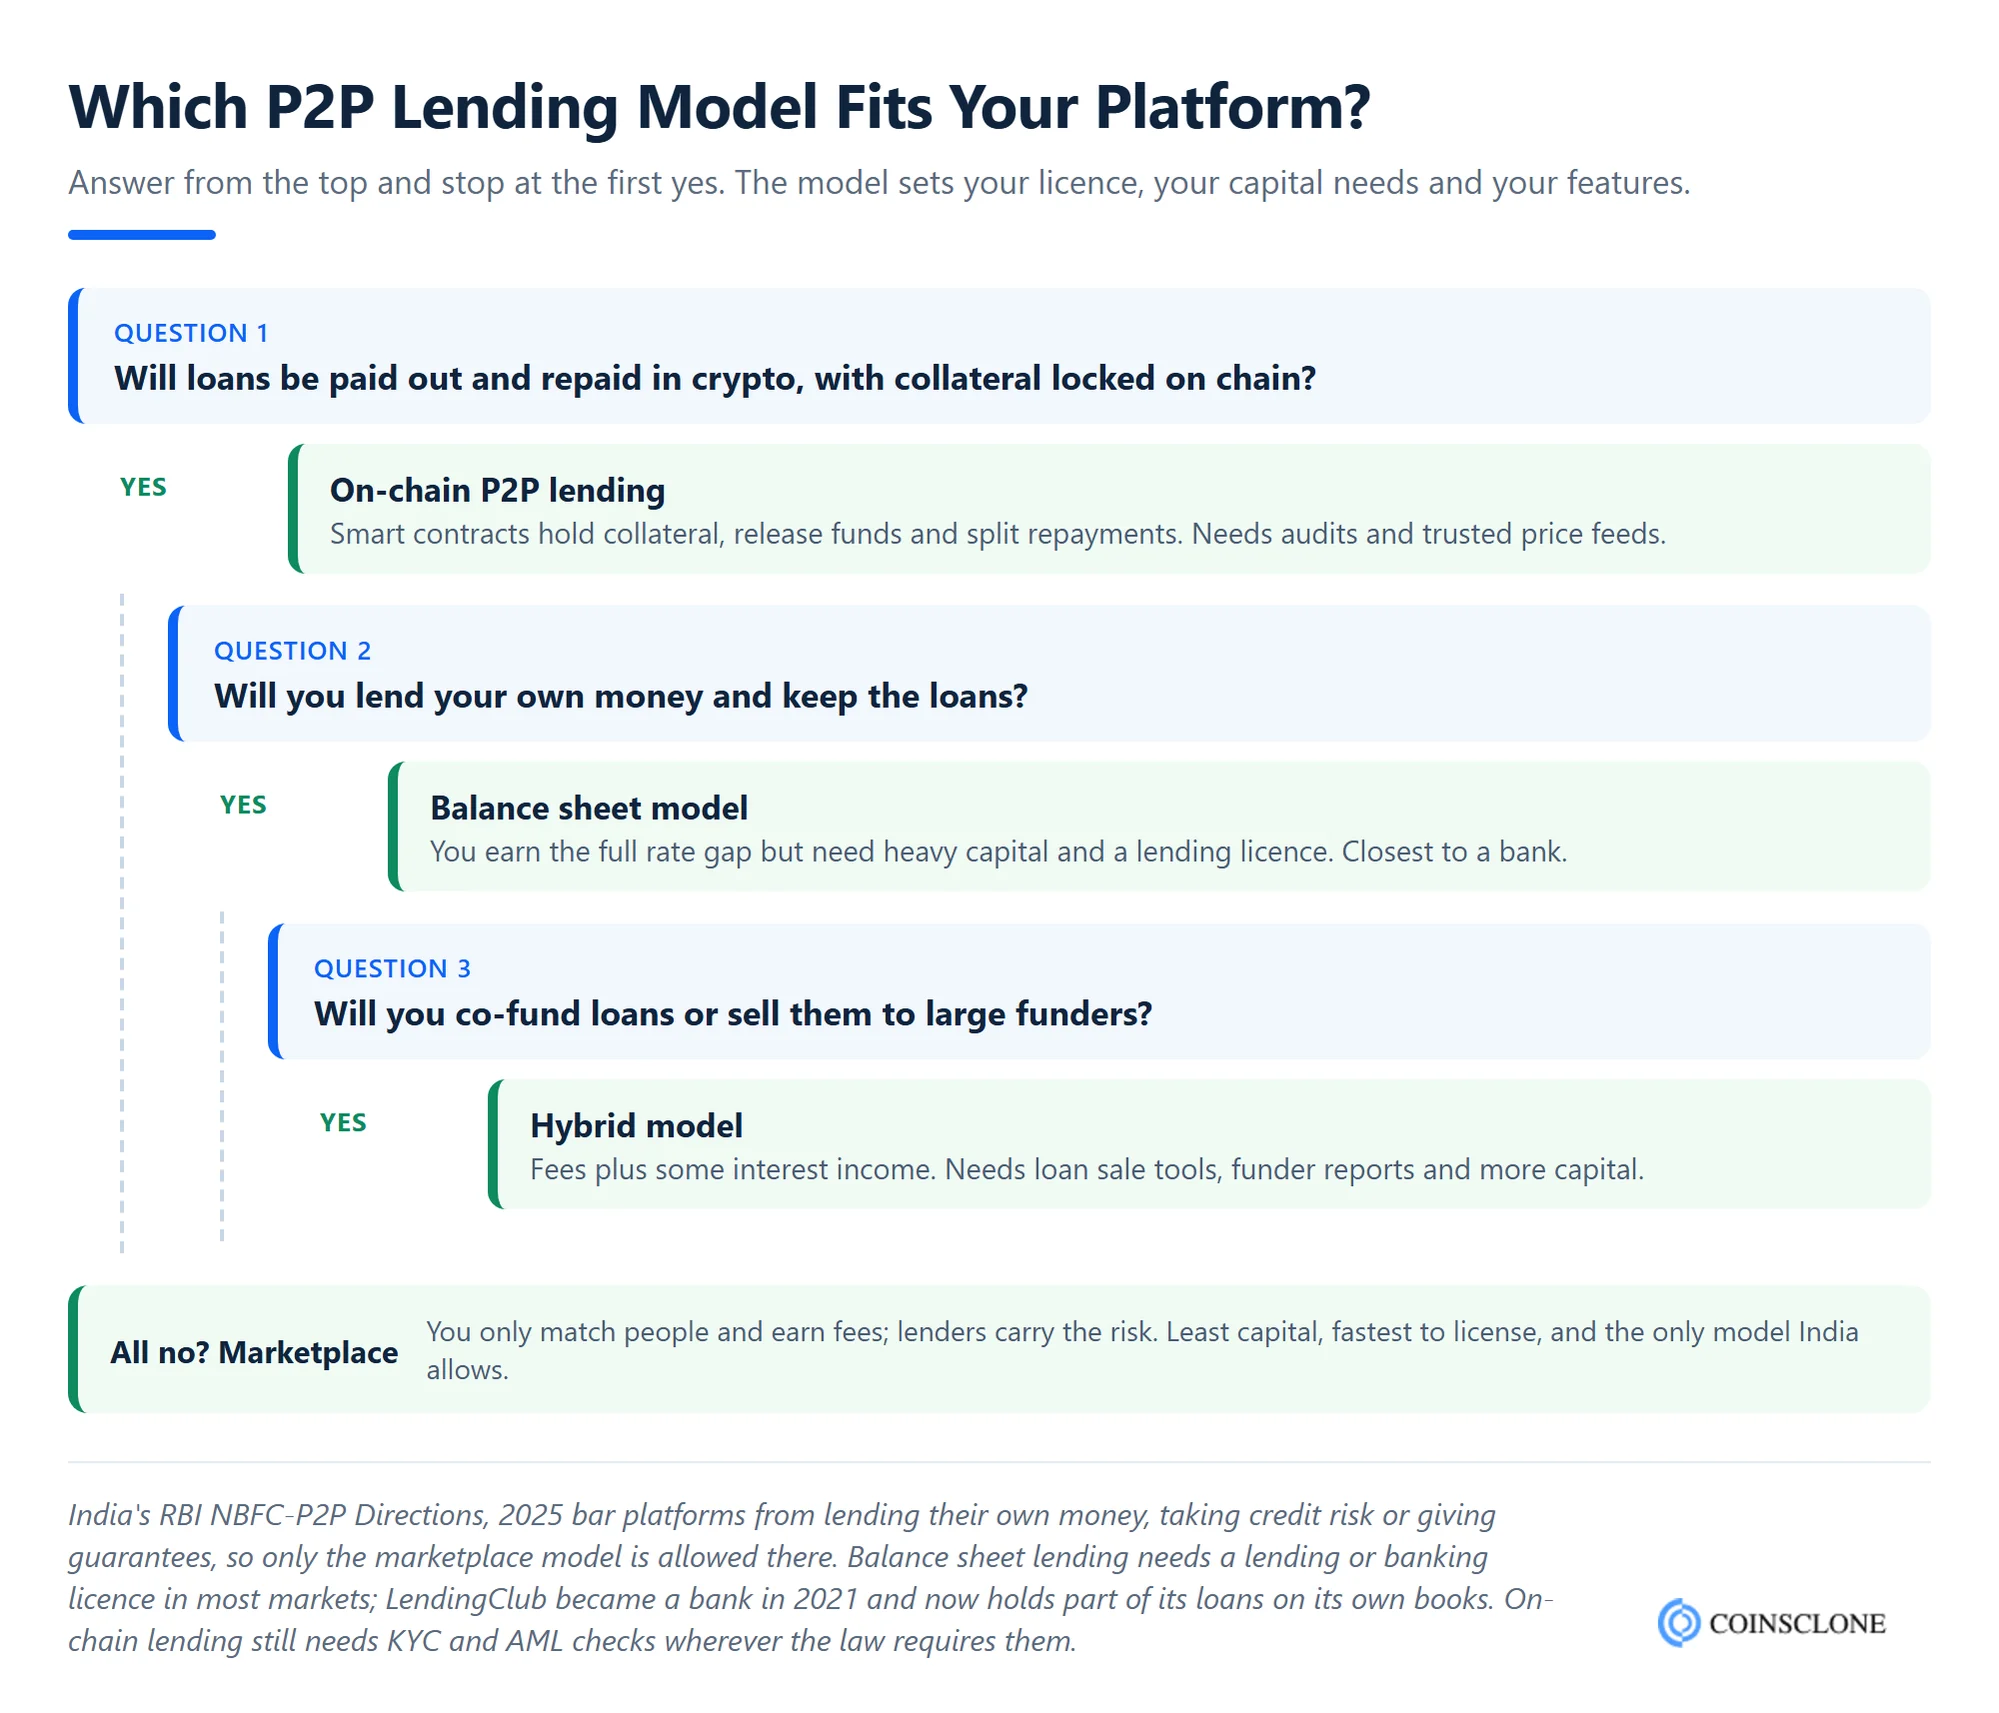
- Marketplace model: The platform only matches people and earns fees. Lenders carry the credit risk. It needs the least capital, and it is the only model India’s RBI allows.
- Balance sheet model: The platform lends its own money and keeps the loans. It earns the full rate gap but needs heavy capital and, in most places, a lending licence.
- Hybrid model: The platform funds part of each loan or sells loans to big buyers. It mixes fee income with interest income.
- On-chain model: Smart contracts match, hold and repay funds. The code enforces the terms, and anyone with a wallet can join where the law allows. Pooled lending, where all lenders share one pool, is a different design. Our DeFi lending and borrowing platform development guide covers it.
Use the quick test below to see which model fits your plan.
Must-Have Features of P2P Lending Software
P2P lending platforms come with a wide set of features for borrowers, lenders and admins. These tools make the platform easy to use, run key tasks on their own and keep every payment safe, legal and clear.
General Functionality
- User sign-up and checks with forms you can change
- Profile edits and file uploads
- Instant messages between borrowers, lenders and admins
- A full audit trail of every action
- Automatic payments in more than one currency
Account Management for End Users
- Pages where users update their own details
- Access to past payments and loan status
- Alerts and reminders for key actions
Borrower Credit Risk Checks
- Automatic reading and checking of uploaded files
- AI credit scores and borrower groups
- Live risk scores for lenders, with scoring rules you can tune
Payment Processing
- Automatic and repeat payment pulls
- Support for many payment methods: bank, card, wallet and crypto
- Set fees charged at each payment
Lender-Side Features
- Create and manage loan offers with your own terms
- Quick loan checks with set yes or no rules
- Live portfolio tracking and risk charts
- Auto-invest: Rules that spread money across loans by grade, term and amount
- Alerts for missed payments, with set late fees
- E-signing and safe file storage
- Automatic loan reports to credit bureaus
Borrower-Side Features
- Loan calculator: Estimate amounts, rates and monthly payments, and compare offers
- Apply and repay: Ready forms, live status, a choice of plans and due-date alerts
- Early payoff and reschedule requests: Let borrowers clear a loan early or ask for a new plan
Admin Features
- User pre-checks: AI checks of ID, income and other rules, approval workflows and KYC and AML checks
- Platform data: Live dashboards, set and one-off reports, and tracking of loans, users and income
- Collections desk: Queues for late loans, payment plans and hand-off to agencies
Security Features
- KYC checks: Automatic ID checks, document checks and AML screening
- Multi-factor login (MFA): Extra login safety via SMS, email or an authenticator app
- Biometric login: Face or fingerprint checks for safer access
- Document checks: Automatic tests that uploaded files are real and complete
With these features in place, P2P lending software gives borrowers, lenders and admins a smooth, safe and complete lending experience.
Key Components and Integrations of P2P Lending Software
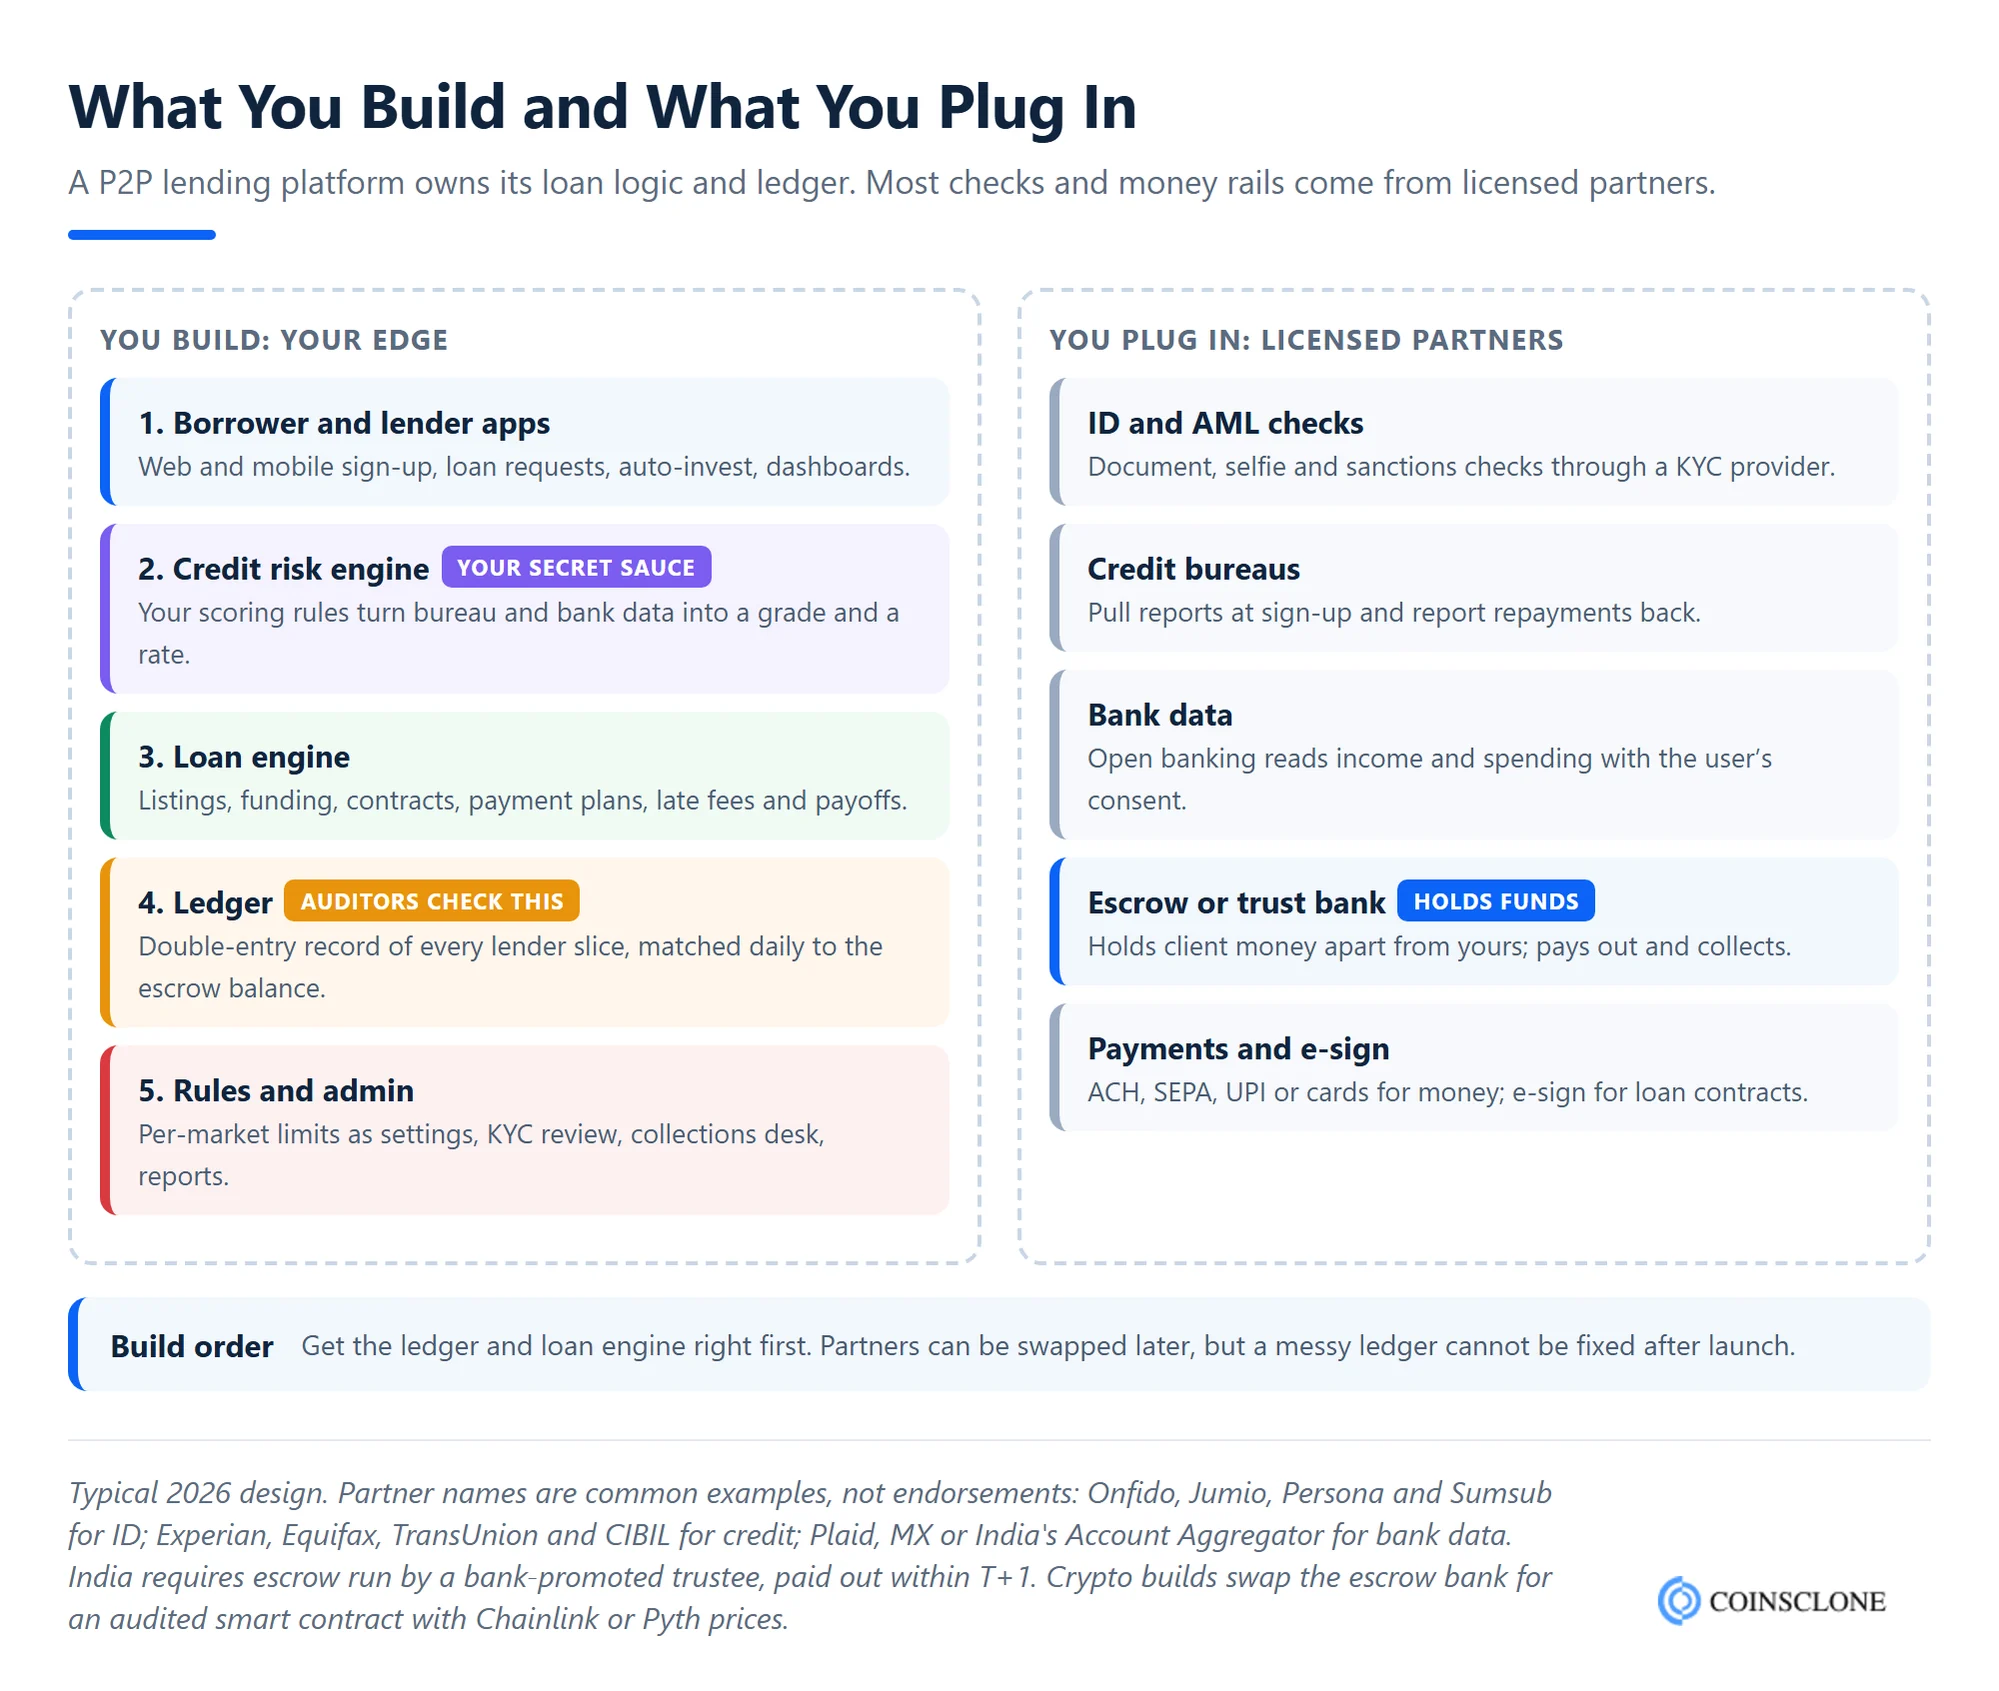
Building sound P2P lending software means joining a set of core modules so the platform stays safe and simple for everyone. The must-have parts are:
- User accounts: Safe sign-up, profiles, file uploads and self-help tools for both sides.
- Credit risk engine: AI tools that read, check and score borrower data, linked to credit bureaus and other data sources.
- Loan setup and servicing: Tools for requests, sign-off, contracts, payouts, payment plans and status tracking.
- Payments: Gateways for bank transfer, card, e-wallet and crypto, with repeat payments and fees taken on their own.
- Escrow or trust ledger: A record of whose money sits where, matched every day to the bank or smart contract balance.
- Portfolio management: Lenders track and judge their loans in real time for returns and risk.
- Platform analytics: Admin dashboards and reports on key numbers, user activity and loan behaviour.
- Security and compliance: Multi-factor and biometric login, fraud checks, encryption, KYC and AML steps and rule-based reports.
The smart move is to build what makes you different and plug in proven partners for the rest. The map below shows which parts you own and which you rent.
Tech Stack for P2P Lending Software
There is no single right stack, but most 2026 builds use proven, well-staffed tools. A common setup looks like this:
| Layer | Common choices |
| Web front end | React or Next.js |
| Mobile apps | Flutter or React Native |
| Back end | Node.js, Java (Spring) or Python (Django, FastAPI) |
| Database | PostgreSQL for loans and ledgers, Redis for caching |
| Cloud | AWS, Google Cloud or Azure |
| KYC and ID | Onfido, Jumio, Persona or Sumsub |
| Bank data | Plaid, MX or a local open banking API |
| Payments | Stripe, Dwolla, ACH or SEPA rails, UPI in India |
| Smart contracts (crypto) | Solidity on Ethereum, Base, Polygon or BNB Chain |
| Price feeds (crypto) | Chainlink or Pyth |
Keep loan and ledger data in a relational database with strict, double-entry records. That one choice saves months of clean-up when auditors arrive.
How Do P2P Lending Platforms Make Money?
A P2P platform earns a little on every loan, so revenue grows with loan volume. Most platforms mix several of these streams:
- Origination fee: A one-time cut of each loan, taken from the payout. Prosper charges borrowers 1% to 9.99%, based on the loan grade.
- Servicing fee: A yearly fee on what lenders hold. Prosper charges lenders 1% a year on the outstanding balance.
- Late and failed payment fees: Set charges when a borrower pays late or a payment bounces.
- Secondary market fee: A small cut when lenders sell their loan slices to other lenders before term.
- Premium tools: Paid plans for auto-invest, deeper data or early access to new loans.
- Spread: On balance sheet or hybrid platforms, the gap between what borrowers pay and what funders earn.
On crypto platforms, the contract can take the same fees in stablecoins, plus a share of any liquidation when collateral is sold. Monthly payments in USDC work much like recurring crypto payments. The borrower signs off on a plan once, and the contract pulls and splits each payment.
On the $10,000 loan in the example above, the platform earns about $665 over three years. That is why volume, low default rates and repeat borrowers matter more than any single fee.
Benefits of Building P2P Lending Software
Investing in P2P lending software brings clear gains in today’s fast-moving finance market. As demand grows for open and direct lending, firms use P2P platforms to find new revenue, work faster and give users more control over their money.
Lower Costs and Better Rates
With no bank branch network to fund, a P2P platform costs far less to run. Borrowers can get lower rates, and lenders can earn better returns than a savings account.
Custom Features and Flexibility
A custom-built platform lets you shape features, user journeys and loan products around one market and its rules. That gives you a clear edge over generic tools.
Stronger Security and Compliance
A modern build brings encryption, multi-factor login and compliance tools from day one. That builds trust and keeps you in line with the rules.
Room to Grow
Well-built software grows with your business. You can add loan types, users and features without slowing the platform down.
Automation and New Tech
AI and blockchain can run credit checks, loan setup, servicing and tracking with little manual work. That cuts cost and makes every step easy to audit.
Market Opportunity
Precedence Research puts the global P2P lending market at $176.5 billion in 2025 and about $222.9 billion in 2026. It expects the market to reach about $1.6 trillion by 2035, growing near 25% a year. Forecasts like this vary between firms, but every major one points up.
Risks of Running a P2P Lending Platform
P2P lending is not risk-free, for lenders or for the operator. A P2P platform is a trust business. These are the risks that sink weak platforms, and the software choices that guard against them:
- Defaults: If too many loans go bad, lenders leave. Invest early in scoring, bank data checks and clear risk grades, and show past default rates openly.
- Slow collections: Recovering late loans is hard and costly. Build a collections desk and a partner agency hand-off into the first release.
- Funding gaps: A marketplace needs both sides. Without enough lenders, good borrowers wait and leave. Auto-invest tools and a few large funders help early on.
- Rule changes: Regulators have tightened P2P rules more than once. Keep limits, disclosures and reports as settings, not hard code, so you can change them fast.
- Platform failure: If the operator shuts down, lenders still need to be repaid. Keep client money in a separate escrow or trust account and agree a backup servicer. Crypto platforms can go further and publish proof of reserves, so lenders can check that pooled funds and collateral are really there.
- Smart contract bugs: On crypto platforms, a code flaw can drain funds in minutes. Audits, price feeds from trusted oracles and admin keys held in a multisig are a must.
Is P2P Lending Legal? Rules by Market in 2026
P2P lending software itself is legal. What is regulated is the business of matching loans and holding client money. The rules differ a lot by country, so build your platform around the market you launch in first.
| Market | Main rules | Hard limits that shape the software |
| United States | SEC securities rules, CFPB and state lending laws | Loan notes sold to the public are securities. Regulation Crowdfunding caps a raise at $5 million in 12 months |
| United Kingdom | FCA rules for loan-based crowdfunding (PS19/14) | New retail lenders may put no more than 10% of their investable assets into P2P, after an appropriateness test |
| European Union | Crowdfunding Regulation 2020/1503 and Consumer Credit Directive 2023/2225 | Business loans up to EUR 5 million per project owner in 12 months; consumer crowdfunding credit comes under the new consumer credit rules from 20 November 2026 |
| India | RBI NBFC-P2P Directions, 2025 | Lender cap Rs 50 lakh across all platforms; borrower cap Rs 10 lakh; Rs 50,000 per lender per borrower; terms up to 36 months; escrow paid out within T+1; no guarantees |
In the US, the SEC’s Regulation Crowdfunding lets firms raise up to $5 million a year through a registered portal. Consumer platforms that sell loan notes to the public, as Prosper does, register them with the SEC. They also follow state lending licences and federal lending laws.
In the UK, the FCA’s P2P rules have applied since 9 December 2019. They require an appropriateness test and the 10% cap for new retail lenders who take no advice.
In the EU, one crowdfunding licence works across all member states for loans to firms. The second Consumer Credit Directive applies from 20 November 2026. It brings crowdfunded personal loans under its rules for the first time.
In India, the RBI’s P2P lending directions require an NBFC-P2P licence with at least Rs 2 crore in owned funds. The platform may not take credit risk or promise returns.
Crypto P2P lending adds another layer: AML and Travel Rule checks on transfers, and in the EU, MiCA rules for any crypto service you offer alongside the loans. Get legal advice in each market before launch, and write the limits above into your rules engine from day one.
Examples of P2P Lending Platforms in 2026
The P2P lending platforms still open to retail lenders in 2026 either work through a bank partner or hold a licence built for this kind of business. The well-known names show which models lasted:
- Prosper (US): The best-known US consumer P2P platform still open to retail lenders. A partner bank, WebBank, makes the loans, and Prosper sells lenders notes tied to them, registered with the SEC.
- LendingClub (US): Once the largest P2P lender, it retired its retail notes platform on 31 December 2020 after buying Radius Bank. It now lends as a bank.
- Zopa and Funding Circle (UK): Zopa closed its P2P investment arm in December 2021 to focus on its bank. Funding Circle closed its retail platform to new lenders in March 2022 and now funds small business loans from institutions.
- Mintos (EU): A Latvian loan marketplace run by a MiFID II licensed investment firm under Latvijas Banka. In February 2026, it began applying for a European banking licence.
- LenDenClub (India): An RBI-registered NBFC-P2P platform, bound by the lender and borrower caps in the table above.
The lesson for builders is plain. Plan for licences, bank or escrow partners and large funders from the start, not only for retail lenders.
P2P Crypto Lending Software: Blockchain Use Cases
Blockchain opens new ways to use P2P lending software. These use cases show why it is a smart bet for fintech and crypto firms that want to reshape lending in 2026 and beyond.
Tokenized Loans
A P2P platform can tokenize loans the same way you tokenize real estate or art. Each loan is split into tokens of part ownership. Many lenders can fund parts of one loan, which adds choice and makes it easier to sell out early.
Decentralized Lending Platforms
DeFi platforms cut out banks and other middlemen. Smart contracts approve loans, take payments and pay out interest on their own. This lowers running costs and gives a lending experience that needs no trust in a middleman.
Fractional Lending
With blockchain, one large loan can be split into small units funded by many lenders. This lowers the entry point for small lenders, spreads risk better and adds cash flow to the system.
Identity Checks
Safe identity checks are vital in finance, and blockchain makes them stronger. A shared ledger lets platforms run KYC and AML checks automatically. Borrower IDs are checked and stored in a way that cannot be changed, so every party sees the same trusted record.
Cross-Border Lending
Blockchain removes borders from lending. Borrowers can apply from anywhere, and lenders can fund loans worldwide, often with stablecoins. This opens new markets, spreads risk across countries and helps more people get access to credit.
These use cases lead straight to the build itself. If your plan also includes buyer and seller trading of crypto, a P2P crypto exchange development company can run escrow trading alongside your lending product.
How to Build a P2P Lending Platform in 6 Steps
From idea to launch, a good P2P lending platform needs a clear, step-by-step plan. Each stage helps make the final product safe, simple and ready to grow.
Market Research and Requirements
Study your target borrowers and lenders, check rival platforms and find the gap you will fill. From that, set your niche, your selling points and the features you must have.
Licence, Safety and Tech Planning
Pick your launch market and its licence path first, using the rules table above. Plan for data and payment rules such as GDPR and PCI DSS. Then plan your safety tools: two-step login, fraud checks and DDoS guards.
Features, Architecture and UI/UX Design
Design the core features, the system layout and separate screens for borrowers, lenders and admins. Keep each journey short and clear so people finish sign-up and come back.
Tech Stack and Build
Choose a safe stack that can grow with you. Build the back end and APIs, the front end and the data store. Run automatic and manual tests as you go.
Integration, Testing and Compliance Checks
Connect partner services such as KYC, credit bureaus, payment gateways, escrow banks and, for crypto, blockchain networks. Then run full tests for usability, security and function, and a third-party audit for any smart contracts.
Launch and Improvement
After every check passes, launch, ideally with a small group first. Track user feedback and platform data to guide each update.
These are the main steps. If you plan to build your platform, Coinsclone can help at each stage.
What Should a P2P Lending MVP Include?
A P2P lending MVP should include only what one loan needs from request to repayment. That means sign-up with KYC, a loan request form, a basic risk grade, a loan listing, lender funding, an escrow payout and automatic repayments split among lenders. Add an admin panel to approve users and loans, plus the reports your regulator asks for.
Leave these for later releases:
- Auto-invest rules and a secondary market for loan slices
- AI credit scoring beyond your bureau and bank data checks
- Native mobile apps, if a mobile-friendly web app will do at first
- More currencies, more loan types and more countries
Track two numbers from day one: how fast loans get fully funded, and how many repayments arrive on time. Slow funding means you need more lenders. Late payments mean your scoring needs work.
Factors that Drive ROI for P2P Lending Software
How you design the platform decides how well it pays. These drivers speed up work, keep users happy and keep the platform in profit.
Less Manual Work on Each Loan
Automation cuts manual work, speeds up loan decisions and reduces errors that would hurt both efficiency and profit.
A Strong Matching Engine
The platform should match borrowers and lenders by risk and preference. Good matching means more loans funded and happier lenders.
User-Friendly UI and UX
Take the stress out of money tasks. Simple screens lift sign-ups, repeat use and trust.
Easy-to-Use APIs
Clean APIs let you link with other fintech tools and partners, which widens what your platform can offer.
With these drivers in mind, the next question is budget.
How Much Does P2P Lending Software Development Cost?
P2P lending software development costs about $25,000 to $80,000 for an MVP and $80,000 to $200,000 for a standard platform in 2026. Advanced and enterprise builds run from $200,000 to over $1 million. The final figure depends on its features, the depth of custom work and the rules of your market. Published 2026 agency cost guides fall into four broad bands:
| Scope | Typical cost |
| MVP: sign-up, loan listing, basic repayment | $25,000 to $80,000 |
| Standard: full borrower and lender portals, compliance tools, admin | $80,000 to $200,000 |
| Advanced: AI scoring, secondary market, open banking or blockchain | $200,000 to $500,000 |
| Enterprise: multi-market, API-first, full institutional features | $500,000 to $1,000,000+ |
Some large firms quote $400,000 to over $1 million for a platform of average scope. Smart contracts and AI scoring push a build toward the upper bands.
Budget for costs outside the code too. Legal advice and licences, KYC and credit bureau fees per check, a smart contract audit for crypto builds, and hosting and upkeep of about 15% to 20% of the build cost each year all add up.
How Long Does P2P Lending Software Development Take?
A P2P lending MVP usually takes 4 to 6 months, and a full custom platform takes 8 to 15 months. A white label crypto lending build from Coinsclone goes live in about 8 to 12 weeks. In most markets, the licence takes longer than the code, so start that process first.
For a custom platform of average scope, published 2026 agency timelines break the work into these phases:
| Phase | Typical time |
| Research and requirements | 3 to 4 weeks |
| Product design and user journeys | 4 to 8 weeks |
| Build: back end, web app, admin and tests | 6 to 9 months |
| Partner links: KYC, credit bureaus, payments, escrow bank | 4 to 8 weeks, alongside the build |
| Release to a small first group | 1 to 3 weeks |
Phases overlap, so the total is shorter than the sum. Crypto builds add a smart contract audit, which often takes several weeks of its own.
White Label P2P Lending Platform vs Custom Build
A white label P2P lending platform is ready-made software that you rebrand, set up for your loan products and launch under your own name. It suits a fast market test. A custom build suits a unique scoring model, loan type or licence path. Many firms start on white label and add custom modules once real users show what they need.
| Factor | White label | Custom build |
| Time to launch | Weeks (Coinsclone crypto lending: about 8 to 12 weeks) | 8 to 15 months for a full platform |
| Upfront cost | Lower: you pay for setup and changes, not a full build | $80,000 to $200,000+ for a standard platform |
| Control | Core logic fixed by the vendor, branding and settings yours | You own every rule, screen and line of code |
| Best for | A standard loan product, a first market, a quick test | Unique scoring, several markets, deep bank links |
| Main risk | Vendor lock-in if you cannot get the source code | Slower launch and a bigger budget at risk |
Before you sign, ask whether you get the source code, who hosts the platform and who carries out updates when the rules change. For crypto loans backed by collateral, our Aave clone script gives you a tested lending base to rebrand.
How to Choose a Lending Software Development Company
The right lending software development company has shipped live lending products, knows your market’s rules and will hand you the source code. Price matters less than these points, because a cheap build that fails an audit costs more later.
Check each partner against this list:
- Lending track record: Ask for live platforms, not mockups, and a reference client you can call.
- Rules knowledge: They should know your licence path, from SEC and state rules in the US to the RBI caps in India.
- Ledger and escrow skills: Ask how they keep a double-entry ledger in step with the bank or smart contract balance each day.
- Security proof: Look for penetration tests and, for crypto, third-party smart contract audits.
- Code ownership: Get the source code and full rights in the contract.
- Support after launch: Agree who fixes bugs, updates the rules engine and keeps the servers running.
Good lending software development services cover the whole path: product scoping, UX design, the build itself, partner links, audits, launch and upkeep. A partner that only writes code leaves you to manage the hardest parts alone.
Why Choose Coinsclone as Your P2P Lending Software Development Company?
Coinsclone is a trusted name in crypto and a leading P2P lending software development company. Since 2018, the team has delivered 350+ platforms for 200+ clients across 20 industries. Whether you start from scratch or upgrade an existing platform, Coinsclone takes you from idea to launch smoothly.
Here’s why Coinsclone stands out:
- Crypto expertise: Deep experience in P2P lending and blockchain, built to meet the rules of your market.
- Custom and white label options: Fast white label launches or fully custom platforms, based on your business needs.
- Top-notch security: Multi-factor login, biometric checks, AI fraud alerts and audited smart contracts.
- End-to-end support: Planning, build, launch and upkeep, all in one place.
- Easy links: Connects to payment rails, credit bureaus, KYC tools and more.
Want crypto loans with on-chain escrow? Coinsclone’s DeFi development company team builds them with you, from the smart contracts to the apps.
Partnering with Coinsclone helps you launch faster, lower your risk and stay ahead in the fast-growing P2P lending market.
See How Our MVP System Can Launch Your P2P Lending Platform Faster!
P2P Lending Software Development — done right.
- MVP System: Go live with your lending marketplace 90% faster.
- Payments & KYC: Pre-integrated modules — no coding, no hassle.
- Brand & Customization: Your design, your loan categories, your investors.
- Revenue Engine: Earn from transaction fees, interest spreads, and premium listings.
Get a free branded demo of your lending platform in just 48 hours — before you invest a cent.
Book a Free Demo to see how our P2P Lending Software Solution can take you from idea to live platform in just 8-12 weeks.
Frequently Asked Questions
What is P2P lending software?
P2P lending software is a web or mobile app that lets people lend to each other directly. Borrowers post loan requests, and lenders fund them. The system handles matching, interest, repayment plans and payment records on its own.
How does P2P lending software work?
It connects lenders and borrowers on one platform. Borrowers apply, the system checks and grades them, and lenders fund the loans they like. The software then runs the contract, the payout, repayments and the split to each lender for the life of the loan.
What features are required in P2P lending software?
Core features include sign-up with KYC, credit risk checks, loan listings and auto-invest. You also need repayments that run on their own, a payment log, a collections desk and admin dashboards. Most platforms also add fraud alerts, e-signing and reports to credit bureaus.
Is P2P lending software legal and regulated?
The software itself is legal, but the platform must follow local finance rules. In the UK, the FCA limits new retail lenders to 10% of their investable assets. In India, the RBI caps each lender at Rs 50 lakh across all platforms. In the EU, crowdfunding and consumer credit laws apply, and in the US, loan notes sold to the public are securities.
How much does it cost to build a P2P lending platform?
Published 2026 ranges run from about $25,000 to $80,000 for an MVP, $80,000 to $200,000 for a standard platform and $200,000 to $500,000 for advanced builds with AI scoring or blockchain. Enterprise platforms can pass $1 million. A white label base cuts both cost and time.
How long does it take to develop P2P lending software?
An MVP usually takes 4 to 6 months, and a full custom platform 8 to 15 months. A white label crypto lending build can go live in about 8 to 12 weeks, but licences in your market may take longer than the code.
How does a P2P lending platform make money?
Mainly through origination fees taken from each loan payout and yearly servicing fees charged to lenders. Late fees, secondary market fees and premium plans add more. Prosper, for example, charges borrowers 1% to 9.99% and lenders 1% a year.
Are there any free trials for P2P lending software?
Most P2P lending software vendors offer a live demo rather than a free trial. A lending platform needs KYC, payment and escrow links set up for your market before it can run real loans, so a self-serve trial shows little. Ask for a demo with your own loan product, and test the borrower, lender and admin journeys. Coinsclone offers a free live demo of its lending builds.
Why is Prosper the only big P2P lending platform left in the US?
Because US rules treat loan notes sold to the public as securities, which makes retail P2P lending costly to run. Prosper registers its notes with the SEC and works with a partner bank that makes the loans. LendingClub, the other big name, retired its retail notes platform at the end of 2020 and became a bank. A new US platform can register its notes, use a Reg A or Reg D exemption, or sell loans only to institutions.
Do I need a bank partner to launch P2P lending in the US?
Usually yes, unless you get state lending licences in every state you serve. Most US platforms use a partner bank to make the loans, then buy them back or sell notes tied to them. Prosper works this way with WebBank. The bank partner route is faster, but the bank will check your scoring, compliance and collections before it signs.
Do I need a licence if my P2P platform never holds client money?
In most markets, yes. Regulators look at what the platform does, not only where the money sits. Matching loans and running payments is a regulated activity in the UK, the EU and India, even when a bank holds the escrow. In the US, the notes you sell to lenders are securities. Get legal advice in your launch market before you build.
Should I build custom P2P lending software or use white label?
Choose white label if you want to test a market fast with a standard loan product. Choose custom if your scoring, loan type or licence needs are unique. Many firms launch on white label and then add custom modules.
What is the difference between P2P lending software and traditional lending systems?
Traditional lending runs through banks that take deposits and lend their own money. P2P software links lenders and borrowers directly, so the platform earns fees instead of a rate gap. Digital checks replace slow manual steps, which makes loans faster to match and manage.
Who uses P2P lending software?
Fintech startups, lending marketplaces, credit unions, crypto platforms and firms that want to offer loans without becoming a bank. Their users are individual lenders, small firms and people who need personal loans.
What technologies are used in P2P lending software development?
Most builds use React or Flutter for the apps, Node.js, Java or Python for the back end, PostgreSQL for data and AWS or Google Cloud for hosting. They plug in KYC, credit bureau, bank data and payment APIs. Crypto platforms add smart contracts in Solidity and price feeds from Chainlink or Pyth.
See How Our MVP System Can Launch Your P2P Lending Platform Faster!
P2P Lending Software Development — done right.
- MVP System: Go live with your lending marketplace 90% faster.
- Payments & KYC: Pre-integrated modules — no coding, no hassle.
- Brand & Customization: Your design, your loan categories, your investors.
- Revenue Engine: Earn from transaction fees, interest spreads, and premium listings.
Get a free branded demo of your lending platform in just 48 hours — before you invest a cent.
Book a Free Demo to see how our P2P Lending Software Solution can take you from idea to live platform in just 8 – 12 weeks.