Where you launch an RWA tokenization project now shapes almost everything else. It sets which law applies, who can buy your tokens, how long the review takes and what it costs to stay within the rules. Real World Asset (RWA) tokenization turns things like bonds, funds, real estate and gold into tokens on a blockchain. As of 1 October 2026, rwa.xyz tracks about $38.6 billion of these assets held in on-chain wallets, and the total keeps growing.
This guide ranks the top 10 countries to launch RWA tokenization in 2026. For each one you get the watchdog, the main laws, what is live there now, the pros and cons, and the kind of project it suits best. You also get a side by side table, the one test that sets your legal route, a quick way to pick your country and answers to the questions founders ask most.
In this guide:
- The 10 best countries for RWA tokenization, with the watchdog and laws for each.
- A side by side table of who can buy and what each country suits best.
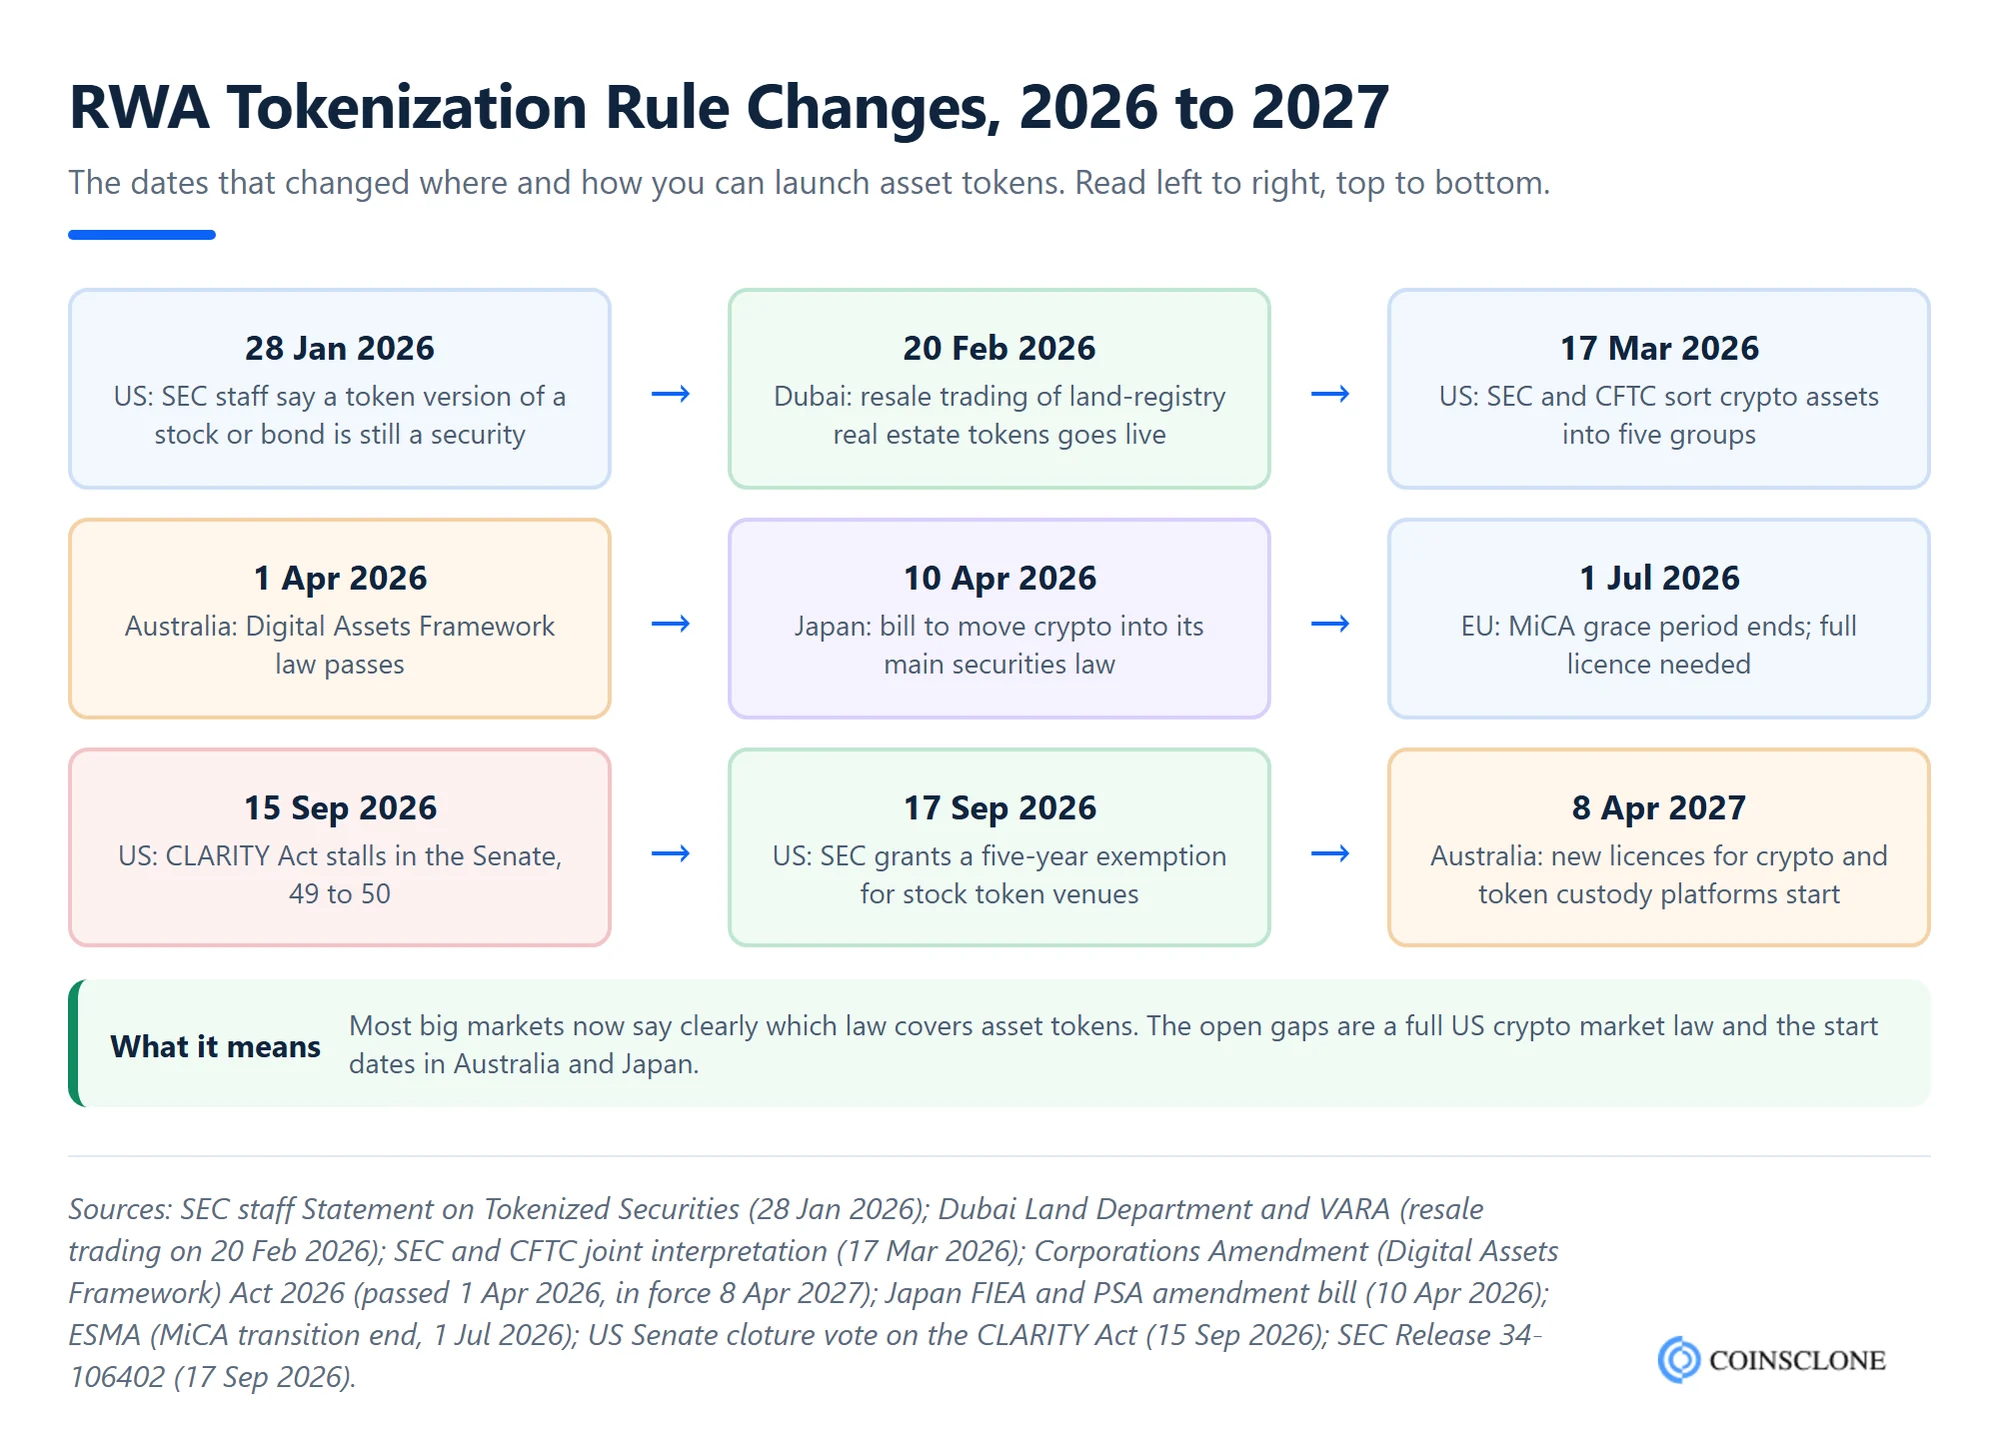
- The 2026 rule changes in the US, EU, UAE, Japan and Australia.
- A decision tree that matches your asset and your buyers to a country.
- How most cross-border RWA deals split the asset, the issuer and the platform across countries.
Top 10 Countries to Launch RWA Tokenization
Build, tokenize, and scale real-world assets — the smart way.
- RWA-Friendly Regulations:Jurisdictions with clear frameworks for asset tokenization.
- Investor Access: Countries with strong institutional & crypto-native capital flows.
- Infrastructure Ready:Mature banking, custody, and blockchain ecosystems.
- Tax & Compliance Edge:Crypto-friendly tax policies and streamlined licensing.
- Market Demand: High appetite for tokenized real estate, commodities, and securities.
Get a free strategy snapshot in 48 hours — discover where your RWA project will thrive before you commit capital.
Book a Free Consultation to explore the Top 10 Countries to Launch RWA Tokenization and take your idea from concept to compliant launch in weeks, not months.
Top 10 Countries to Launch RWA Tokenization in 2026
Each country below lets you tokenize real-world assets within the law, but each one takes its own path. Most treat a bond token or a fund share as a normal security, so the usual stock and bond rules apply. A few, such as Dubai, also have a crypto rulebook for asset-backed tokens. The table gives you the quick view, and the sections after it go country by country.
| Country | Main regulator | Law for asset tokens | Can retail investors buy? | Best for |
| Singapore | MAS | Securities and Futures Act | Mostly accredited and institutional | Bonds, funds, bank pilots |
| United States | SEC (plus CFTC and states) | Securities Act exemptions: Reg D, Reg S, Reg A+, Reg CF | Only through Reg A+ or Reg CF | Treasury funds, private credit |
| European Union | ESMA and national regulators | MiFID II and the DLT Pilot Regime (MiCA for non-security tokens) | Yes, with a prospectus | Cross-border offers in the EU |
| Switzerland | FINMA | DLT Act (ledger-based securities) | Yes, with a prospectus | High-value private assets |
| UAE | VARA, DFSA, FSRA, SCA | VARA rules for asset-referenced tokens; DIFC and ADGM securities rules | Yes for Dubai property tokens | Real estate, commodities |
| Hong Kong | SFC and HKMA | Securities and Futures Ordinance plus SFC tokenization circulars | Yes for SFC-approved fund tokens | Bonds, funds, stablecoin rails |
| Japan | FSA | Financial Instruments and Exchange Act | Yes | Retail property tokens |
| Australia | ASIC | Corporations Act; Digital Assets Framework Act 2026 | Yes, with a licence and disclosure | Funds, fixed income |
| Germany | BaFin | Electronic Securities Act (eWpG) | Yes, with a prospectus | Digital bonds and shares |
| France | AMF | PACTE law, DEEP ledger rules, MiFID II | Yes, with a prospectus | Funds, bank-issued bonds |
1. Singapore
Singapore is one of the top places to tokenize real-world assets. Its central bank and watchdog, the Monetary Authority of Singapore (MAS), treats a bond token or fund token the same way it treats the paper version. So the rules are clear from day one. MAS also runs some of the world’s largest bank-led token trials, which makes the city-state a strong base for asset-backed crypto token development.
Local banks and fund firms now issue and trade token products. Under Project Guardian, MAS has brought together more than 40 banks, fund firms, trade groups and policy bodies to test bond tokens, fund tokens and other products. In November 2025, MAS ran a live trial of bank-to-bank loans settled in central bank money on a ledger with DBS, OCBC and UOB. It also plans to trial MAS Bills as tokens.
Key Laws and Licences
- Securities and Futures Act (SFA): Bond, share and fund tokens are treated as capital markets products.
- Licences: A Capital Markets Services (CMS) licence to deal or run funds, and Recognised Market Operator status to run a trading venue.
- Payment Services Act: Covers payment tokens and stablecoins used to settle trades.
- Offshore-only firms: Since 30 June 2025, MAS will in most cases not license a firm that serves only clients abroad.
Strengths
- Clear rules let firms tokenize assets with legal confidence from the start.
- Strong links to global banks help with deals across borders and with reaching buyers.
- The rules cover real estate, funds, bonds and commodities, so many use cases fit.
Challenges
- Licence reviews take time, often six months or more, which can delay launch.
- Strict KYC, AML and report rules raise both legal and running costs.
- Most offers are open only to wealthy and professional buyers.
Best For: Fintech firms, fund houses and banks that want an Asian base with clear, tested rules.
2. United States
The United States is the largest market for RWA tokenization by value. US Treasury fund tokens alone hold about $14.7 billion on rwa.xyz, close to 40% of all RWA value held on-chain. The rules are still complex, but 2026 brought the clearest guidance yet.
US activity centres on Treasury funds, private credit, real estate and, more recently, stock tokens. Large fund firms now run on-chain money market funds, and traders use tokenized treasuries to park cash and back loans. In January 2026, SEC staff confirmed that a token version of a stock or bond is still a security. In September 2026, the SEC granted a five-year Innovation Exemption for venues that trade stock tokens on public blockchains.
Key Laws and Licences
- Securities and Exchange Commission (SEC): Most RWA tokens count as securities. You either register the offer or use a carve-out such as Reg D, Reg S, Reg A+ (up to $75 million a year) or Reg CF (up to $5 million).
- Commodity Futures Trading Commission (CFTC): Covers tokens and trades linked to gold, oil and other raw goods.
- State laws: Each state’s own investment and money transfer rules can also apply.
- Market law: The CLARITY Act stalled in the Senate in September 2026, so there is still no full crypto market law.
Strengths
- The deepest capital markets in the world and the largest pool of big-fund money.
- Custody, transfer agent and fintech services are in place and well tested.
- New SEC guidance in 2026 makes the path for stock and bond tokens much clearer.
Challenges
- Federal and state rules overlap, so you need a careful plan to comply.
- Most offers under Reg D are open only to wealthy, vetted buyers.
- Legal and running costs are high compared with smaller hubs.
Best For: Large platforms built around fund tokens, private credit and Treasury-backed assets.
3. Europe (EU)
Europe offers one market of 30 countries (the EU plus Iceland, Liechtenstein and Norway) with shared rules. That makes it a strong base for RWA projects that want to raise money across borders.
The key point is which law applies. Bond, share and fund tokens fall under MiFID II and the DLT Pilot Regime. Since 23 March 2023, that regime has let licensed venues trade and settle such tokens on a blockchain. Other asset-backed tokens that are not securities fall under MiCA, whose grace period ended on 1 July 2026. Firms across Europe now use these rules for the tokenization of real estate, bonds and funds.
Key Laws and Licences
- MiFID II and the Prospectus rules: Cover stock, bond and fund tokens, just like paper ones.
- DLT Pilot Regime: Lets licensed venues trade and settle these tokens on a blockchain, within size caps.
- Markets in Crypto-Assets (MiCA): Covers crypto tokens that are not stocks, bonds or funds, and the firms that serve them.
- AML rules: The EU Travel Rule applies to each crypto transfer, whatever the size.
Strengths
- One licence or approved prospectus can be passported across all 30 EEA markets.
- Rules put strong weight on buyer safety, which builds trust.
- Retail buyers can take part once you publish an approved prospectus.
Challenges
- Reviews can take longer because both local and EU rules apply.
- Tax on asset tokens still changes from country to country, so plan tax per market.
- The DLT Pilot Regime caps how large the token issues on a venue can be.
Best For: Licensed RWA platforms, banks and projects that target buyers across the EU.
4. Switzerland
Switzerland is one of the most crypto-friendly countries in the world, with strong blockchain laws and a long record in private banking. It offers legal certainty and trust, which makes it a top choice for high-value assets.
Swiss law has treated tokens as securities since the DLT Act took effect in 2021. Under it, “ledger-based securities” live only on a blockchain and still hold up in court. Firms have issued share, bond, real estate and private asset tokens. SIX, the Swiss stock exchange group, folded its SIX Digital Exchange (SDX) into its main exchange and post-trade units in 2025, so digital bonds now trade on SIX Swiss Exchange and settle on a ledger.
Key Laws and Licences
- Swiss DLT Act: Created ledger-based securities in 2021 and a new licence for DLT trading facilities.
- FINMA guidelines: Sort tokens into payment, utility and asset tokens, and asset tokens count as securities.
- Licensed venues: Trading needs a FINMA-licensed exchange or DLT trading facility.
Strengths
- Clear blockchain laws that have worked in practice for five years.
- High buyer trust and a strong private banking and wealth market.
- Asset tokens have full legal standing, which protects both issuers and buyers.
Challenges
- The home market is small, so most projects need a cross-border plan to grow.
- Setting up and running a licensed firm is costly, with high legal and staff bills.
- FINMA expects strong board control, audits and reports.
Best For: High-value assets, wealth managers and projects that put legal clarity first.
5. United Arab Emirates (UAE)
The UAE has moved faster than almost any other country on RWA tokenization. In its 2025 rulebook update, Dubai’s crypto watchdog (VARA) added a class for asset-referenced virtual assets (ARVAs). That gives asset-backed tokens their own licence path. The country has four watchdogs: VARA for Dubai, the DFSA in the DIFC, the FSRA in Abu Dhabi Global Market (ADGM) and the federal SCA.
Dubai real estate is the stand-out use case. The Dubai Land Department (DLD) runs a real estate tokenization project with VARA, the Dubai Future Foundation and the Central Bank of the UAE. Each token links to a title deed on the land register. The pilot drew more than AED 18.5 million from buyers of over 50 nationalities, and resale trading went live on 20 February 2026.
Key Laws and Licences
- VARA (Dubai): Issue rules for asset-referenced tokens, plus a separate sign-off for each issue.
- DFSA (DIFC) and FSRA (ADGM): Rules for stock, bond and fund tokens in the two finance free zones.
- DLD rules: Real estate tokens must link to a DLD title deed.
- Federal rules: The SCA and the Central Bank of the UAE cover the rest of the country.
Strengths
- Fast, firm-friendly licences and strong state support.
- A real, live real estate token market with resale trading.
- Low tax: company tax is 9% on profit above AED 375,000, with no income tax on people.
Challenges
- Rules are still being updated as the market grows, so plans must stay open to change.
- Each zone has its own watchdog, which adds work when you set up a project.
- Some legal and rules experts still have to come from abroad.
Best For: Real estate tokenization, gold and raw goods tokens, and projects that want to scale fast across the Gulf.
6. Hong Kong
Hong Kong is building a licensed gateway for RWA tokenization in Asia. It pairs a major finance hub with clear guidance from its two watchdogs, the Securities and Futures Commission (SFC) and the Hong Kong Monetary Authority (HKMA).
The government itself is a leading issuer. In November 2025, it priced about HK$10 billion of digital green bonds in four currencies, drawing over HK$130 billion of orders. It was the largest on-chain bond issue in the world to date. The HKMA’s Project Ensemble now tests bank deposit tokens as a way to pay for asset tokens. Read our full guide to RWA tokenization in Hong Kong for more detail.
Key Laws and Licences
- SFC token circulars (November 2023): Treat stock and bond tokens like normal ones and set rules for fund tokens.
- Virtual Asset Trading Platform (VATP) licence: Needed to run a crypto trading platform. The SFC listed 13 licensed platforms as of 29 May 2026.
- Stablecoins Ordinance: In force since 1 August 2025, for stablecoins used to pay for trades.
Strengths
- A trusted, stable finance hub with strong global links.
- Clear licence rules help firms plan launches with fewer legal unknowns.
- Retail buyers can hold fund tokens that the SFC has approved.
Challenges
- Most other stock and bond tokens go only to professional buyers.
- High standards for audits, reports and board control add time and cost.
- Legal, tech and rules costs can be heavy for small projects.
Best For: Bond and fund tokens, and projects that want links to both global and mainland Chinese money.
7. Japan
Japan offers a stable, steady market for RWA tokenization, with a strong focus on buyer safety. Since May 2020, its main securities law has named security tokens as their own type of security, so the rules are clear.
The market is growing fast. New token issues reached JPY165 billion in the year to March 2026, bringing the total to JPY333.3 billion, about double the year before, according to BOOSTRY’s market report. About 85% of the year’s new tokens were backed by real estate. The Osaka Digital Exchange runs START, a resale market where retail buyers can trade these tokens.
Key Laws and Licences
- Financial Instruments and Exchange Act (FIEA): Covers security tokens as “electronically recorded transferable rights”.
- Financial Services Agency (FSA): Licenses firms that issue, sell and trade these tokens.
- Payment Services Act (PSA): Covers crypto and stablecoins. A 2026 bill moves crypto into the main securities law, with the new system due in 2027.
Strengths
- Security tokens have a clear legal home in the main securities law.
- Large firms and regional banks now issue tokens, which builds trust.
- Retail buyers now hold real estate tokens, so there is real demand.
Challenges
- Reviews move slowly and with care.
- Rules leave little room for new or untested models.
- Most deals are in yen and in Japanese, which limits foreign reach.
Best For: Retail real estate tokens, company bonds and projects that value long-term calm.
8. Australia
Australia is a growing market for licensed RWA tokenization, backed by a mature finance system. Its focus on clear disclosure and buyer safety suits fund and bond tokens.
Most asset tokens there count as financial products. So the Corporations Act and the market watchdog, ASIC, set the rules. The Digital Assets Framework Act 2026 passed on 1 April 2026 and takes effect on 8 April 2027. It brings crypto platforms and token custody platforms under the licence system. The Reserve Bank’s Project Acacia has also tested how asset tokens could settle between banks.
Key Laws and Licences
- ASIC and the Corporations Act: Asset tokens that are financial products need an Australian Financial Services Licence (AFSL) and clear disclosure.
- Digital Assets Framework Act 2026: Licenses crypto and token custody platforms from 8 April 2027, with a six-month window to apply.
- AUSTRAC: AML sign-up for firms that swap or hold crypto.
Strengths
- Banks, fund firms and super funds are testing asset tokens.
- The new law gives a clear licence path for platforms.
- Strong buyer safety builds trust for long-term projects.
Challenges
- Detailed reviews can slow down your launch.
- The new platform rules only start in 2027, so some details are still settling.
- Ongoing audits and reports add to running costs.
Best For: Licensed RWA platforms, fund tokens and bond projects.
9. Germany
Germany stands out in Europe because token securities are written into its own law. Its Electronic Securities Act (eWpG) has let bonds exist only on a blockchain since June 2021, and a 2023 law extended this to shares.
Large issuers now use it. Siemens issued a EUR 60 million bond on a blockchain under the eWpG in February 2023, sold straight to buyers with no paper notes. The country also has the busiest crypto watchdog in the EU: BaFin holds 99 of the 364 MiCA crypto licences on the ESMA register.
Key Laws and Licences
- Electronic Securities Act (eWpG): Lets bonds, fund units and shares be issued as crypto securities.
- BaFin licences: You need a licence under the German Banking Act (KWG) to keep a crypto securities register.
- MiFID II and MiCA: EU rules for stocks, bonds and crypto still apply.
Strengths
- Asset tokens have full legal standing under German law.
- A large, stable economy supports buyer trust.
- Banks and big firms now issue and buy bond tokens.
Challenges
- High standards for reports, audits and board control add work.
- Issuing asset tokens needs detailed legal papers, which can slow launch.
- Smaller teams may need outside help to meet the rules.
Best For: Bond tokens, share tokens and large RWA issues for big funds.
10. France
France was one of the first EU countries to write blockchain into finance law. That makes it a forward-looking market for RWA tokenization that balances new ideas with firm rules.
Since 2017, French law has let unlisted shares and bonds be kept on a shared ledger. The PACTE law of 2019 then set up rules for token offers and crypto firms. Big French banks lead the way: Societe Generale’s crypto arm, SG-FORGE, has issued bonds on public blockchains since 2020. France also holds the second-highest number of MiCA crypto licences in the EU, with 36 on the ESMA register.
Key Laws and Licences
- DEEP rules (2017): Let unlisted shares and bonds be kept on a blockchain.
- PACTE law (2019): Set up rules for token offers, with an optional AMF stamp of approval.
- MiCA licence: Crypto firms now need a full MiCA licence from the AMF. The old French sign-up (PSAN) ended with the grace period on 1 July 2026.
Strengths
- Clear French and EU rules give legal certainty to issuers and buyers.
- Big banks take part, which speeds up real use cases.
- A French base gives easy access to the wider EU market.
Challenges
- Licence reviews are detailed and can delay launch.
- Ongoing audits and reports add to running costs, so budget for them early.
- Retail buyers are wary of new products, so big funds tend to move first.
Best For: Fund tokens, bank-issued bonds and EU-compliant RWA platforms.
Other RWA Tokenization Hubs Worth a Look
The 10 countries above cover most live RWA activity, but a few smaller hubs often play a part in a deal:
- Luxembourg: The EU’s main fund centre. Its Blockchain Law IV, passed in December 2024, lets a “control agent” keep the records for token securities, which suits fund tokens.
- Liechtenstein: Its Blockchain Act has covered token rights since 2020, and it now also applies MiCA. It is small, but quick for well-prepared firms.
- United Kingdom: The Digital Securities Sandbox lets firms test token trading and settlement under lighter rules. Its new crypto licence system goes live on 25 October 2027.
- Cayman Islands and BVI: Not places to sell your tokens, but common homes for the fund or special purpose vehicle (SPV) that holds the asset.
Why Country Selection Matters for RWA Tokenization
Choosing the right country is one of the biggest calls you will make when you launch an RWA tokenization project. It decides:
- Legal risk: Clear laws mean your tokens hold up in court and your buyers are safe.
- Buyer reach: Your home country decides whether you can sell to retail buyers, big funds or global money.
- Time to market: Clear review steps help projects go live without long delays.
- Cost: Countries differ in how many rules they set, which drives setup and running costs.
- Growth: Rules that allow offers abroad make it easier to grow past your home market.
Securities Law or Crypto Law? The Rule That Decides Your Route
Before you compare countries, check what your token really is. In almost each country on this list, a token that gives a share of profit, interest or ownership in an asset counts as a security. That means normal stock and bond law applies, whatever the tech.
So a bond token in Germany follows the eWpG and MiFID II, not MiCA. A fund token in Singapore follows the SFA, and a Treasury fund token in the US follows SEC rules. Crypto laws such as MiCA or VARA’s rules mainly matter for tokens that are not securities, such as some gold-backed tokens, and for the platforms that trade them.
This one test shapes your licence, your buyer rules and your launch date. Settle it with a local lawyer before you write a line of code.
How to Choose the Right Country for Your RWA Tokenization Project
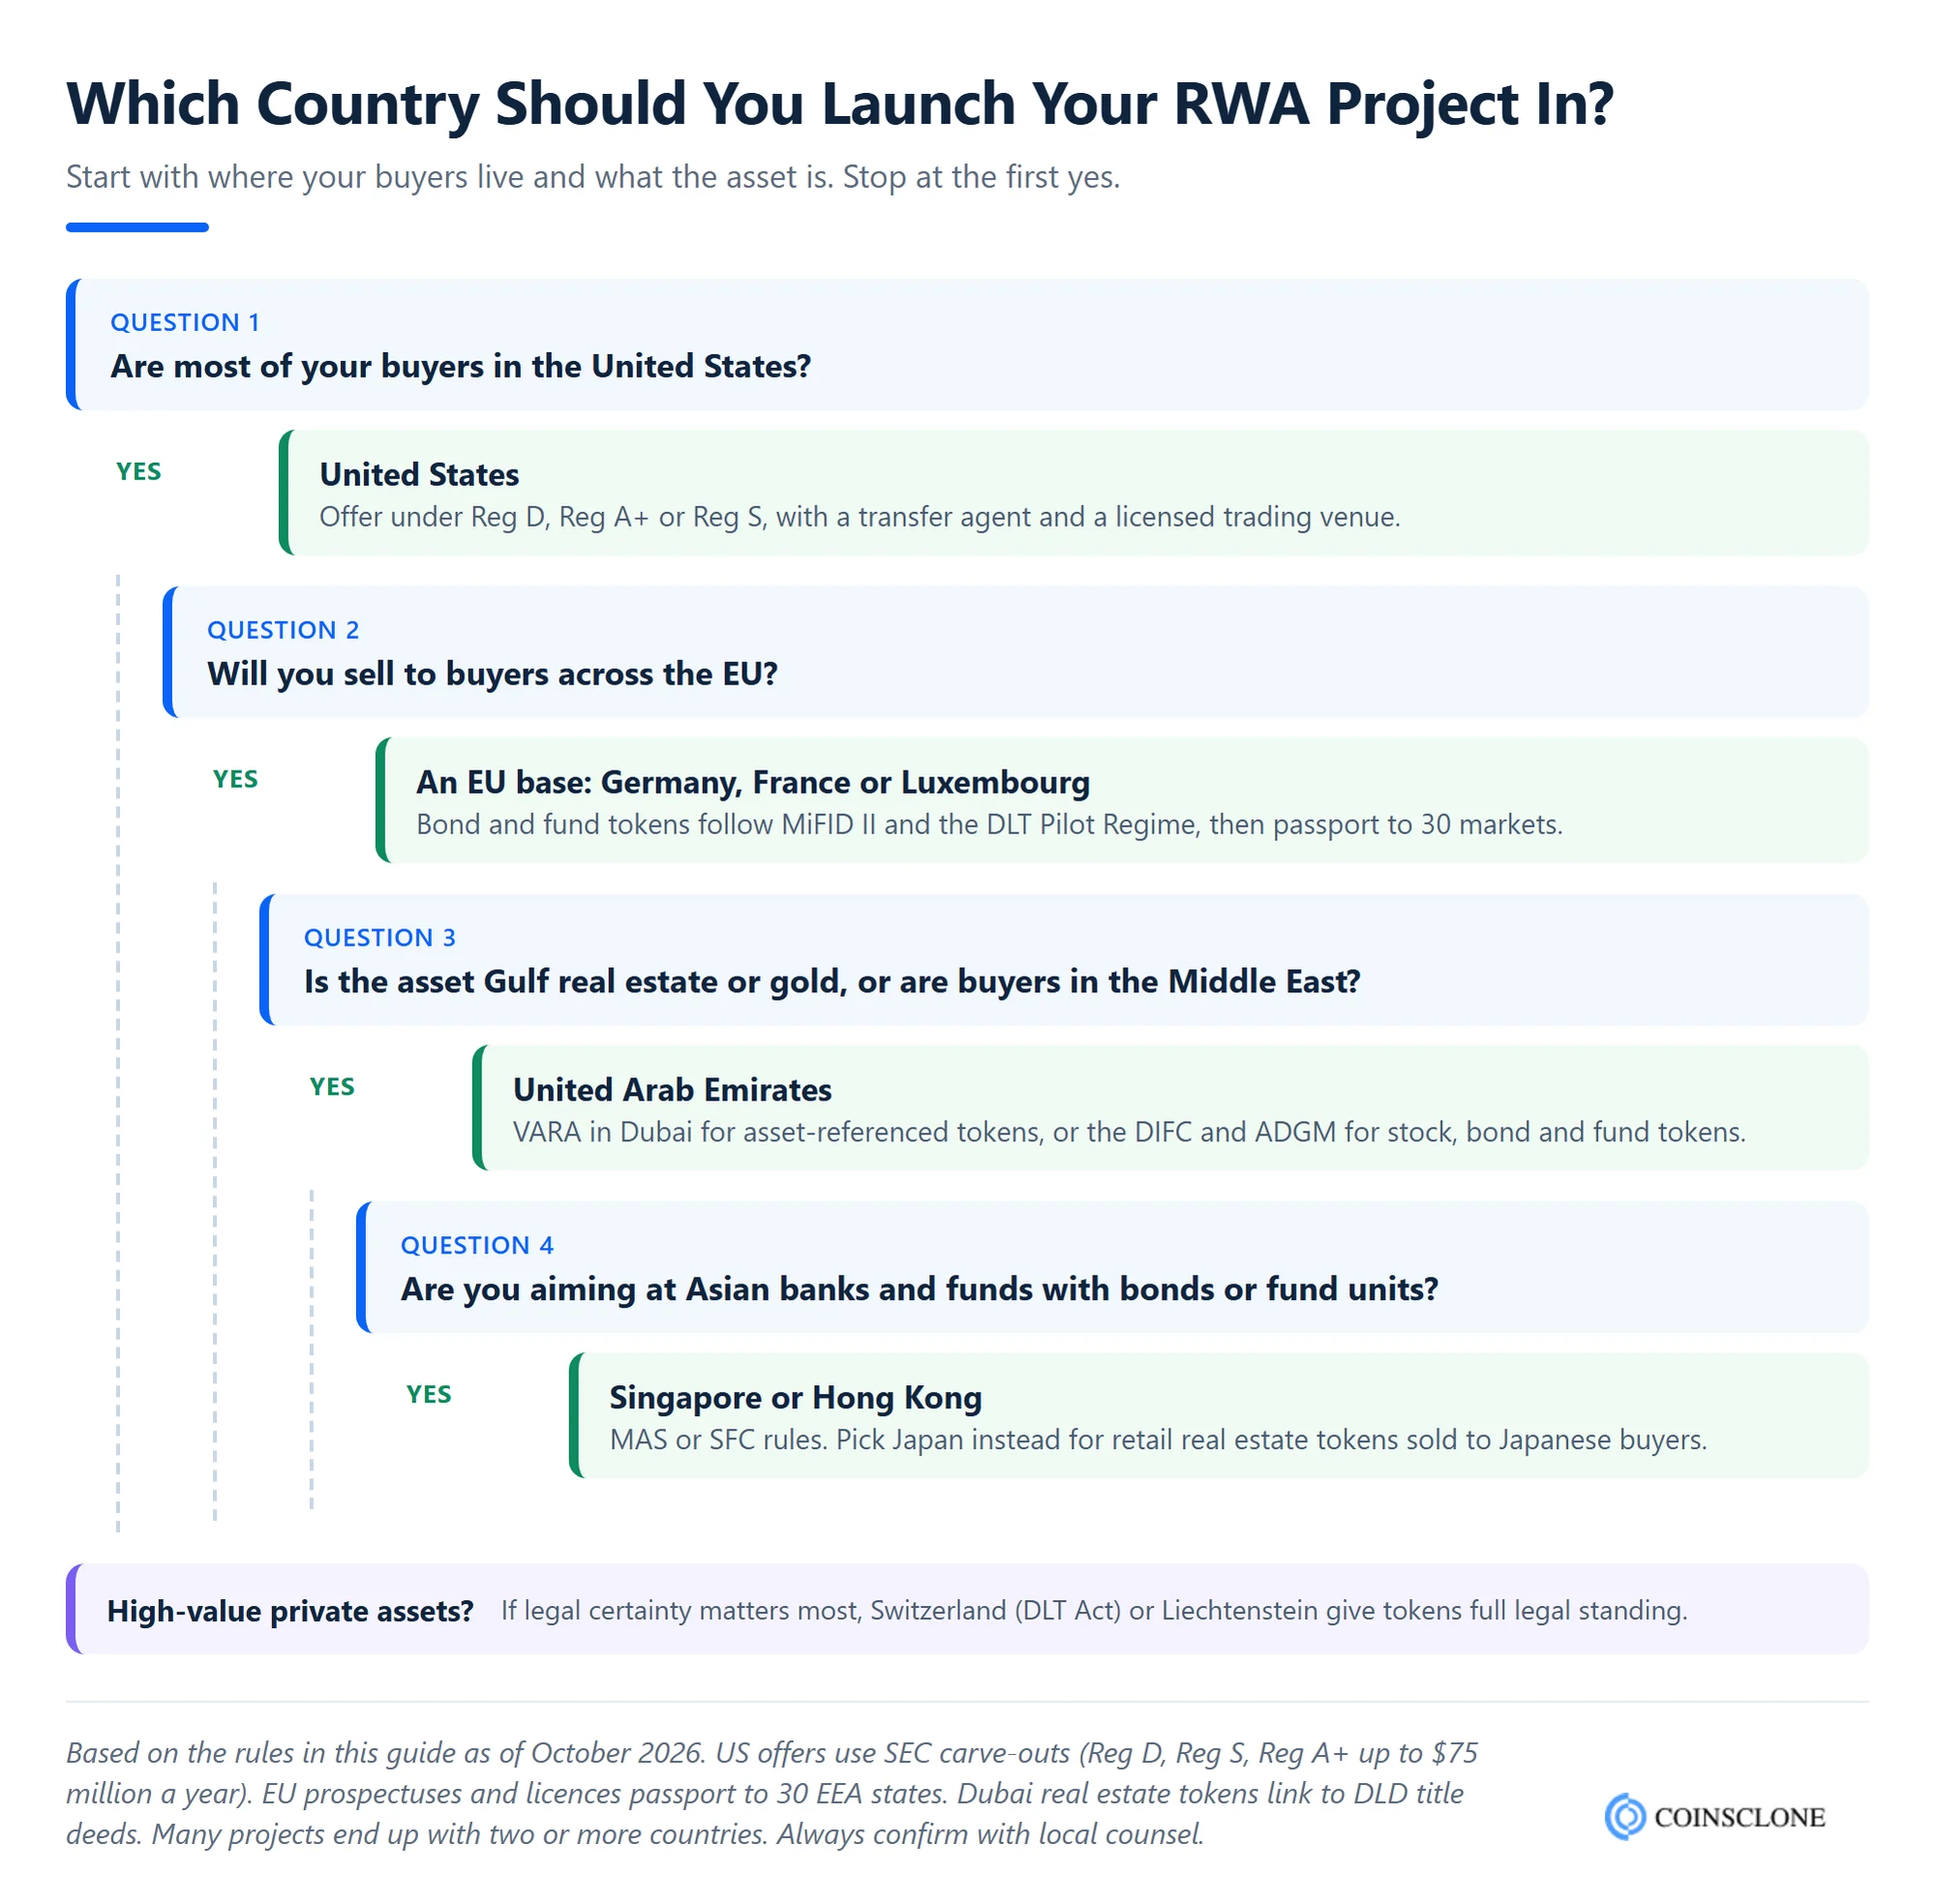
Choosing the right country is just as important as choosing the right technology. Here are the key factors to weigh.
Clear Rules: Look for countries where asset tokens have a clear legal home. Some, like Switzerland and Germany, wrote them into law. Others, like Singapore and the US, apply their normal stock and bond rules.
Asset Type: Each country suits some assets better than others. Dubai and Japan lead for real estate tokens. The US and Singapore lead for Treasury funds and bonds, while Luxembourg and France are strong for funds.
Target Buyers: Decide whether you want retail users, big funds or global money. Rules on who can buy change a lot from place to place, and many offers are open only to wealthy, vetted buyers.
Running Costs: Some countries offer speed and lighter rules, while others ask for more checks. Weigh cost against the trust a strong watchdog brings.
Market Reach: If you plan to grow abroad, choose a country whose licence works in other markets too, such as an EU state with passporting. Start with one market, then add more.
How Cross-Border RWA Projects Are Usually Structured
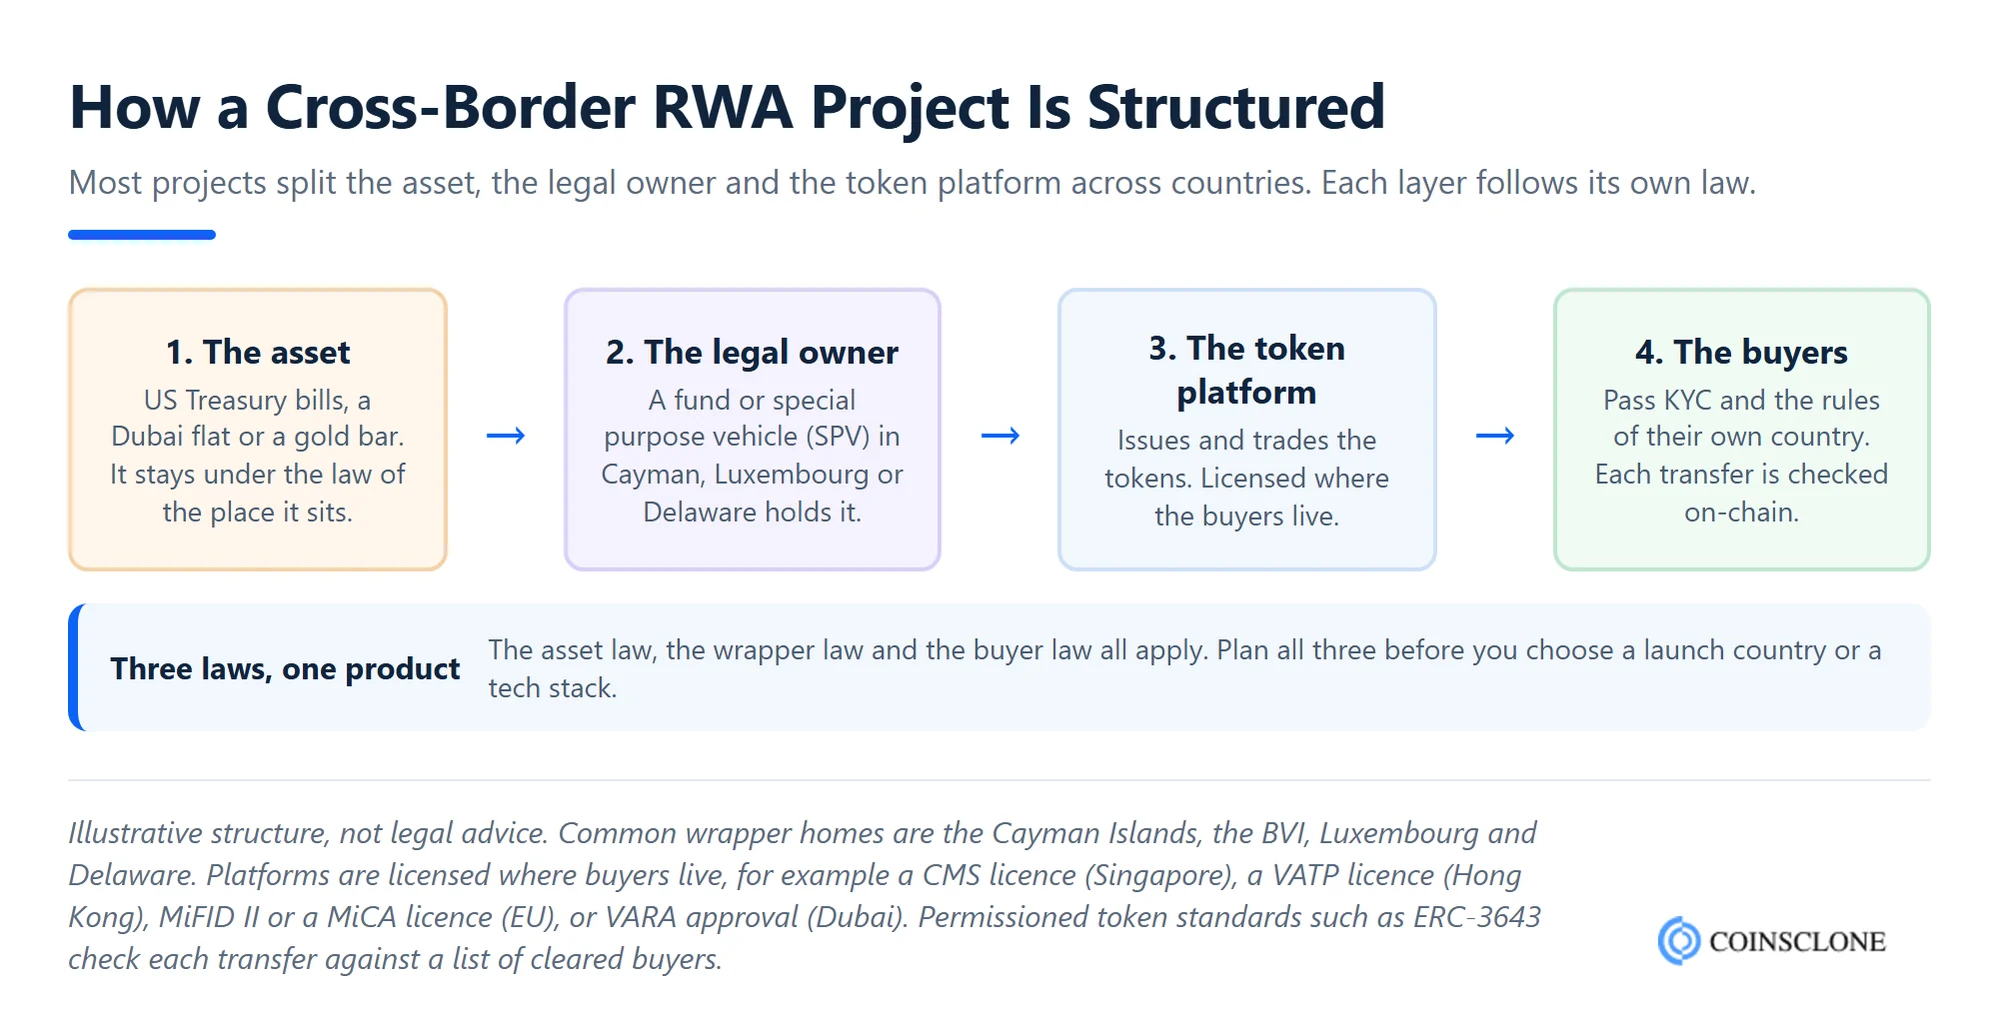
Most serious projects use more than one country. The asset sits in one place, a legal wrapper holds it in another, and the platform gets licensed where the buyers live. For example, a fund may hold US Treasury bills through a Cayman or Luxembourg vehicle, while a Singapore or EU platform sells the tokens.
This split lets you pick the best law for each layer. It also means each layer must pass its own checks, so plan the structure before you pick a tech stack.
Business Benefits of Tokenizing Real-World Assets
Real World Asset tokenization is quickly changing how firms raise money with physical assets. Here are the main benefits, whichever country you choose.
Liquidity
In old-style markets, costly assets like real estate, art or private equity can be locked up for years. Tokenization turns these assets into tokens that can be traded on a blockchain. That can turn hard-to-sell assets into ones that trade faster, as long as a licensed market exists for them.
Fractional Ownership
Tokenization lets you split one asset into many small pieces. Even high-value assets come within reach of a wider group of buyers. Instead of asking for a check worth millions, you can sell small slices and widen your buyer base.
Global Accessibility
Once assets are tokenized, buyers from many countries can take part, within each country’s rules. A builder in the UAE can raise money from Singapore, London or Mumbai, so it relies less on local money.
Transparency
A blockchain ledger makes each transfer easy to check. For firms, this gives clear records of who owns what, who paid and which rules were met. It cuts disputes and fraud risk, builds buyer trust and makes audits simpler.
Cost Efficiency
From lawyers to brokers, old-style asset deals pass through many middlemen, and each adds cost and time. Smart contracts run many of these steps on their own, cut out some middlemen and speed up settlement.
24/7 Market Access
Old-style markets open at fixed hours and can take a day or more to settle trades. Asset tokens can move at any hour, on any day. Dubai’s real estate tokens, for example, trade around the clock on a licensed app.
With these benefits in mind, see our complete guide to Real World Asset Tokenization for how the process works from start to finish.
Where to Professionally Tokenize Real World Assets?
Tokenizing real-world assets needs a secure blockchain system, a sound legal setup, audited smart contracts and strong security. The right build partner helps your RWA project grow, stay within the rules and keep the trust of buyers.
Coinsclone is a professional Asset Tokenization Platform Development Company that helps firms tokenize real-world assets. Since 2018, we have delivered more than 350 platforms for over 200 clients across 20 industries. Whether you are tokenizing real estate, gold, funds or bonds, we build secure token platforms that grow with your business.
For each launch country, we build the rules your lawyers set into the platform itself: buyer checks, transfer limits by country and the reports each watchdog expects. See our RWA tokenization platform development guide for the build process, features and timeline.
Top 10 Countries to Launch RWA Tokenization
Build, tokenize, and scale real-world assets — the smart way.
- RWA-Friendly Regulations:Jurisdictions with clear frameworks for asset tokenization.
- Investor Access: Countries with strong institutional & crypto-native capital flows.
- Infrastructure Ready:Mature banking, custody, and blockchain ecosystems.
- Tax & Compliance Edge:Crypto-friendly tax policies and streamlined licensing.
- Market Demand: High appetite for tokenized real estate, commodities, and securities.
Get a free strategy snapshot in 48 hours — discover where your RWA project will thrive before you commit capital.
Book a Free Consultation to explore the Top 10 Countries to Launch RWA Tokenization and take your idea from concept to compliant launch in weeks, not months.
Frequently Asked Questions
Which country is best for real world asset tokenization?
There is no single best country. It depends on your asset and your buyers. Singapore and Hong Kong lead in Asia for bonds and funds. The US leads for Treasury fund tokens and private credit. The UAE leads for real estate. Switzerland and Germany give the firmest legal footing, and an EU base lets you reach 30 markets.
Which countries give security tokens full legal standing?
Switzerland (DLT Act, 2021), Germany (eWpG, 2021), France (DEEP rules, 2017), Luxembourg (Blockchain Laws, latest in 2024) and Japan (FIEA, 2020) have laws written for stocks and bonds on a blockchain. Singapore, Hong Kong and the US apply their normal rules, so a token there has the same legal standing as a paper share or bond.
Do I need a licence to tokenize real-world assets?
In most cases, yes. If your token is a security, you need to register the offer or use a carve-out. Anyone who sells, trades or holds the tokens for clients also needs a licence. The exact licence depends on the country, such as a CMS licence in Singapore, an AFSL in Australia or VARA sign-off in Dubai.
How do MAS rules apply to RWA tokenization?
MAS treats a bond, share or fund token just like the paper version under the Securities and Futures Act. Offers need a prospectus or a carve-out, and firms that deal, run funds or run a trading venue need the matching licence. Payment tokens used to settle trades fall under the Payment Services Act.
How do cross-border distribution rules apply to tokenized offerings?
A token can move anywhere, but the rules follow the buyer. You must meet the rules of each country where you sell, not just your home country. Many platforms block some regions and keep lists of cleared buyers, so they sell only where they are allowed. An EU prospectus or licence can be passported across the 30 EEA markets.
How long does it take to launch an RWA tokenization project?
Legal setup often takes a few months. Licence reviews tend to take three to six months in hubs like Switzerland, Luxembourg and the Dubai and Abu Dhabi free zones, and six months or more in Singapore. US private offers under Reg D can move faster because they do not need an SEC review before launch. The platform build can run alongside the legal work.