Blockchain in finance has moved past the pilot stage. Banks now settle billions of dollars a day on shared ledgers, asset managers sell Treasury funds as tokens, and stablecoins hold over $310 billion. This guide shows how blockchain works in finance, where it is live today, and what it costs to build on.
You will get a plain explanation, ten use cases with real names and numbers, the main types of blockchain banks use, and the risks that still slow things down. If you plan to build a finance product, you will also see the cost drivers and the build times we quote.
In this guide:
- What blockchain in finance means, in plain words
- 10 use cases, from cross-border payments to tokenized funds, with live examples
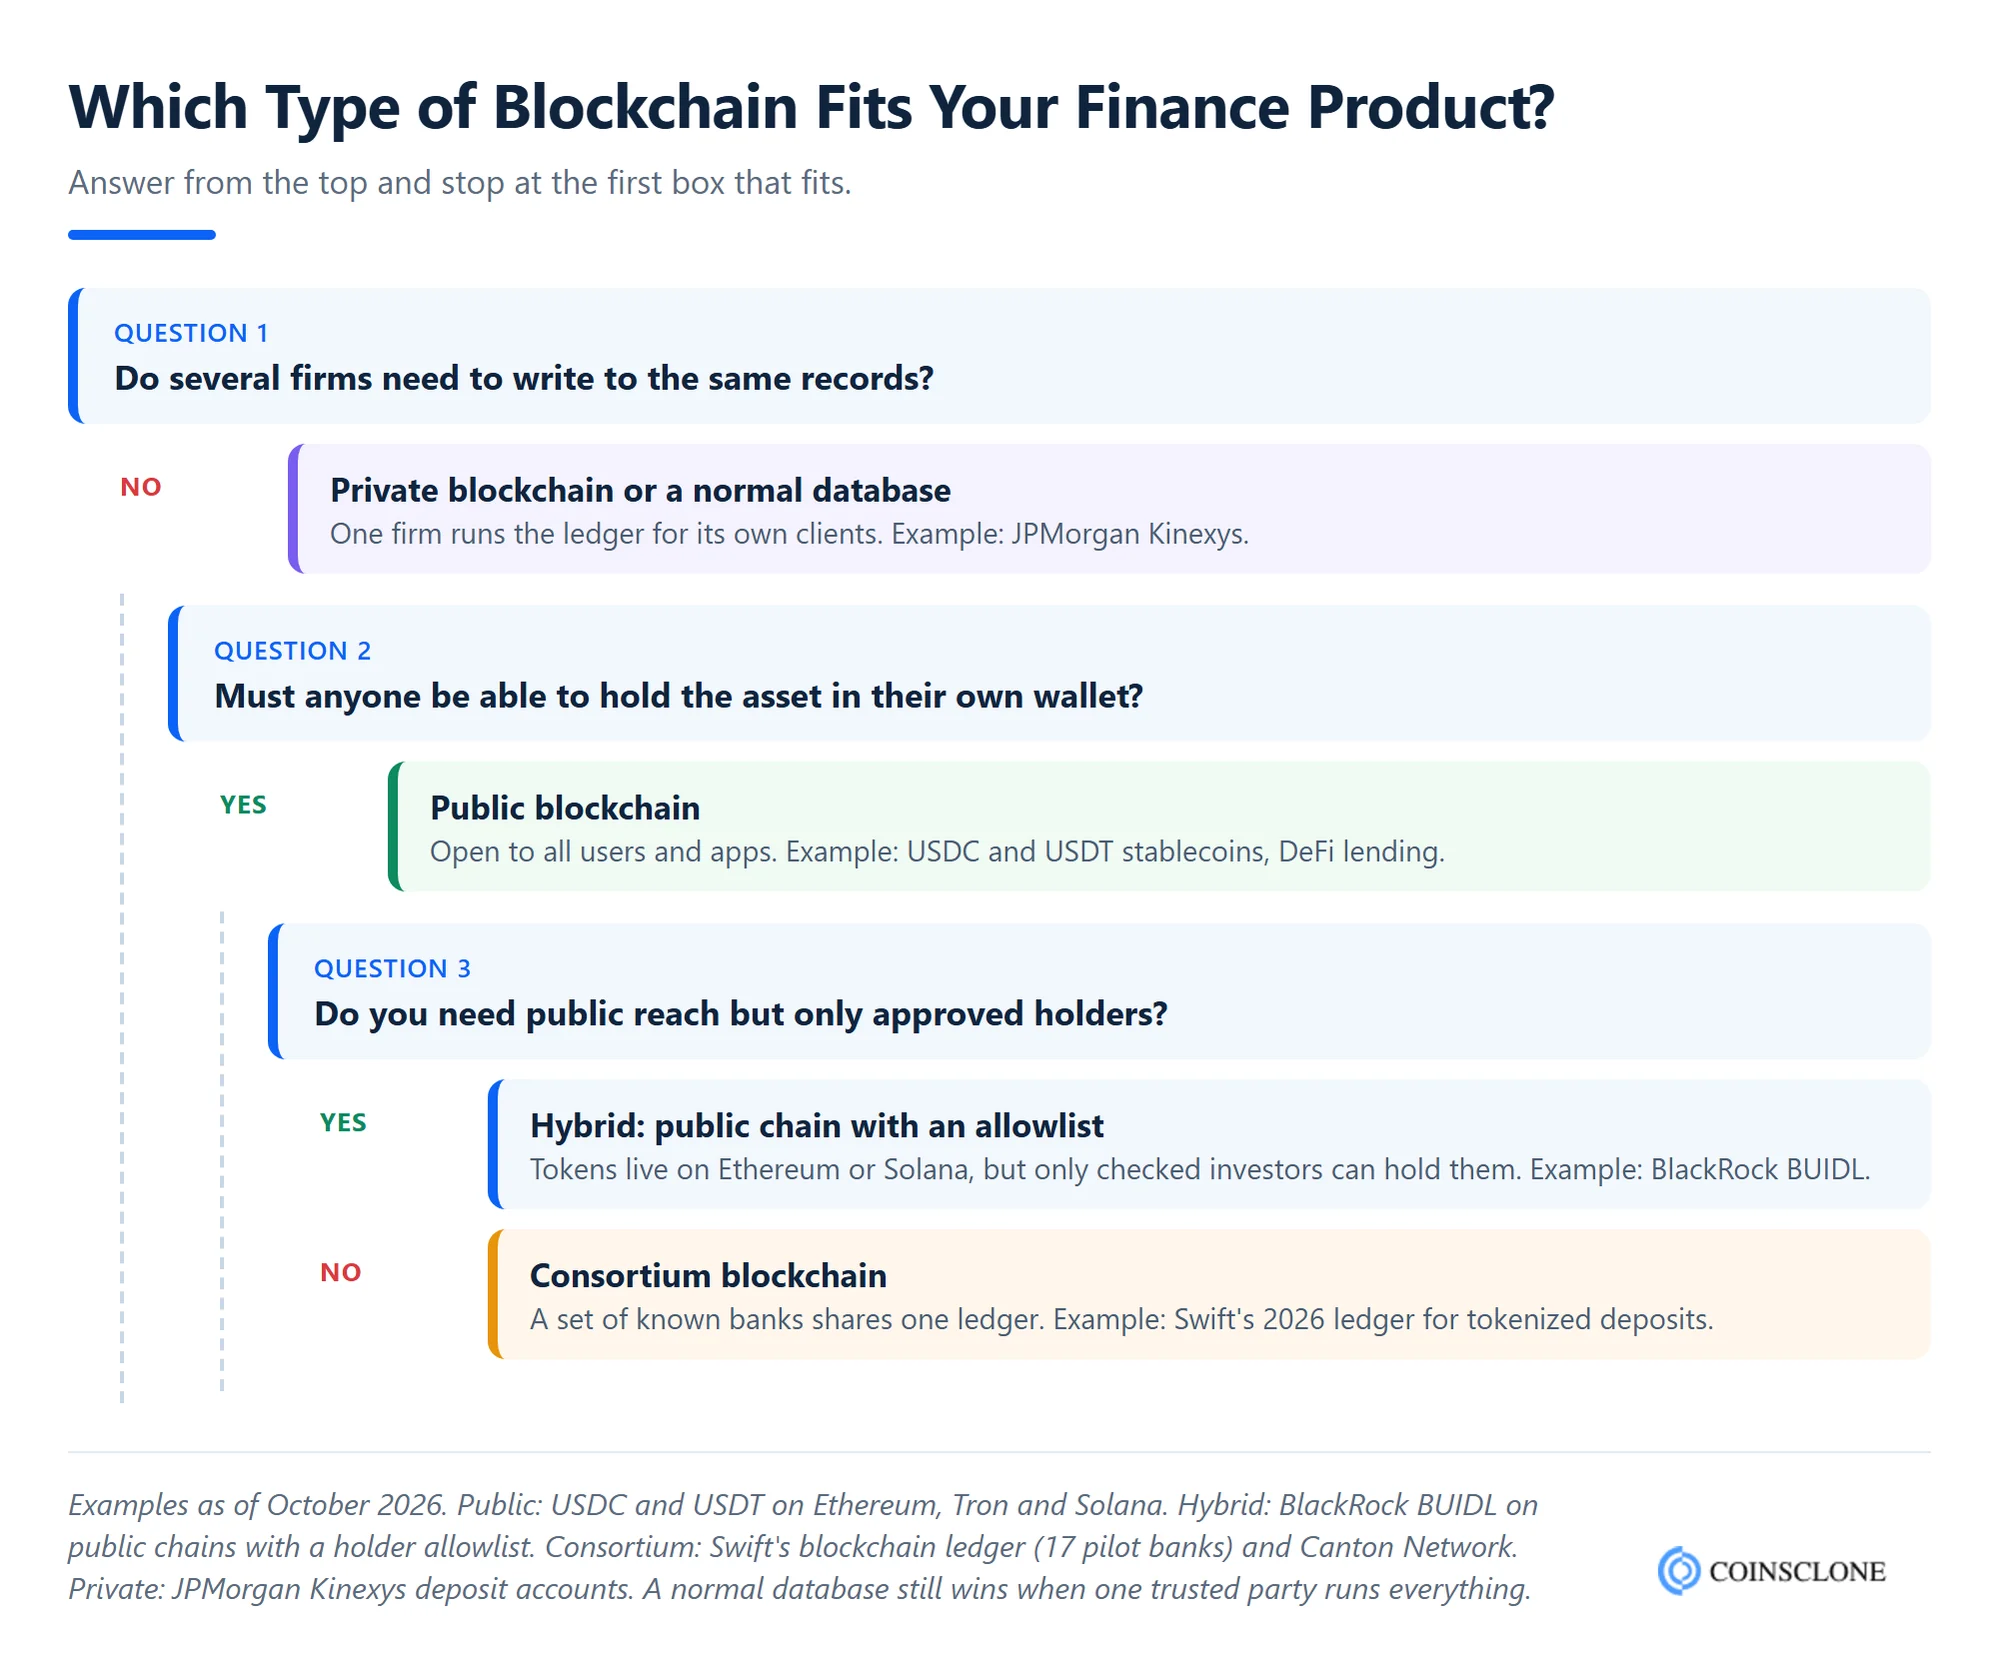
- Which type of blockchain fits a finance product, with a decision tree
- The real risks: hacks, rules, speed and old bank systems
- What it costs and how long it takes to build a blockchain finance app
Blockchain in Finance Explained
A blockchain is a shared record book. Many computers keep the same copy, and new entries are added in blocks that link to the ones before. Once an entry is in, no single person can quietly change it. Everyone who uses the ledger sees the same history.
In finance, that record book holds money and assets. Think of a payment, a loan, a bond or a share in a fund. Today, each bank keeps its own records and then checks them against other banks. That checking takes days and costs money. With a blockchain, the parties work from one record, so the asset and the payment can move together in seconds.
The scale in October 2026 shows this is real, not hype:
- Stablecoins: about $313 billion in dollar tokens, led by USDT ($184 billion) and USDC ($74 billion), per DefiLlama’s stablecoin data.
- Bank ledgers: JPMorgan’s Kinexys has handled over $4 trillion since launch and now averages over $7 billion a day, per JPMorgan’s June 2026 release.
- Tokenized assets: about $38.6 billion in real-world assets such as Treasury funds and private credit, per rwa.xyz.
- DeFi apps: about $95 billion locked in lending, trading and other apps, per DefiLlama.
Why the Financial Sector Needs Blockchain
Money moves through many hands. Each bank, broker and payment firm keeps its own books, so every step needs checks, fees and waiting time. Blockchain tackles those pain points directly.
- Fewer records to match: All parties share one ledger that cannot be quietly edited. This cuts the risk of data breaches, fraud and costly errors.
- Faster, cheaper work: Smart contracts handle steps that staff once did by hand, so payments and trades clear sooner and cost less.
- A clear audit trail: Every entry has a time stamp and a full history. That builds trust between firms that do not know each other well.
- Easier compliance: Records stay full and easy to check. That helps with KYC (Know Your Customer) and AML (Anti-Money Laundering) rules.
So the need to develop blockchain applications in finance keeps growing. Its shared, tamper-proof records have proven useful against fraud and forged data. As a result, more banks, fintechs and asset managers are adding it to stay ahead.
Benefits of Blockchain in Finance
Having seen the demand, let’s look at the main benefits that blockchain brings to finance.
Enhanced Security
The first big plus is safety. Each entry is signed with cryptography and linked to the entries before it. So changing one old record would mean changing every record after it, on most copies of the ledger at once. That makes fraud and quiet edits very hard. However, the code and the keys around the ledger still need guarding, as the risks section below shows.
Increased Transparency
Everyone with access sees the same ledger. Buyers and sellers can check a payment or a trade as it happens, rather than wait for statements. This builds trust between parties and makes disputes rarer.
Reduced Transaction Costs
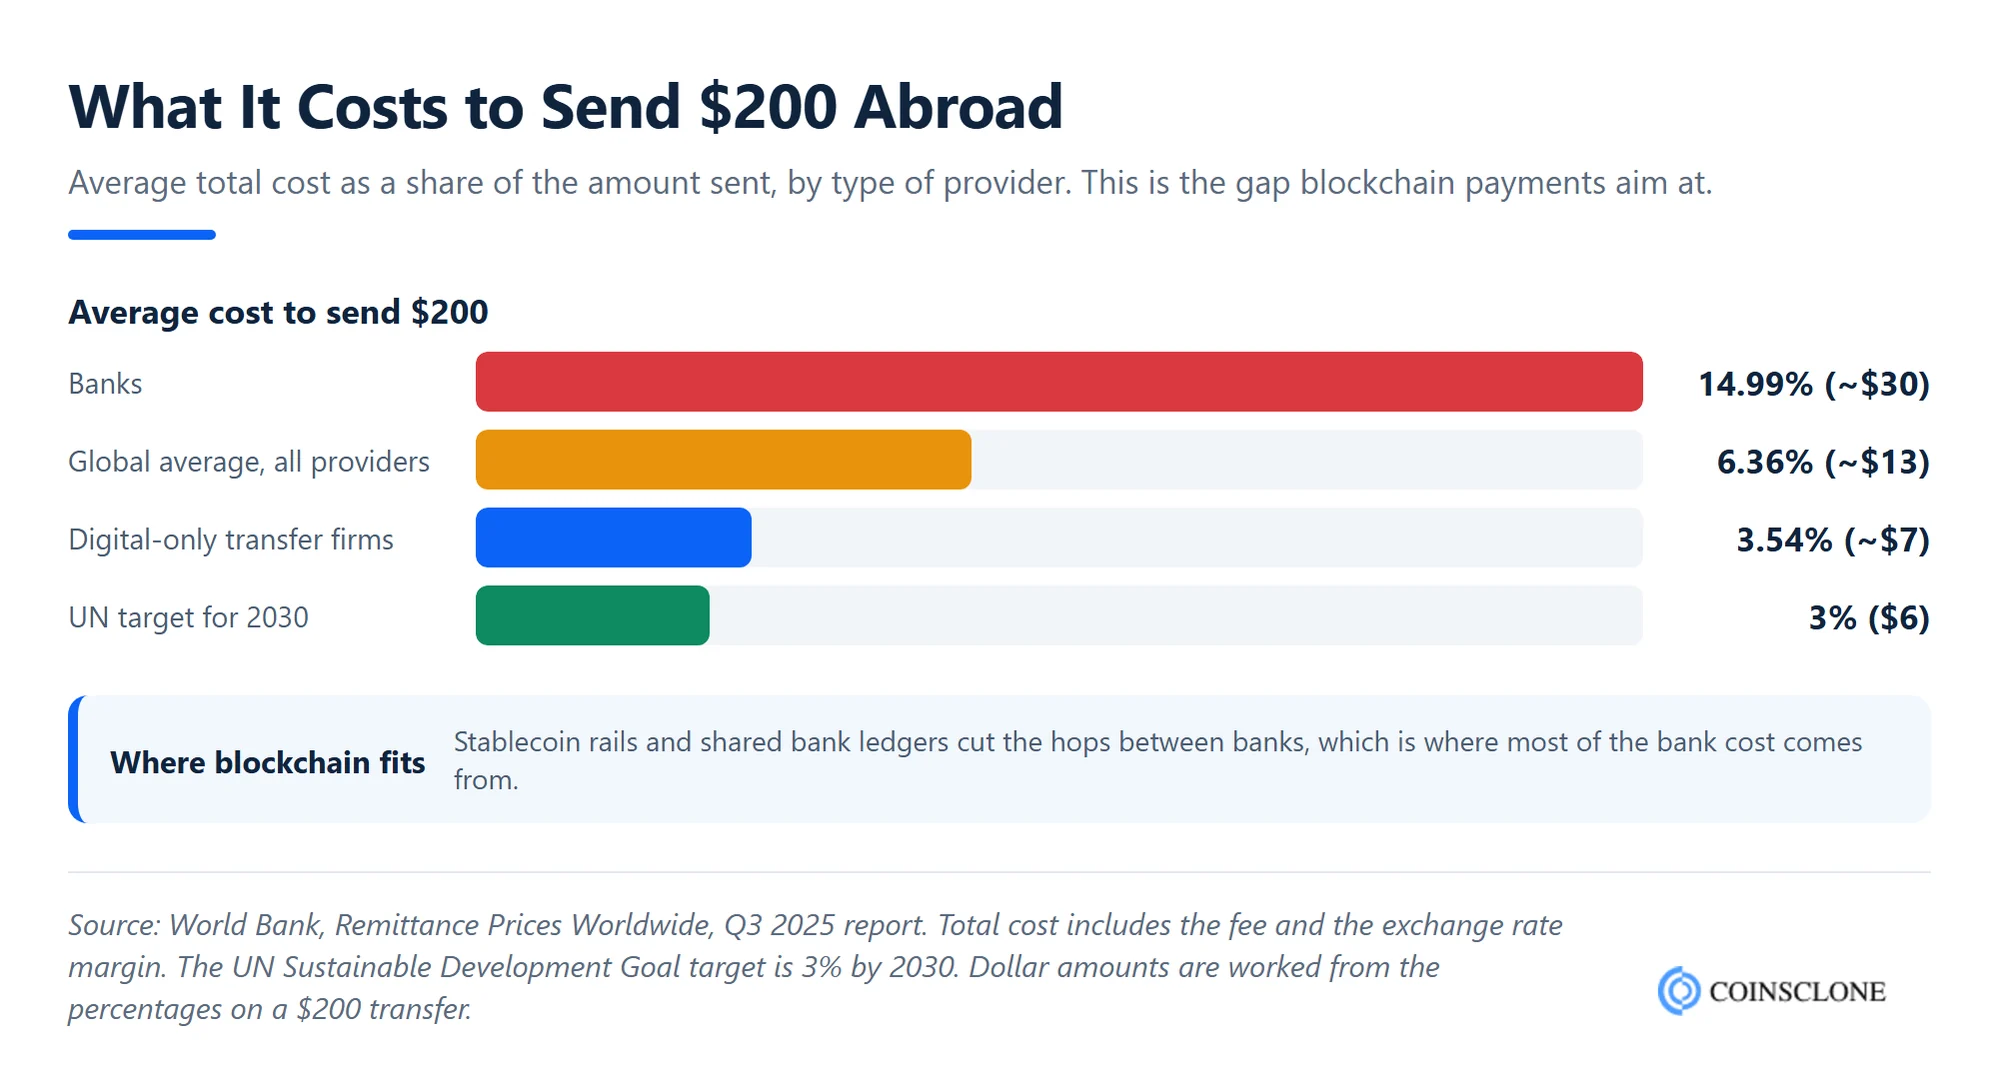
Old-style payments pass through several middlemen, such as banks and card firms, and each one takes a fee. A shared ledger removes some of those hops. That matters most for cross-border payments, where banks still charge about 15% to send $200, according to the World Bank.
Faster Transaction Times
A bank transfer abroad can take one to three days, and it stops at weekends. Blockchain payments settle in seconds or minutes, any hour of any day. Faster settlement frees up cash that would otherwise sit idle in transit.
Less Manual Work With Smart Contracts
Smart contracts are small programs that run by themselves when set terms are met. For example, a contract can release a loan payment when the paperwork is signed. This cuts manual work, delays and human error.
High Financial Inclusion
About one in five adults still has no account at a bank or mobile money service, according to the World Bank’s Global Findex 2025. With only a phone and an internet link, people can hold stablecoins, send money home and save in a digital wallet. This opens basic services to people that banks have long left out.
Sounds useful, right? If you are thinking of building a blockchain product for your business, read on to see where it fits in finance.
Use Cases of Blockchain in Finance
To see blockchain at work, check out these ten use cases of blockchain in finance, each with a live example.
1. Cross-Border Payments
Cross-border payments are the biggest use case. Today, a payment abroad hops through one or more middle banks, and each takes a fee and some time. On a blockchain, value moves straight from sender to receiver in minutes. Businesses use stablecoins such as USDC, while banks now use shared ledgers.
Real case: Swift opened its own blockchain ledger on 9 July 2026. Then 17 banks got ready to test bank deposits as tokens on it, such as Citi, HSBC, DBS and BNP Paribas. The chart below shows why the race matters.
If you want to accept or send stablecoins, a crypto payment gateway is the usual starting point.
2. Trade Finance
Trade finance runs on paper: letters of credit, bills of lading and invoices that pass between banks, shippers and buyers. A single deal can take weeks. Blockchain puts these papers on one shared ledger, so every party sees the same version. As a result, there is less paperwork, faster payment and less room for forged documents.
Real case: Banks and trade platforms now test digital bills of lading on shared ledgers. However, early bank groups such as we.trade and Contour closed after struggling to get enough users, which is a lesson in why network size matters.
3. Smart Contracts
Smart contracts are self-running programs on a blockchain. They act on their own when set terms are met. In finance, they pay out loans, settle insurance claims, handle collateral and run trading rules. Because the code runs the same way every time, it cuts errors and manual steps.
Real case: Every DeFi lending app runs on smart contracts.
4. Digital Identity Verification
Blockchain can store proof that a customer passed identity checks, without passing the raw papers around. A bank checks a user once, then other services can trust that check. This cuts onboarding time and keeps personal data safer. It also helps firms meet KYC and AML rules with less repeat work.
5. Asset Tokenization
Asset tokenization turns a real asset, such as a bond, a fund share or a building, into a token on a blockchain. The token stands for ownership and can be traded online. It lets people own a small part, so a buyer can get a slice of a costly asset. It also lets trades settle any time, not only in market hours.
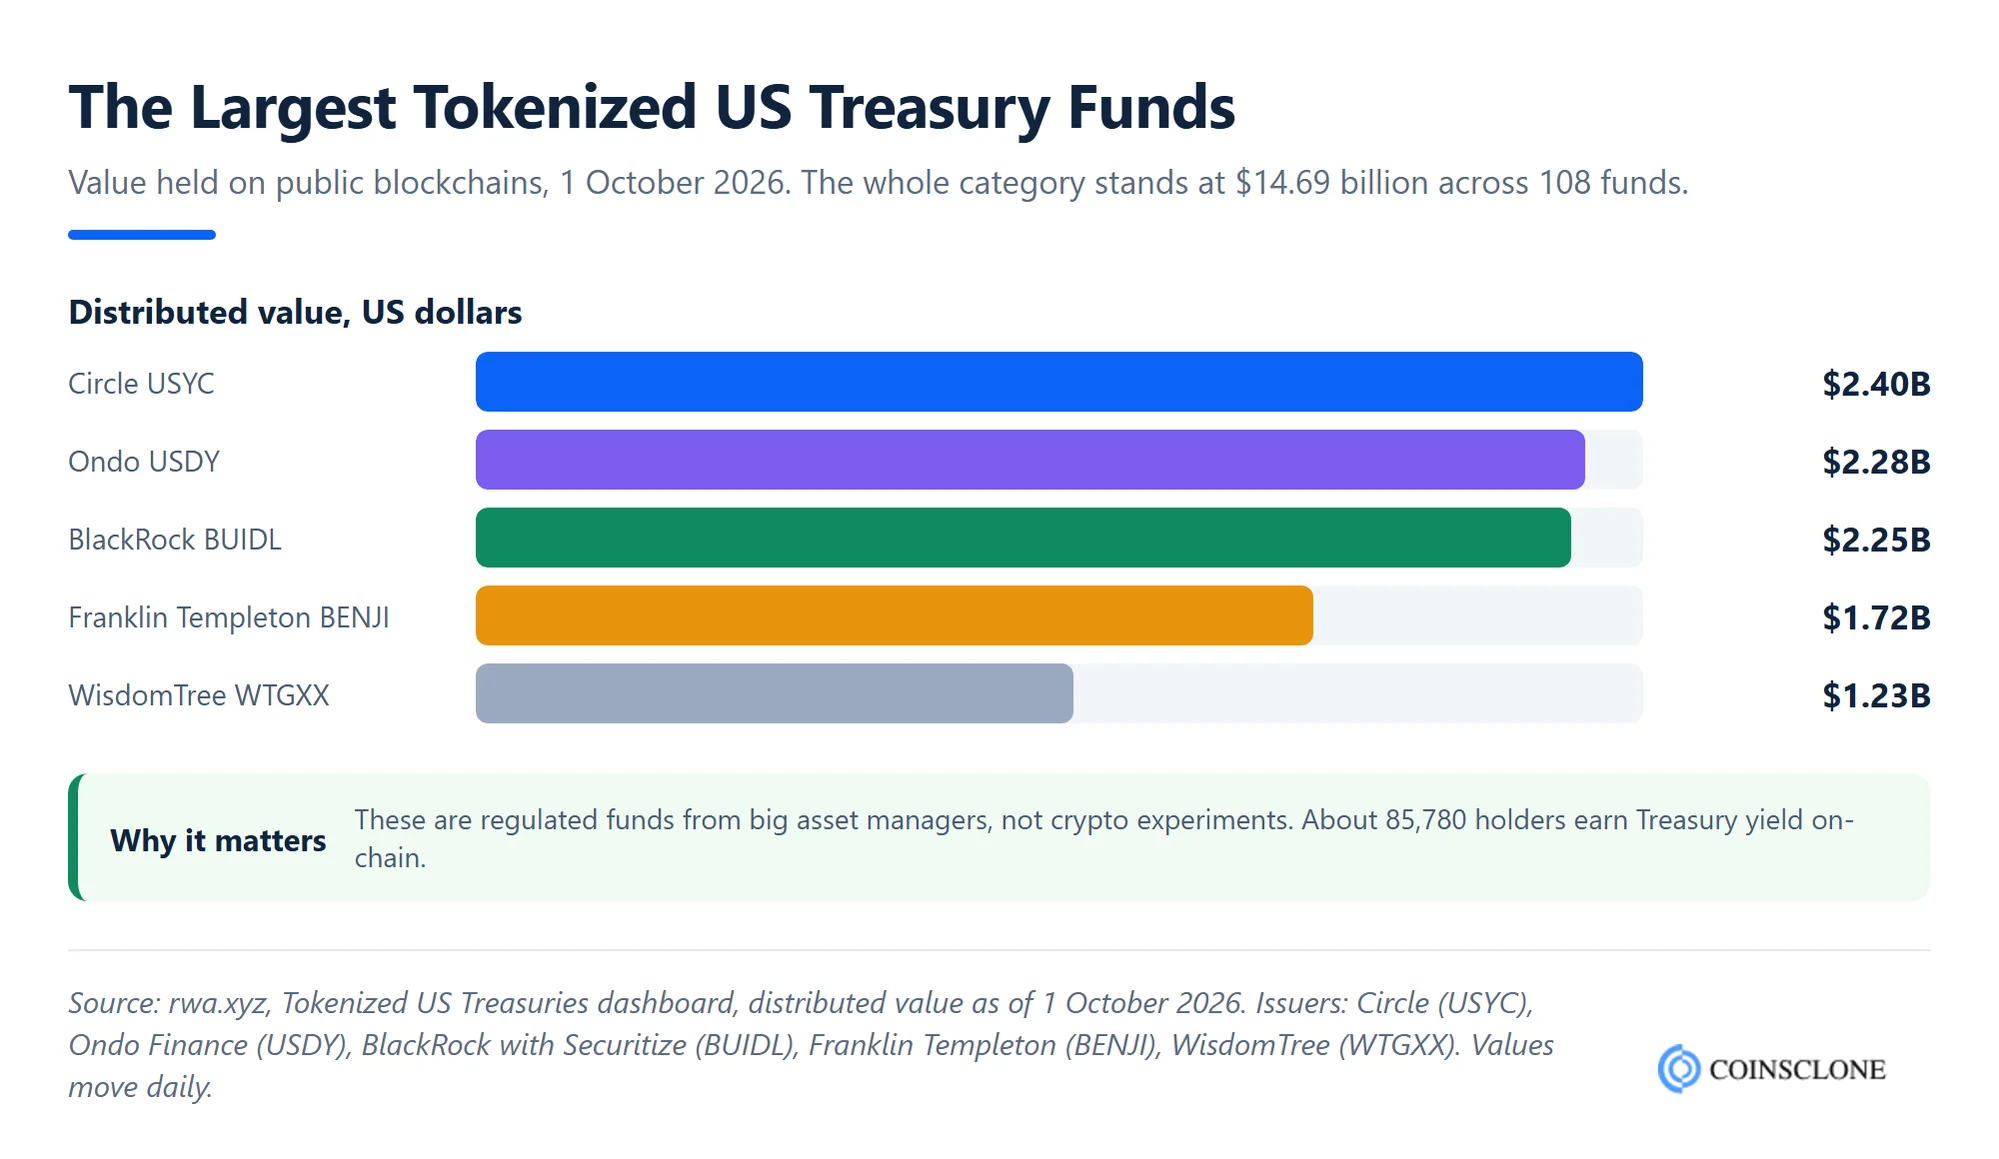
Real case: Tokenized US Treasury funds hold about $14.7 billion. They come from big names such as BlackRock, Franklin Templeton and WisdomTree. Learn more in our guide to real-world asset tokenization.
6. Decentralized Finance (DeFi)
DeFi offers lending, borrowing and trading through smart contracts, with no bank in the middle. Anyone with a wallet can join. About $95 billion sits in DeFi apps today. Lending apps such as Aave and trading apps such as Uniswap are the best known.
7. Regulatory Compliance
Blockchain records are full, dated and hard to edit. So auditors and watchdogs can trace each step almost as it happens. Firms can also build rules into the token itself, such as blocking transfers to unverified wallets. This makes reporting easier and cuts the cost of proving compliance.
8. Stock and Bond Trading
Stock and bond trades still pass through brokers, clearing houses and custodians. In the US, a trade settles one business day later (T+1, since May 2024). On a blockchain, the share and the cash can swap at the same moment. That cuts the risk that one side fails to pay.
Real case: The SEC gave DTCC, the firm behind most US trade settlement, a no-action letter in December 2025. This letter lets it tokenize Russell 1000 stocks, major index ETFs and Treasuries on approved blockchains. Limited live trades began in July 2026, and the full service is set to open in October 2026.
9. Fraud Prevention
Because past entries cannot be quietly edited, blockchain makes it hard to fake records or double-spend funds. Every payment can be traced from start to end. Tools that track wallets on public chains also help firms spot stolen funds and freeze them faster.
10. Financial Auditing
Blockchain makes audits easier because the ledger already holds a full, time-stamped history. Auditors can check records directly, rather than piece them together from many systems. This speeds up the audit and cuts errors. Some stablecoin issuers already publish monthly reserve reports tied to on-chain supply.
So far, you have seen what blockchain can do in finance. Now, to bring your idea to life, you need the right team. Coinsclone has been building blockchain products since 2018, with 350+ platforms delivered for 200+ clients across 20 industries. We build asset tokenization platforms, payment gateways, wallets and exchanges for finance firms.
Real Examples: Who Uses Blockchain in Finance Today
Here are some of the largest live projects as of October 2026. They show that banks, asset managers and payment firms now run real money on blockchain, not just tests.
| Company | What it does on blockchain | Scale or status |
| JPMorgan (Kinexys) | Moves tokenized bank deposits between corporate clients | Over $4 trillion since launch, $7 billion+ a day |
| Swift | Shared ledger for tokenized deposits between banks | Live since July 2026, 17 pilot banks |
| BlackRock (BUIDL) | Tokenized US Treasury money market fund | About $2.25 billion |
| Circle (USDC) | Dollar stablecoin used for payments and trading | About $74 billion in supply |
| DTCC | Tokenized versions of US stocks, ETFs and Treasuries | Live pilot since July 2026, full launch set for October 2026 |
| Large US banks (The Clearing House) | Shared tokenized deposit network | Planned for 2027 |
Types of Blockchain Used in Finance
There are four main types of blockchain. Each one suits a different kind of finance product.
- Public blockchain: Anyone can read, write and hold assets on chains such as Ethereum, Solana and Tron. Used for stablecoins and DeFi.
- Private blockchain: One firm runs the ledger and decides who joins. Used for in-house settlement.
- Consortium blockchain: A group of known firms runs the ledger together. Used for bank-to-bank payments and trade finance.
- Hybrid blockchain: Assets sit on a public chain, but only approved users can hold them. Used for token funds, shares and bonds.
Which public blockchains lead in finance? By stablecoins held, five chains lead. Ethereum holds about $146 billion and Tron about $94 billion. Then come Solana (about $16 billion), BNB Chain (about $14 billion) and Hyperliquid (about $7 billion), per DefiLlama on 1 October 2026. Most token funds also sit on Ethereum.
Challenges and Risks of Blockchain in Finance
Blockchain is not a cure-all. Before you build, weigh these real limits.
- Hacks and lost keys: The ledger itself is hard to break, but apps and keys around it are not. Chainalysis counted $3.4 billion in stolen crypto in 2025. One hack of the Bybit exchange in February 2025 took about $1.5 billion. Security audits and strong key storage are a must.
- Rules still differ by country: The US, EU, UK, UAE and Asia each have their own licences and reporting rules. A product that is legal in one market may need a new licence in the next.
- Speed and cost at scale: Some public chains slow down or get costly when busy. Finance apps often pick faster chains or layer-2 networks, or a permissioned ledger.
- Old bank systems: Most banks run core systems that are decades old. Linking them to a blockchain takes time, money and careful testing.
- Network size: A shared ledger is only useful when enough firms join. Several industry groups closed for lack of users, such as the bank-led we.trade and the insurer-led B3i.
- Privacy: On a public ledger, anyone can see each transfer. Firms need privacy tools or permissioned chains to protect client data.
Rules That Shape Blockchain in Finance in 2026
Clearer rules are a big reason banks moved from tests to live use. Here are the key ones to know.
- United States: The GENIUS Act, signed on 18 July 2025, set the first federal rules for dollar stablecoins, including full reserves. Bank regulators have also eased limits on crypto custody.
- European Union: MiCA has fully applied since 30 December 2024. It covers stablecoin issuers and crypto service firms across all 27 member states.
- Shares and bonds: A share or bond on a blockchain is still a share or bond in law. They need the same licences, investor checks and disclosures as the paper versions.
- AML and the Travel Rule: Crypto firms must share sender and receiver details on transfers in most major markets.
How Much Does It Cost to Build Blockchain-Based Financial Applications?
The cost of a blockchain finance app depends on what it does, which blockchain you use and how you build it. A simple app on a public chain such as Ethereum or Solana mostly needs smart contracts, a wallet link and a clean user interface. A bank-grade system on a permissioned ledger, such as Hyperledger Fabric or Corda, costs much more.
These are the main cost drivers:
- Scope: A payment gateway or a wallet is smaller than a full tokenization platform or a trading venue.
- Chain choice: Public chains cost less to start. Private and consortium chains need nodes, hosting and more setup.
- Security: Smart contract audits and key storage (MPC or hardware modules) are a must for anything that holds money.
- Compliance: KYC, AML, Travel Rule and reporting tools add both build and running costs.
- Upkeep: Hosting, updates, monitoring and new audits continue after launch.
Build time is often easier to plan than cost. These are the times we quote on our service pages:
| Product | Typical build time at Coinsclone |
| White label crypto wallet | 3 to 5 weeks |
| White label crypto exchange | 4 to 6 weeks (7 to 10 with fiat rails) |
| Crypto payment gateway | 6 to 9 weeks (10 to 14 with settlement) |
| Custom crypto wallet | 8 to 12 weeks |
On the whole, whether you build a simple public chain app or a large bank system, plan for both build and upkeep. For a full breakdown, see our guide to blockchain app development costs. Next, let’s look at where blockchain in finance is heading.
Future of Blockchain in Finance
Here is what we expect over the next few years, based on what banks and regulators are already doing.
Tokenized Deposits
Tokenized deposits are simply bank balances that live on a blockchain. Unlike stablecoins, they stay inside the banking system, so banks can still lend against them. JPMorgan already runs them at scale, and large US banks plan a shared tokenized deposit network for 2027. They aim first at business payments abroad and at moving cash between a firm’s own branches.
Central Bank Digital Currencies (CBDCs)
CBDCs are digital money issued by central banks. The Atlantic Council CBDC tracker shows 146 countries and currency unions looking into one. Together they make up over 98% of world GDP. Only three have fully launched: the Bahamas, Jamaica and Nigeria. China’s e-CNY runs one of the largest pilots, and the European Central Bank is preparing a digital euro.
The US is the exception. In January 2025, a White House order banned work on a central bank dollar for the public. Instead, the US is betting on regulated stablecoins.
Looking ahead, we can expect:
- Stablecoins in daily payments: More shops, payroll apps and remittance firms will settle in stablecoins under the new rules.
- 24/7 bank settlement: Deposit tokens will let banks move money at weekends and at night.
- Token markets: Funds, bonds and shares will trade as tokens, settle faster and need less money to get in.
- DeFi meets TradFi: Banks will pledge Treasury tokens to back loans and plug into on-chain lending.
- Better access: More people will reach savings and payments through a phone wallet, without a bank branch.
Frequently Asked Questions
How is blockchain used in finance?
Banks and fintechs use blockchain for payments abroad, stablecoins, trade finance, token funds, shares, DeFi loans, ID checks and audits. Its main job is to give many firms one shared, tamper-proof record, so money and assets can move faster and with fewer middlemen.
What are the four types of blockchain?
The four types are public, private, consortium and hybrid. Public chains such as Ethereum are open to all. Private chains are run by one firm. Consortium chains are shared by a group of known firms. Hybrid chains mix public access with approved-only holders.
What are the top 5 blockchains?
For finance, a good guide is how many stablecoins each chain holds. On that basis, Ethereum, Tron, Solana, BNB Chain and Hyperliquid lead, per DefiLlama in October 2026. Ethereum leads by a wide margin and also hosts most tokenized funds.
Is blockchain real or fake?
Blockchain is real and in daily use. JPMorgan’s Kinexys settles over $7 billion a day, and stablecoins on public blockchains hold over $310 billion. Many crypto tokens are risky or worthless, but the ledger technology itself is proven.
How do you explain blockchain in simple terms?
Picture a shared notebook that many people hold a copy of. Each new page links to the last one, so nobody can secretly change an old page. In finance, that notebook records who owns what, so firms can trust it without checking each other’s books.
Is blockchain secure enough for financial transactions?
The ledger itself is very hard to tamper with. Most losses come from weak smart contracts, stolen keys or hacked exchanges, not from the chain. With code audits, strong key storage and good controls, banks now run trillions of dollars on blockchain.
Will blockchain replace banks?
Not likely. Banks are adopting blockchain rather than being replaced by it. They now use it as new pipes inside the system, through bank-run ledgers, deposit tokens and stablecoins under clear rules. DeFi still offers a separate route for some services.
To Sum It Up
Blockchain in finance is no longer a future idea. It now moves real money every day: stablecoins hold over $310 billion, banks settle billions on shared ledgers, and big asset managers sell funds as tokens. Clearer rules in the US and EU have sped this up. Still, hacks, old systems and patchy rules mean every project needs careful design. For more ideas on what to build, see these fintech startup ideas.
At Coinsclone, we help firms turn these ideas into working products. Since 2018, we have delivered 350+ platforms, from payment gateways and wallets to exchanges and tokenization platforms. If you plan to bring blockchain into your finance business, our team can help you scope it, build it and launch it securely.
Blockchain-Powered Financial Solutions for the Future
Secure, Fast, and Transparent Finance Solutions with Blockchain. Fully Customizable to Fit Your Needs.